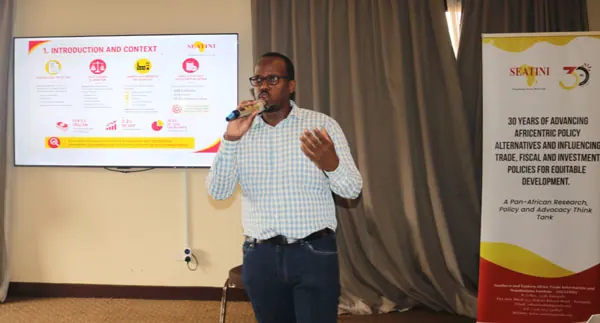
Uganda's tax policy is facing a critical examination as the country strives to achieve a $500 billion economy by 2040. The government's Tenfold Growth Strategy aims to expand the economy from approximately $50 billion to $500 billion, partly by increasing the share of the formal economy and creating a larger domestic revenue base. However, this ambitious plan has raised concerns about the revenue sacrificed through tax exemptions, holidays, and other incentives. A recent study by the Southern and Eastern Africa Trade Information and Negotiations Institute (SEATINI-Uganda) estimates that Uganda's tax expenditure reached Shs5.01 trillion in FY2024/25.
The study, conducted in partnership with the Uganda Revenue Authority (URA) and supported by the Embassy of Ireland, reveals that tax expenditure in Uganda is substantial, equivalent to about 2.2% of GDP and 15.5% of total tax collections. The majority of tax expenditure comes from VAT, personal income tax, excise duty, customs duty, and corporate income tax. For instance, VAT accounted for about Shs2 trillion, while personal income tax accounted for roughly Shs1 trillion. This significant revenue gap has sparked a policy debate on the effectiveness of tax incentives in driving economic growth.
Tax incentives can be used to attract investment, create employment, encourage exports, and accelerate industrialization. However, every exemption also means the government collects less from a particular activity, company, household, or sector. Solomon Rukundo, a tax specialist at the Ministry of Finance, Planning and Economic Development, emphasized that tax expenditures were costing the country about Shs5 trillion in FY2024/25. The distribution of tax expenditure across various tax heads and beneficiaries, including individuals, public institutions, and households, highlights the complexity of the issue.
The debate over tax incentives is often framed around investors, but the evidence suggests that the issue is considerably broader. Under personal income tax, security personnel, retirement fund contributions, and Members of Parliament were among the major beneficiaries during the period examined. Under VAT, mining, oil and gas, and government projects accounted for a substantial share of the relief. This means tax expenditure is not merely an investment-promotion instrument but also a central component of fiscal policy, social policy, and income distribution.
Uganda's government has a clear reason for wanting to maintain an investment-friendly tax regime, as the Tenfold Growth Strategy is designed to push the economy towards double-digit growth. The strategy identifies agro-industrialization, tourism, mineral development, and science, technology, and innovation as key anchors. Tax incentives can be viewed as one instrument for achieving structural transformation. However, incentives only make economic sense if the investment and other benefits they generate are sufficiently large, additional, and sustainable.
The study provides evidence on both sides, showing that investment-related incentives have expanded considerably, with the number of firms benefiting from the strategic investor tax holiday increasing from two in 2018 to 123 in 2025. Beneficiary firms recorded increases in investment, turnover, profits, wages, and purchases after receiving incentives. However, another finding complicates the picture: imports grew more strongly than local purchases, while the share of local sourcing declined. This distinction is important for the Tenfold Growth Strategy, as attracting a company is one objective, but building an economy in which that company purchases more from Ugandan suppliers, employs Ugandans, and adds value is another.
The emerging policy direction is towards greater scrutiny of incentives rather than eliminating them. Experts argue that incentives could increasingly be treated as performance-based fiscal instruments, with measurable targets and conditions. Jane Nalunga of SEATINI-Uganda emphasized the public-interest dimension of the debate, stating that tax expenditure is public money, even when it does not appear as a conventional budget allocation. The government must monitor and evaluate the effectiveness of tax incentives to ensure they are generating sufficient economic and social value to justify the cost.
Key points
- Uganda's tax expenditure reached Shs5.01 trillion in FY2024/25, equivalent to about 2.2% of GDP and 15.5% of total tax collections.
- The government is pursuing an ambitious economic transformation programme under the Tenfold Growth Strategy, which seeks to expand the economy from roughly $50 billion to $500 billion by 2040.
- Tax incentives could increasingly be treated as performance-based fiscal instruments, with measurable targets and conditions.