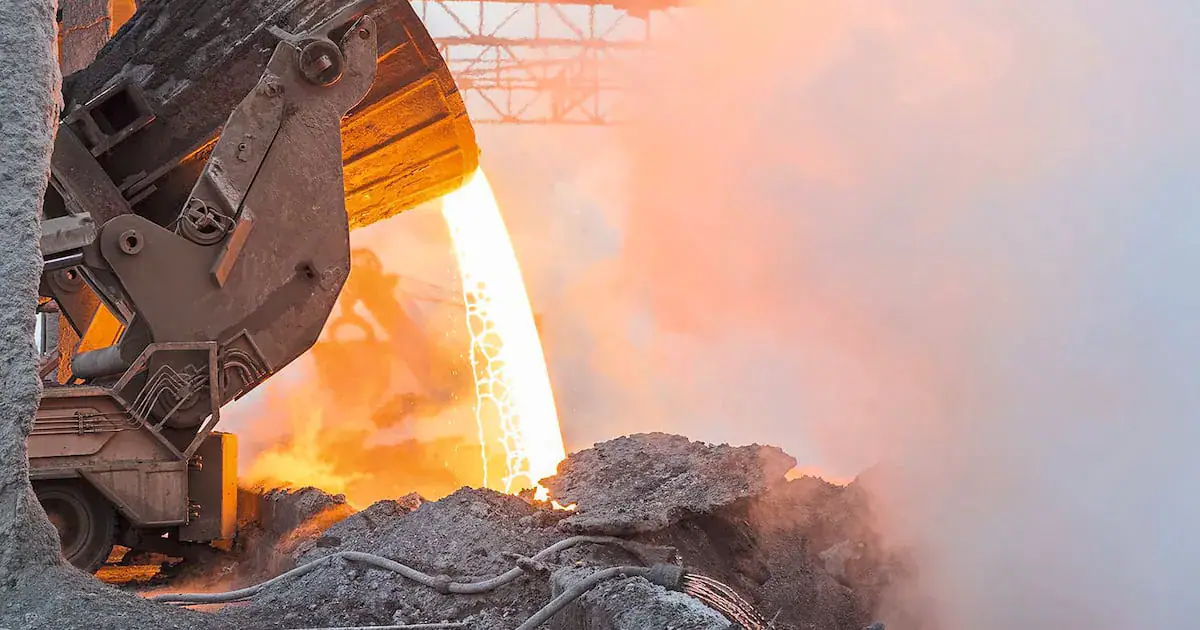
South Africa's chrome industry is experiencing a significant shift in its production and export patterns. In the second quarter of 2026, the country exported 7.3-million tonnes of chrome ore, a 28% increase from the previous year. Conversely, ferrochrome exports declined by 18% to 364,000 tonnes. This trend is notable, given that South Africa boasts the world's largest chrome deposits and is the largest exporter of chrome ore, with production exceeding 23-million tonnes in 2025.
The South African government has attempted to support the ferrochrome industry by offering cheaper electricity. Electricity and energy minister Kgosientsho Ramokgopa reduced the electricity tariff for ferrochrome producers to 62c/kWh, down from 80c/kWh two years ago. This move was made possible by Eskom's surplus generating capacity. However, the impact of this tariff reduction on the industry's competitiveness remains to be seen. Electricity accounts for 30%-40% of ferrochrome production costs, making tariff relief a crucial factor.
Despite the benefits of cheaper electricity, the ferrochrome industry faces significant challenges. Only 11 of the 66 furnaces operating in 2008 remain, highlighting the sector's decline. The National Energy Regulator of South Africa's decision on amended tariff arrangements for Glencore and Samancor provides context for the industry's struggles. The proposed tariff implies an electricity bill of about R2,170-R2,480 per tonne of ferrochrome. At an assumed ferrochrome spot price of $4,500 per tonne, estimated cash costs of $3,600-$4,200 leave a nominal spread of $300-$900.
The competitive disadvantage faced by South African smelters is exacerbated by China's ferrochrome industry, which combines scale, integrated supply chains, and substantial processing capacity. Estimates suggest that Chinese smelters can obtain electricity at below four US cents per kWh, giving them a significant advantage. Some estimates put the margin advantage over South African producers at $1,200-$1,500 per tonne. However, these figures require verification through like-for-like comparisons.
The challenges facing South Africa's ferrochrome industry extend beyond electricity costs. The country's transportation infrastructure, particularly rail, has deteriorated, leading to increased costs for producers. Transnet's decline has resulted in a shift from rail to road transport, with estimates suggesting that roads now carry a similar share of chrome ore as rail once did. Road transport is estimated to cost $50-$80 more per tonne than efficient rail.
A co-ordinated strategy is needed to address the industry's challenges and restore competitiveness. Industrial policy should focus on setting measurable targets for competitive production, exports, investment, and downstream value addition, with clear accountability for delivery. This would involve a comprehensive approach, including rail rehabilitation, trade measures, and investment in higher-value products. The aim would be to create a production base capable of competing in alloys and stainless steel semi-products.
The investment challenge facing South Africa's ferrochrome industry is substantial. The draft national rail master plan estimates that restoring rail as the backbone of the country's logistics and mobility system will require R1.9-trillion over a decade. Using Eskom's surplus capacity to support industry has a reasonable economic case, but discounted power must be judged against the value it creates: sustainable jobs, export earnings, and domestic processing.
Key points
- Cheap electricity is not enough to save South Africa's smelters; a comprehensive strategy addressing transportation, industrial structure, and competitiveness is needed.
- China's ferrochrome industry has a significant advantage over South African producers due to its scale, integrated supply chains, and low electricity costs.
- A co-ordinated industrial policy with measurable targets and accountability is required to restore the competitiveness of South Africa's ferrochrome industry.