South African mining and materials company Afrimat has announced that it expects to report a significantly lower earnings for the first half of the year. The company attributed the decline to a stronger rand and a nearly 50% increase in shipping costs, which negatively impacted its iron ore exports. As a result, Afrimat expects to report a headline loss per share of between 55c and 60c for the six months to end-August.
The company's earnings per share (EPS) is expected to be between 0.1c and 5.2c, representing a decrease of between 95% and 100% from the previous year. Afrimat stated that the difference between EPS and the headline loss per share is primarily due to profits recognized on the completion of Competition Commission-mandated divestitures and disposal of non-core assets. These profits are excluded from headline earnings.
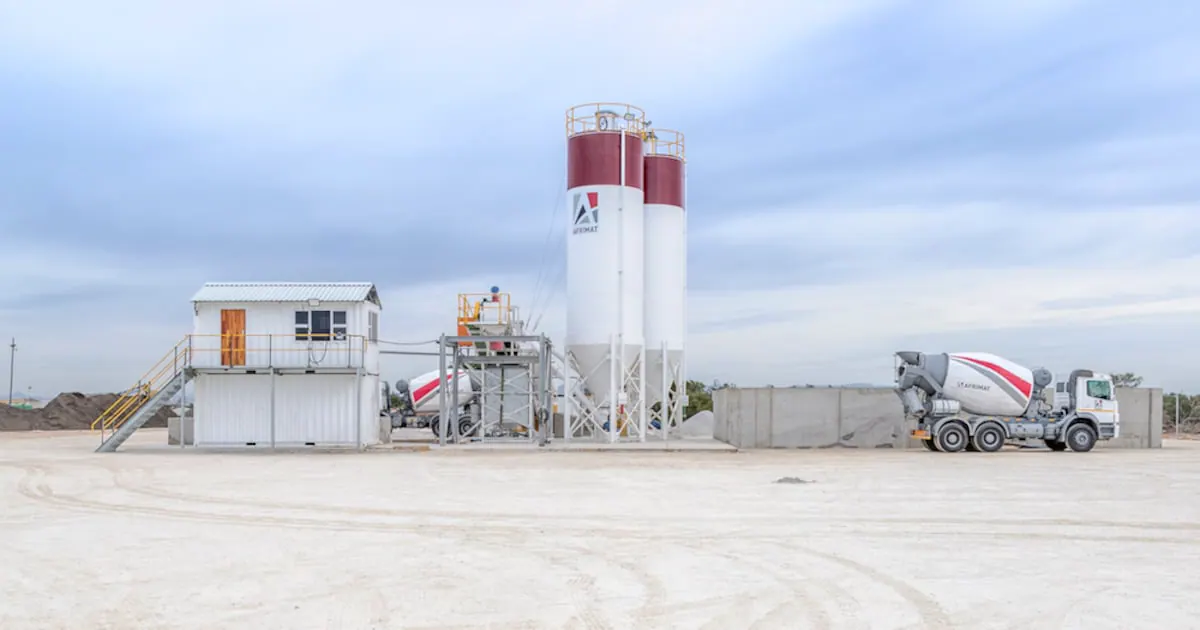
Afrimat disposed of some of its general aggregate quarries and readymix concrete plants across South Africa as part of the conditional approval of the Lafarge South Africa merger. The disposals were stipulated by the Competition Tribunal in April 2024. The company noted that it has never faced trading conditions as challenging as those experienced during the period, resulting in a significantly weaker financial performance.
The primary driver of the decline in profitability was iron ore, with export revenue adversely impacted by a combination of a stronger rand and higher shipping costs. Average mine-gate revenue per tonne was down by 16.4% due to these factors. Domestic iron ore was also affected in the first quarter as a domestic customer drew on non-Afrimat stockpiles, leading to lower and irregular sales volumes.
However, Afrimat's aggregate and fly ash operations performed strongly, supporting the original rationale for the acquisition of the Lafarge quarries. The company attributed the positive performance to ongoing efficiency drives, effective marketing, strong client retention, and sound operational performance. This resulted in margin expansion and strong operating profit growth.
Despite investing in strengthening engineering and management capacity, the cement operation continued to incur an operating loss during the early part of the period. The group has focused on cash generation through the disposal of non-core assets and converting surplus iron ore stockpiles into cash. This has reduced the debt-to-equity position to below 50%, with a target of closer to 25%.
Afrimat continues to add diversified capacity, including a new Manganese Export Capacity Allocation III manganese allocation of 240,000 tonnes a year for seven years. The company will release its interim results on October 22.
Key points
- Afrimat expects a headline loss per share of between 55c and 60c for the six months to end-August.
- The company's earnings per share is expected to be between 0.1c and 5.2c, representing a decrease of between 95% and 100% from the previous year.
- Afrimat's aggregate and fly ash operations performed strongly, resulting in margin expansion and strong operating profit growth.