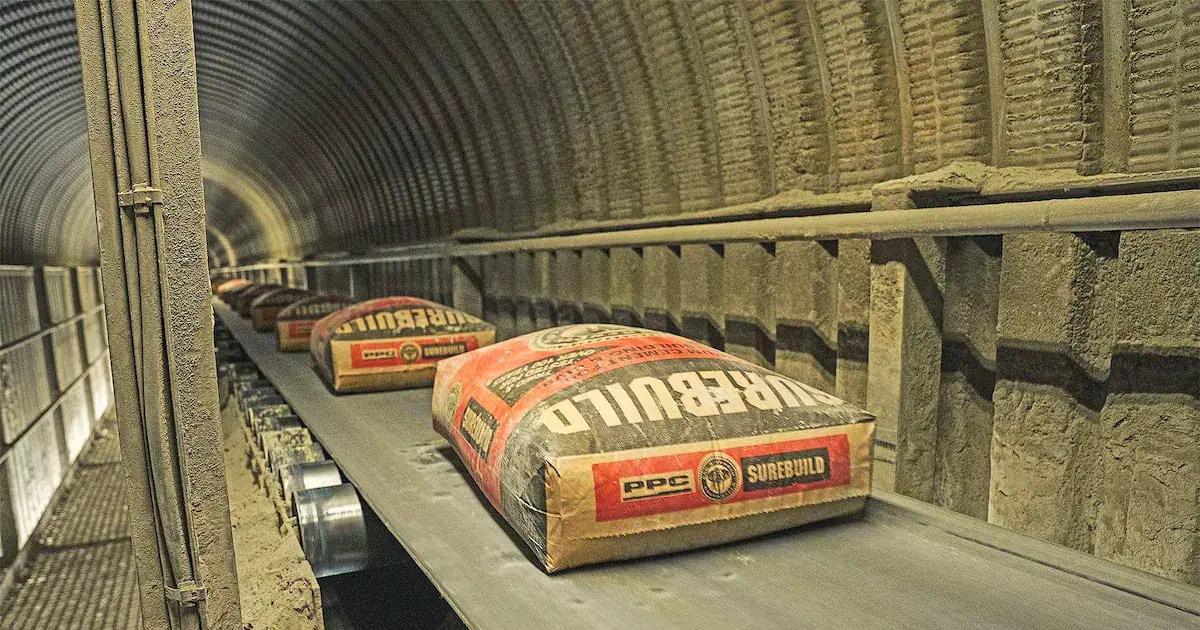
Cement producer PPC has reported a significant increase in first-half earnings, driven by a strong contribution from its Zimbabwean unit and improved performance in its South African cement business. The company's "Awaken the Giant" turnaround strategy continues to yield positive results, with earnings growth maintained despite challenging trading conditions in some markets. PPC's revenue rose 1.7% to R5.47bn for the six months to end September.
PPC's trading profit surged 31.7% to R906m, while earnings before interest, tax, depreciation, and amortisation (ebitda) increased by almost a quarter to R1.2bn. This lifted the group's margin by 3.9 percentage points to 22.2%. Headline earnings per share rose 28% to 32c. The company's cost of sales increased marginally, while administration and other operating expenses declined during the period.
The Zimbabwean unit delivered higher cement volumes and revenue, driven by robust demand from the industrial and retail sectors. PPC attributed the improved profitability in Zimbabwe to higher own-clinker production and strong operating performance at the Colleen Bawn kiln. This was achieved despite higher coal and diesel prices, which pushed up costs. In contrast, PPC reported weaker cement volumes in South Africa and Botswana, where sales fell by 7.9%.
According to PPC CEO Matias Cardarelli, the gains from the "Awaken the Giant" turnaround are structural and sustainable. The company has protected its earnings in South Africa and grown them in Zimbabwe, while investing in future competitiveness and maintaining a strong balance sheet. Cardarelli emphasised that the company's progress is on track, with a focus on long-term sustainability.
PPC is continuing work on its new integrated cement plant, RK3, in the Western Cape. The project is on track for completion in the final quarter of the 2027 financial year and within its approved budget. To date, the company has spent R2.2bn on the RK3 plant. Construction has progressed, with engineering and procurement substantially complete and civil works more than 85% finished.
The RK3 project is expected to drive the next improvement in group performance, with commissioning anticipated in the 2028 financial year. However, the investment has increased the group's debt, with net debt rising to R787m at the end of September, compared with a net cash position at the end of March. PPC attributed the change to borrowing to fund RK3 and payment of its final dividend for the previous financial year.
Looking ahead, PPC expects trading conditions in the South African cement market to remain challenging, with price discounting and higher diesel costs continuing to put pressure on the business. However, the company anticipates improved margins and continued volume growth in Zimbabwe to support its performance in the second half. The group also expects the second half to be seasonally softer due to the slowdown in construction activity over December and January.
Key points
- PPC's trading profit increased by 31.7% to R906m.
- The company's Zimbabwean unit delivered higher cement volumes and revenue.
- PPC's new integrated cement plant, RK3, is on track for completion in the final quarter of the 2027 financial year.
Reporting sources
- # 2 Strong Zimbabwe contribution lifts PPC’s earnings · The Rand Daily Mail