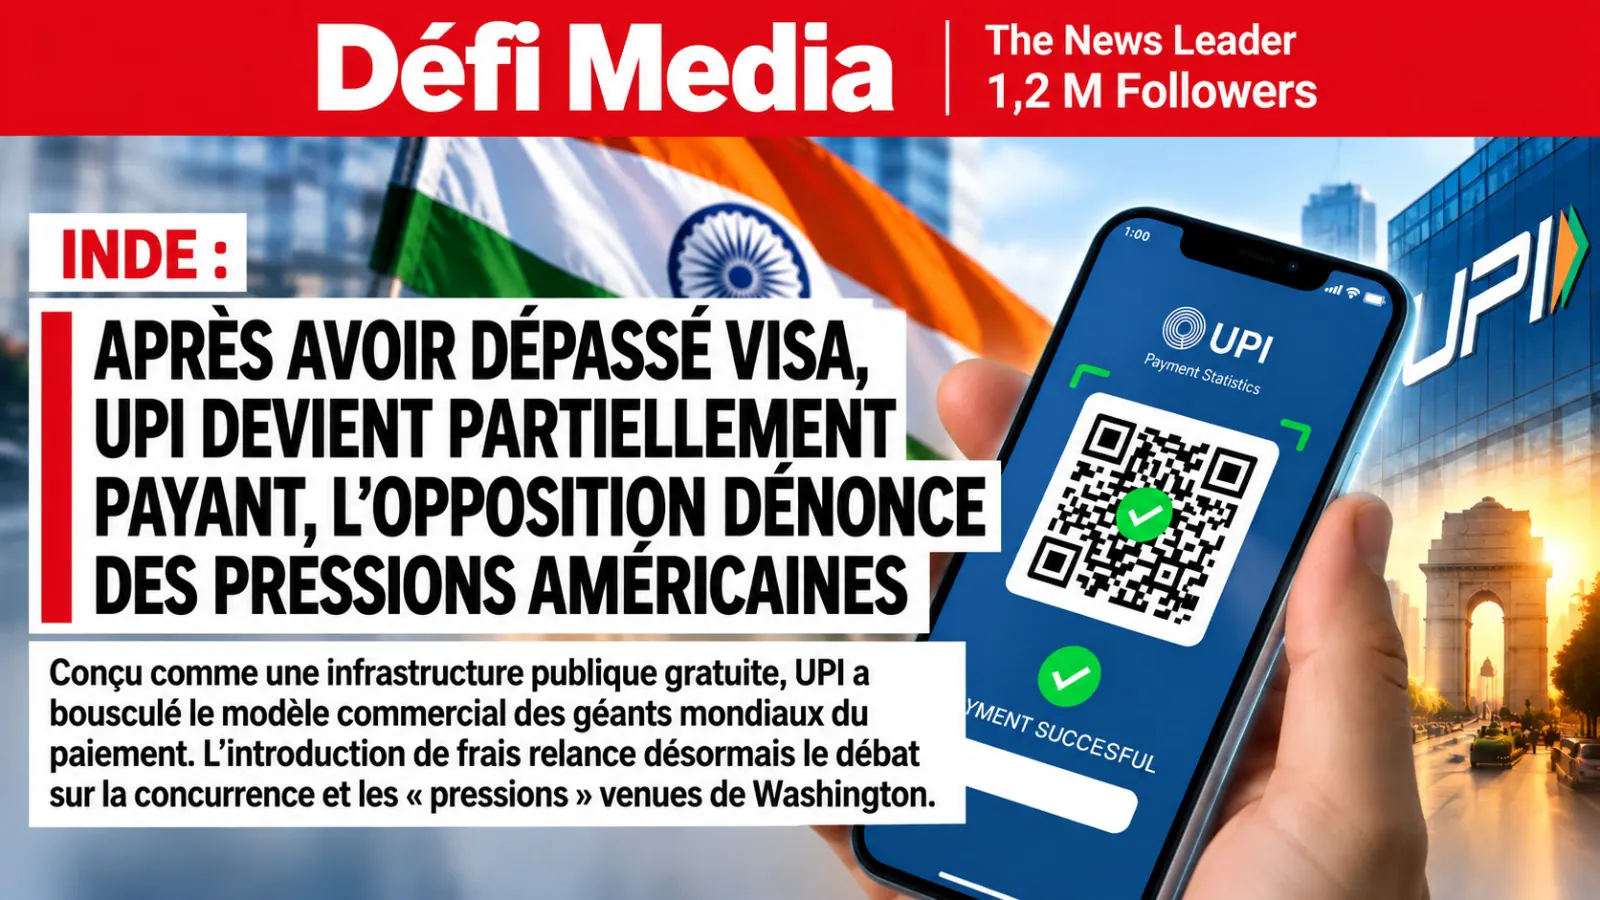
The Indian government's Unified Payments Interface (UPI) system, hailed as a digital public good, has revolutionized payments in the country. Introduced with free transactions, UPI's popularity soared, surpassing Visa in daily transactions. With over 2 billion transactions monthly, UPI has become a major player in India's digital payments landscape. The government's decision to waive Merchant Discount Rate (MDR) fees in 2020 boosted adoption. UPI's growth has been remarkable, with transaction value increasing tenfold in six years.
The US has expressed concerns about India's payment rules, citing favoritism towards local providers. The Office of the United States Trade Representative (USTR) raised issues with India's policies on electronic payments, which they claim hinder foreign competitors. Washington also questioned access to certain components of India's payment ecosystem, including credit transactions via UPI and the national RuPay card network. These concerns have sparked debate about potential pressure on India to alter its UPI system.
From October 15, India will introduce a 0.4% MDR on UPI transactions above 2,000 rupees with merchants. Transfers between individuals will remain free. The National Payments Corporation of India (NPCI) set a cap of 300 rupees for transactions above 75,000 rupees. This fee is significantly lower than traditional card payment commissions, which range from 0.9% for debit cards to 1.5-2.5% for credit cards. UPI will maintain a substantial cost advantage over international card networks.
The opposition has accused the government of ceding to US pressure, with Rahul Gandhi, leader of the Congress party, criticizing the move. The government denies this, stating that UPI decisions are made independently. The finance ministry views the new fee as essential for ensuring the long-term viability of India's digital payments ecosystem. The controversy highlights the challenges of balancing domestic priorities with international pressures.
The introduction of MDR could generate significant revenue for banks and fintech companies participating in the UPI ecosystem. According to estimates, the new fee could yield 245 billion rupees (approximately $2.5 billion) in revenue. However, this may not necessarily benefit Visa and Mastercard, as the 0.4% fee remains much lower than credit card commissions. Merchants are likely to continue preferring UPI due to its cost advantage.
The shift towards monetizing UPI transactions marks a significant change for a system hailed as a digital public good. The government's decision has sparked concerns about potential impacts on the payments landscape. While the opposition alleges a link between US pressure and the new fee, the government disputes this claim. The development highlights the complexities of India's digital payments ecosystem and the challenges of balancing competing interests.
As India navigates the complexities of its digital payments landscape, the UPI system will continue to play a vital role. With its user-friendly interface and cost-effective transactions, UPI has become an essential tool for millions of Indians. The introduction of partial charges will likely have a minimal impact on users, but it may pave the way for further innovations in the country's digital payments sector.
Key points
- India to introduce 0.4% fee on some UPI transactions from October 15.
- The US has expressed concerns about India's payment rules, citing favoritism towards local providers.
- The opposition has accused the government of ceding to US pressure over the new UPI fee.