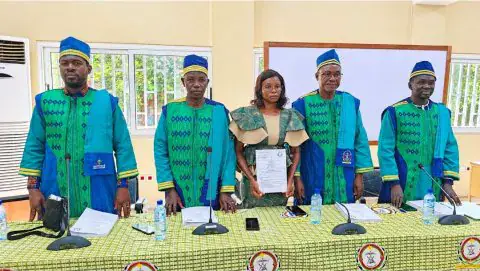
Pascaline Ouédraogo/Ilboudo has successfully defended her doctoral thesis in applied mathematics at the University of Joseph Ki-Zerbo, earning her a doctorate with a very honorable mention. Her research focuses on using applied mathematics to anticipate and evaluate financial risks for insurance companies. The thesis, titled "Non-Markovian Processes and Multivariate Modeling of Phase-Type Insurance Risk," explores mathematical and probabilistic tools to improve understanding and prediction of risks faced by insurance companies.
Ouédraogo/Ilboudo's research aims to address key questions for insurance companies, such as determining whether they have sufficient financial resources to indemnify clients when multiple claims occur in a short period. Her work uses the Hawkes process, a probabilistic tool that represents self-exciting phenomena, where the occurrence of one claim can increase the likelihood of subsequent claims. This approach allows for a more nuanced understanding of the interactions between claim frequency and cost.
The researcher constructed a new classical risk model based on the Hawkes process and used phase-type law distributions to represent claim amounts. These distributions offer flexibility in describing different levels of costs and variations in indemnifications. Ouédraogo/Ilboudo also employed copulas, mathematical tools that measure and represent relationships between multiple random phenomena. Her model uses the Spearman copula to describe the dependence between claim amounts and the time separating one claim from the previous one.
One of the significant contributions of this research is the evaluation of the probability of ruin, which measures the risk that an insurance company may not have sufficient resources to meet its financial obligations. Ouédraogo/Ilboudo studied this issue using the Gerber-Shiu function, a mathematical tool used in risk theory to analyze an insurer's financial situation at the time of ruin. Her work established an integro-differential equation associated with this function and the Laplace transform of the probability of ruin.
The research also evaluated the joint probability of ruin for two insurance branches over a finite time horizon, using the Clayton copula to represent their dependence. This approach allows for the study of how financial difficulties in one branch can be linked to those in another. The study led to the establishment of formulas for dependence coefficients, an asymptotic approximation of the probability of ruin, and closed formulas for the bivariate probability of ruin.
Ouédraogo/Ilboudo's thesis also proposed a numerical method for approximating the risk of bankruptcy, using a collocation method based on Gauss-Lobatto points to solve the integro-differential equation associated with her model. The theoretical and numerical results show that this method provides consistent approximations of the probability of ruin and confirms a fundamental principle of risk management: the higher the initial capital of an insurance company, the lower its probability of ruin.
The tools developed in this research could contribute to informing insurance companies' decisions on reserve management, risk exposure evaluation, and financial planning. The study was supervised by Dr. Frédéric Béré, a lecturer at the École normale supérieure, and conducted within the École doctorale sciences et technologies, with scientific support from the Laboratoire d'analyse numérique, d'informatique et de biomathématiques (L.A.N.I.BIO) at the University of Joseph Ki-Zerbo.
Key points
- Ouédraogo/Ilboudo's research provides a new approach to modeling insurance risks using applied mathematics.
- The study proposes a numerical method for approximating the risk of bankruptcy.
- The research has implications for insurance companies' risk management and financial planning.