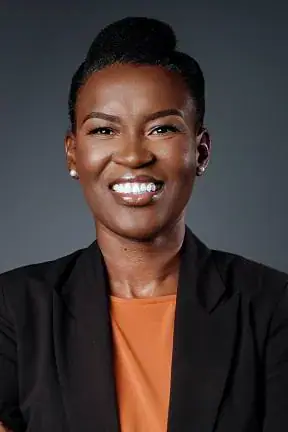
Businesswoman Ally Angula has approached the High Court to have over N$26.7 million recognised as tax deductions. She claims nearly N$24 million was advanced to keep Leap Holdings operating and protect herself from bankruptcy. Angula wants the court to overturn decisions by the Namibia Revenue Agency (Namra) and the tax tribunal rejecting her deductions for the 2014, 2015 and 2016 tax years.
Angula served as managing director and shareholder of Leap Holdings (Pty) Ltd, signing a loan agreement and managing director founder agreement on 1 March 2013. Under the loan agreement, she undertook to provide working capital for the company and its subsidiaries whenever required. The advances covered salaries, suppliers and creditors after she personally guaranteed the company's debts.
The tribunal rejected her argument, finding that Leap Holdings was a separate taxpayer and that the advances did not qualify as deductions against income from her chartered accountancy practice. Angula wants the High Court to set aside Namra's objection decision of 19 September 2025 and the tribunal's ruling of 4 August 2026 and uphold her original tax returns.
Namra's audit findings letter, dated 22 April 2024, lists N$26 753 462 in disallowed expenses across the three tax years, mainly involving bad debts. In 2014, Namra disallowed approximately N$4.6 million in bad-debt-related expenses, N$213 398 in trade-related motor vehicle expenses and N$141 766 in farming expenses.
Angula also disputes the rejection of N$1 668 857 in interest and related expenses, including costs associated with personal suretyships, storage, insurance, legal services and her former KPMG partnership. She said creditors pursued her personally after Leap Holdings defaulted, forcing her to service the debts to avoid judgments and bankruptcy proceedings.
Angula argues that Namra's decisions were affected by administrative failures, incorrect income classification and the rejection of legitimate business expenditure. She accuses Namra of incorrectly classifying her professional earnings as employment income rather than income from independent consultancy work.
The dispute also covers farming expenses and capital allowances claimed for a tractor. Angula argues that the expenses were necessary to preserve her professional income and should not have been treated as personal or capital expenditure.
Key points
- Ally Angula seeks to overturn Namra and tax tribunal decisions rejecting N$26.7m in tax deductions.
- The dispute involves tax deductions claimed for advances made to Leap Holdings, her chartered accountancy practice, and other business expenses.
- Angula accuses Namra of administrative failures, incorrect income classification, and rejection of legitimate business expenditure.
Reporting sources
- Angula takes N$26.7m tax fight with Namra to court Image - Namibian Sun · namibiansun.com