A recent analysis has highlighted the stark contrast in corporate performance between the United States and South Africa. In the US, profits as a share of gross value added (GVA) of nonfinancial corporations have risen from around 10% in 2019 to approximately 16% currently. This surge in profits is largely attributed to increased efficiency and investments in capacity growth. In contrast, South African nonfinancial corporations, which account for about 60% of GVA or GDP, have experienced tepid top-line GVA growth, with real growth in GVA of less than 5% between 2019 and 2025.
The differences in corporate performance between the two countries are further evident in their bottom-line growth. While US corporations have seen a significant surge in efficiency, South African corporations have not exhibited a similar trend. The profit ratios of South African corporations, both at the gross and net levels, have remained largely unchanged since 1995. The share of the operating surplus in GVA has hovered around 50%, and the ratio of income after taxes has remained steady at around 20% per annum.
One of the most concerning aspects of South Africa's corporate performance is the stagnation of capital expenditure (capex). Adjusted for inflation, capex is currently running at approximately the same level as in 2005. The ratio of capex to GVA has declined from 24% in 2012 to less than 18% currently. Similarly, the ratio of capex to household consumption spending has followed a similar pattern. This reluctance to invest in capacity growth is likely to depress GDP growth in the country.
The lack of growth in South African corporations can be attributed to various factors, including supply-side constraints. Lockdowns and logistic failures have hampered the economy, making it challenging for businesses to meet potential demand for exports. However, supply-side reforms aimed at introducing private-style incentives are underway, which promise to relieve some of the constraints on meeting foreign demand and encourage more capex.
In contrast to South Africa, US corporations have benefited from a growing domestic market. The average South African business, however, has not experienced similar encouragement, with household consumption spending adjusted for inflation growing by only 7.5% since pre-Covid 2019. The flat ratio of capex to household consumption spending reveals the dependence of capex on final demands.
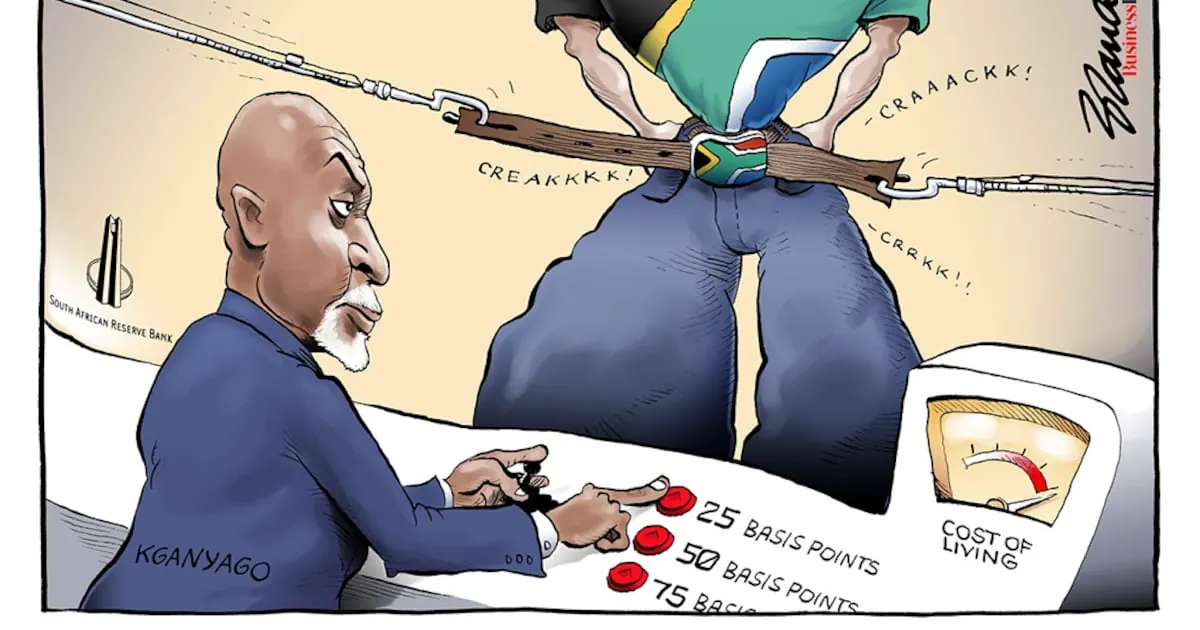
To stimulate growth, it is essential to increase household spending, which in turn would encourage capex. The aim of monetary policy should be to target annual household spending growth of around 3%, with more accommodating interest rate settings to make such growth and growth in bank lending possible. However, with the recent oil price shocks, the Reserve Bank has raised interest rates, which is likely to slow down household spending growth.
The South African economy is likely to face challenges in the coming months due to the supply-side shock caused by the oil price and higher interest rate pressure. Faster growth will have to wait for lower inflation and interest rates. The Reserve Bank is unlikely to change its approach, prioritizing inflation targeting over sensitivity to the state of the economy.
Key points
- US corporations have seen significant gains in profits, while South African corporations have struggled with tepid growth.
- South African corporations have been reluctant to invest in capacity growth, with capex stagnating at around the same level as in 2005.
- To stimulate growth, it is essential to increase household spending, which in turn would encourage capex.