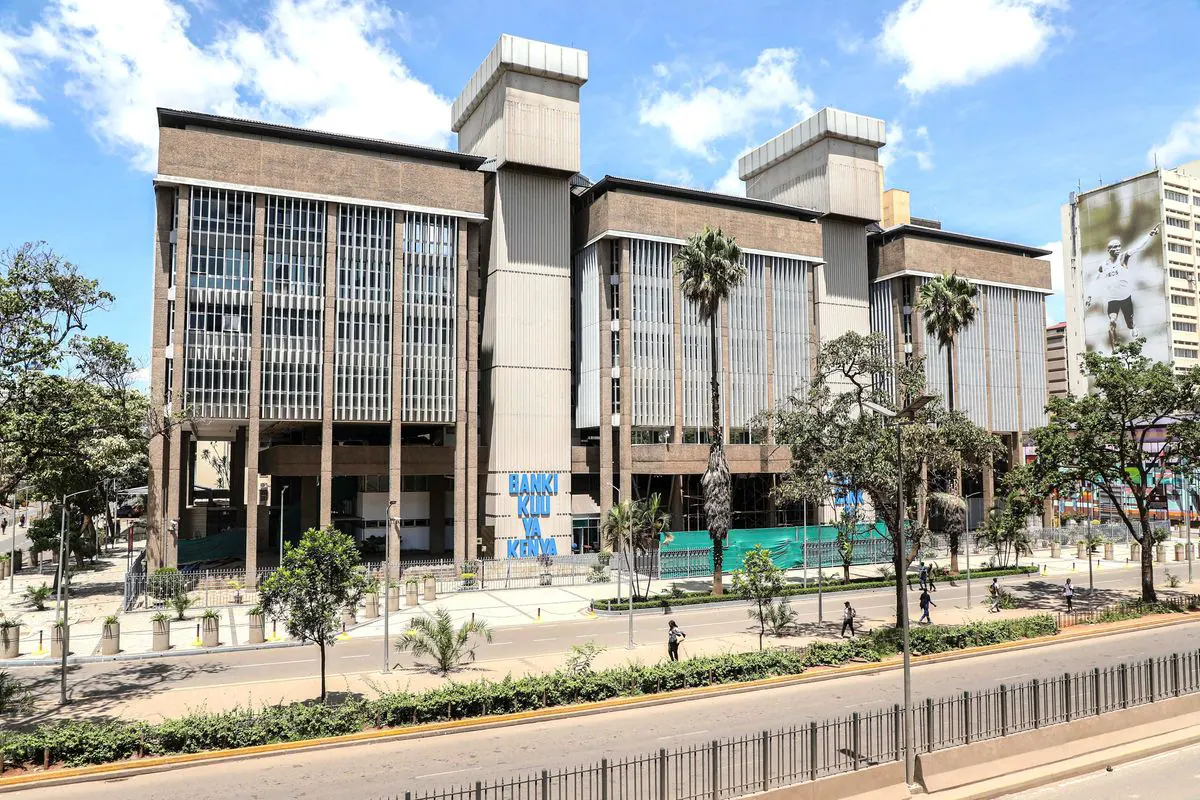
The Central Bank of Kenya (CBK) has introduced new regulations that have raised concerns among non-deposit-taking credit providers (NDTCPs). The rules, published by CBK Governor Kamau Thugge, outline the order in which funds from loan repayments will be distributed. According to the regulations, funds will first offset the principal amount, then fees and charges, and finally interest. This has caused anxiety among NDTCPs and analysts, who argue that the new rules are unclear.
The new CBK rules reverse the traditional sequential payment hierarchy used to distribute recovered loans. Analysts at law firm Bowmans pointed out that the traditional hierarchy prioritizes agency costs, then interest and fees, then principal. The experts argue that the new rules may not be suitable for all types of lenders, including corporate, cross-border, and wholesale lenders. They also raised concerns about the lack of carve-outs for foreign lenders, Development Finance Institutions (DFIs), and representative offices.
The CBK regulations follow amendments to the CBK Act, which aim to clarify and widen the scope of operations of NDTCPs. The new regulations place a big emphasis on consumer protection, with the CBK setting tough terms on key areas such as credit terms and handling of personal information. NDTCPs will be required to formulate a credit policy consistent with the Act and aligned to the size of the provider and the nature and complexity of the products offered.
The CBK has set strict rules for NDTCPs introducing new products or varying existing ones. Providers will need to justify changes and notify customers of planned changes at least 30 days before they take effect. They will also be required to provide a unique identifying account number issued by a mobile money operator for disbursements and repayments of loans.
The CBK regulations also cover digital platforms, requiring providers to make provision for unsubscribing or opting out from services, including receiving marketing messages upon full repayment of the loan. Providers will need to ensure that customers can opt out of receiving marketing and promotional communication.
The regulations also cover loan restructuring, allowing NDTCPs to restructure loans in terms of instalment amount, payment period, or other terms upon receipt of a request from a borrower or on prior notification to the customer. However, the CBK has set limits on what can be recovered from a customer with respect to a non-performing loan.
Analysts have raised concerns about the impact of the new regulations on the industry, but the CBK has emphasized the need for consumer protection. The regulations are aimed at ensuring that NDTCPs operate in a fair and transparent manner, and that customers are protected from unfair practices.
Key points
- The new CBK rules have triggered anxiety among non-deposit-taking credit providers due to unclear guidelines on loan repayment distribution.
- The regulations reverse the traditional sequential payment hierarchy, prioritizing principal over interest and fees.
- The CBK has emphasized consumer protection, setting tough terms on credit terms and handling of personal information.