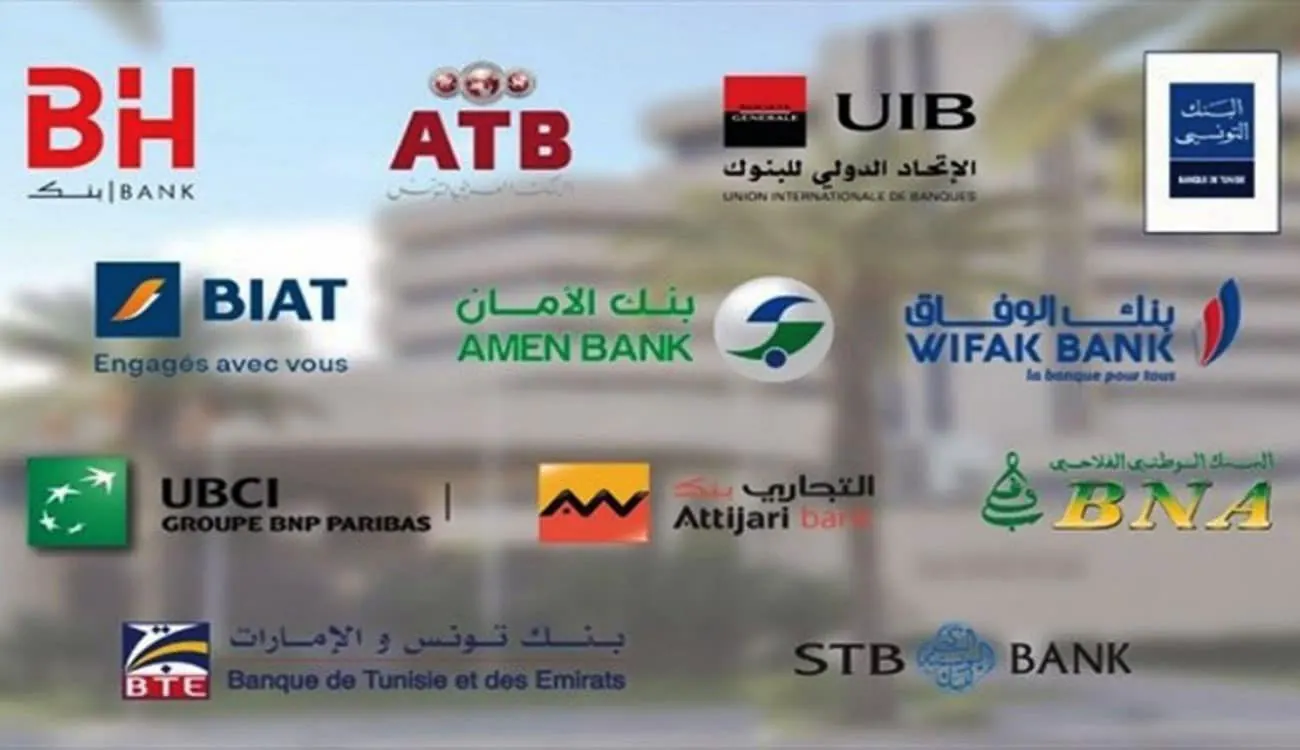
The financial results of Tunisian banks listed on the Tunis Stock Exchange for the first half of 2026 show a significant disparity in profitability. According to a study by Prime Partners Holding, seven banks recorded growth in their net profits, while two others saw a decline, and one switched from profit to loss. The study analyzed the financial statements of ten listed banks as of June 2026.
The product net banking income increased for nine banks, except for the Société Tunisienne de Banque, which saw a 10.5% decline. The Amen Bank recorded the highest growth in net profits, with a 23.7% increase to 161.9 million dinars. The Banque Nationale Agricole and Banque de Tunisie also reported significant growth, with increases of 13.8% and 12.5%, respectively.
Other banks, such as the Banque Internationale Arabe de Tunisie, Attijari Bank, Union Internationale de Banques, and Union Bancaire pour le Commerce et l'Industrie, also reported positive performances. Their net profits increased by 10.3%, 5.9%, 6.6%, and 9.7%, respectively. These results indicate a varied performance across the Tunisian banking sector.
In contrast, some banks faced difficulties. The Housing Bank's net profit plummeted by 72% to 15.2 million dinars, despite an 8.7% increase in its product net banking income. The Société Tunisienne de Banque saw its net profit decline by 59.4% to 9.1 million dinars. The Arab Tunisian Bank switched from a net profit of 2.6 million dinars to a net loss of 27.6 million dinars.
The study attributes the underperformance of some banks to increased provisions for loan risks. The Housing Bank's provisions surged by 83.9% to 146.7 million dinars, while the Arab Tunisian Bank's provisions rose from 32.7 million to 68.6 million dinars. These increased provisions affected the banks' overall profitability.
The analysis also highlights the heterogeneity of financial structures among the banks, particularly in terms of transformation, measured by the credit-to-deposit ratio. This ratio ranged from 57.4% for the Banque Internationale Arabe de Tunisie to 101.4% for the Housing Bank. The rates of classified claims, representing troubled engagements, also varied significantly.
The rates of classified claims differed substantially among the banks, ranging from 21.59% for the Banque Nationale Agricole to 5.1% for the Union Bancaire pour le Commerce et l'Industrie. These indicators suggest that Tunisian banks face varying levels of risk and liquidity.
Key points
- Tunisian banks listed on the Tunis Stock Exchange reported mixed financial results for the first half of 2026.
- Seven banks recorded growth in net profits, while two saw a decline, and one switched from profit to loss.
- The product net banking income increased for nine banks, except for the Société Tunisienne de Banque.