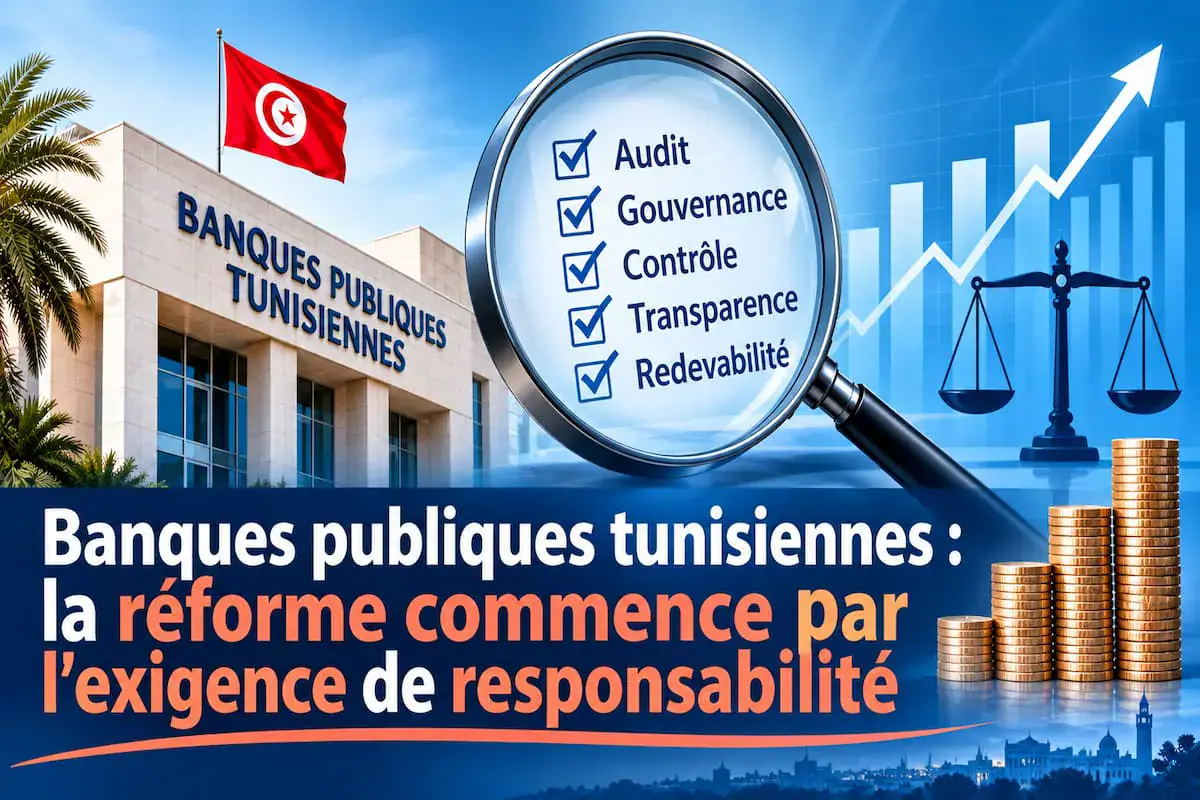
Recent judicial cases involving officials from Tunisian public banks have brought attention to the importance of solid governance and accountability in the country's banking sector. The stability of a bank is not solely dependent on its financial results or financing capabilities, but also on the quality of its decisions, control effectiveness, and governance body accountability. This issue goes beyond specific judicial procedures and encompasses the entire credit decision-making process, which requires rigorous, independent, and transparent evaluation.
The governance of credit is a crucial aspect, serving as the first line of defense against failures. Credit decisions commit not only the institution's resources but also its future ability to support businesses, investments, and economic development. Evaluating credit quality requires a documented assessment of repayment capacity, project economic viability, guarantee quality, engagement concentration, and associated risks. A clear decision-making process is essential, including case instruction, financial analysis, risk assessment, and validation according to power delegations.
Before implementing reforms, a thorough evaluation of existing mechanisms is necessary. This assessment should cover credit portfolio quality, decision conformity with power delegations, grant procedure regularity, engagement coverage by guarantees, and mechanisms for monitoring receivables. Particular attention should be given to high-risk cases, engagement concentrations, and potential conflict-of-interest situations. Identifying anomalies is insufficient; it's also crucial to examine their root causes, such as inadequate procedures or weak information systems.
Tunisia already has a regulatory framework defining key banking obligations regarding governance, internal control, and risk management, established by Law No. 2016-48 on July 11, 2016. However, the focus should shift from regulatory compliance to the actual effectiveness of control. A robust governance system is only effective when procedures are not just reference documents but are enforced at all decision-making levels without exceptions.
The responsibility for governance does not stop at the credit decision stage. It extends to implementing an efficient system for monitoring engagements and managing risks. Digital transformation can enhance the traceability and control of risks. Moreover, the economic cost of governance failures can be substantial, affecting not only the banks but also the overall economy.
Restoring trust in the banking sector requires verifiable results and a genuine commitment to reform. This involves not just addressing past failures but also implementing measures to prevent future ones. A reform that prioritizes responsibility can help public banks consolidate their credibility, preserve their assets, and fully assume their role in financing the national economy.
Ultimately, the goal of banking reform in Tunisia should be to establish a culture of accountability and transparency. This requires a comprehensive approach that includes thorough evaluation of existing mechanisms, effective governance structures, and a commitment to implementing and monitoring reforms. By prioritizing responsibility, Tunisia's banking sector can strengthen its governance and contribute to the country's economic development.
Key points
- Analysts stress that stronger governance and accountability are crucial for the stability and effectiveness of Tunisia's banking sector.