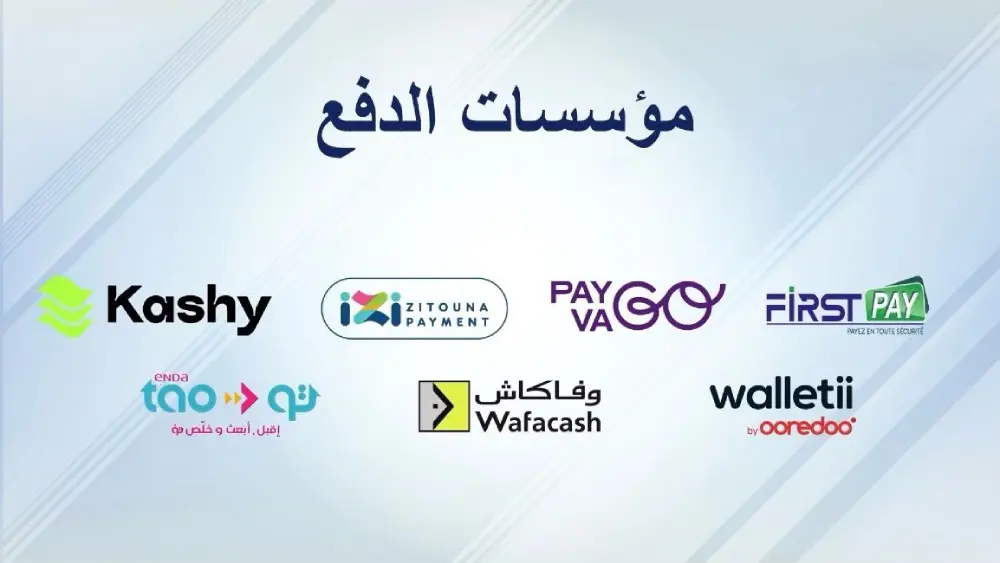
The Central Bank of Tunisia (BCT) has published Circular No. 10, dated September 25, 2026, outlining new rules for payment institutions. This circular replaces the previous one from 2018 and is part of the implementation of the 2016 law on banks and financial institutions. The new regulations aim to enhance transparency, governance, and cybersecurity while expanding and securing the country's mobile and electronic payment ecosystem.
The circular defines the services that payment institutions (IPs) are authorized to offer exclusively in Tunisian dinars. These services include opening payment accounts categorized into three types. Category 1 accounts, reserved for individuals, have a maximum balance of 1,500 dinars. Category 2 accounts have a maximum balance of 5,000 dinars, with a daily cash withdrawal limit of 3,000 dinars. Category 3 accounts have a maximum balance of 20,000 dinars, with a daily cash withdrawal limit of 10,000 dinars.
The new regulations also set limits on transfer and exchange operations. Cash transfers are capped at 3,000 dinars per transaction, while international transfers are limited to 20,000 dinars per transaction. Additionally, the circular introduces the possibility of remote account opening without a physical presence, provided that a highly secure technological model is used. This model must ensure the verification of official documents, proof of life, and strong authentication.
To ensure security and governance, the BCT imposes strict risk management requirements on payment institutions. These institutions must segregate client and merchant funds, depositing them into a unique account with a bank by the next business day. The funds must be kept separate from the institution's own funds. The circular also requires annual cybersecurity audits by accredited firms and immediate notification of cyber incidents to the BCT and the National Cybersecurity Agency.
The regulations also focus on the governance and oversight of payment institutions. These institutions must establish an audit and risk committee within their board of directors or supervisory board. They must also have independent risk management, internal audit, and compliance functions. Furthermore, the circular sets out detailed requirements for the opening, transfer, or closure of physical branches and the qualifications of directors and representatives.
Payment institutions can rely on agent networks and strategic partnerships, subject to prior BCT authorization. The circular provides detailed guidelines on the responsibilities of these agents and partners. The goal is to ensure that payment institutions operate securely and transparently, protecting users' funds and personal data.
The updated regulations are part of Tunisia's efforts to develop its digital payment ecosystem. The country has seen significant growth in mobile payments, with an 81% increase in transactions in 2025. The new rules aim to further enhance the security and efficiency of payment services, promoting financial inclusion and innovation in the sector.
Key points
- The Central Bank of Tunisia has introduced new regulations for payment institutions to enhance transparency, governance, and cybersecurity.
- The regulations set limits on payment accounts and transactions, and introduce remote account opening with strict security requirements.
- The rules aim to develop Tunisia's digital payment ecosystem, promoting financial inclusion and innovation.