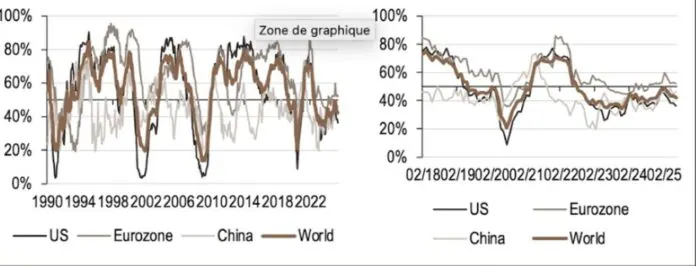
The global economy is navigating a complex landscape, marked by both growth and uncertainty. While major economies continue to produce, invest, and innovate, they are also facing new challenges, including geopolitical tensions, trade disruptions, and rising financing costs. These factors are redefining the rules of the game and leading to a more fragmented global economy. As a result, the traditional model of globalization, which emphasized producing at the lowest cost and selling everywhere, is being reevaluated.
The changing global economy is having a significant impact on Africa, which possesses many of the natural resources needed for future technologies, including semi-conductors, artificial intelligence, and renewable energy. The continent is also home to a large and growing market of over one billion people. However, the key question is whether Africa can move beyond simply exporting raw materials and instead develop its own industries, create jobs, and build regional value chains.
The competition for global influence is no longer limited to major powers, but also involves countries competing for infrastructure development, ports, and commercial corridors. In this new landscape, geography is becoming increasingly important, with countries located along major trade routes and corridors holding significant economic potential. For African economies, this means going beyond simply serving as transit points and instead developing their own industrial and logistical ecosystems.
The port of Djibouti, for example, is strategically located along the Red Sea and Indian Ocean trade routes, making it an important hub for international trade. However, to maximize its economic potential, the country must invest in developing its infrastructure, including transportation networks, logistics facilities, and telecommunications. This will enable Djibouti to move beyond simply serving as a transit point and instead become a major player in regional trade and commerce.
Technological advancements, including artificial intelligence, automation, and digitalization, are also transforming the global economy. While these changes present challenges for developing countries, they also offer opportunities for catch-up and rapid progress. By investing in digital skills, education, and infrastructure, African countries can access global markets more quickly and leapfrog traditional stages of industrial development.
However, realizing the benefits of technological change requires more than just investment in infrastructure and skills. It also requires effective policies and institutions to support innovation and entrepreneurship. Governments must create an enabling environment for businesses to thrive, including by providing access to finance, promoting competition, and protecting intellectual property rights.
As the global economy continues to evolve, Africa's ability to adapt and transform will be critical to its future prosperity. The continent must invest in its infrastructure, human capital, and innovation capacity to take advantage of new opportunities and overcome challenges. By doing so, Africa can move beyond simply participating in globalization and instead play a more significant role in shaping the global economy.
Key points
- Africa must develop its own industries and build regional value chains to maximize the benefits of its natural resources.
- The continent's strategic location along major trade routes and corridors holds significant economic potential.
- Technological change presents both challenges and opportunities for African countries, requiring effective policies and institutions to support innovation and entrepreneurship.