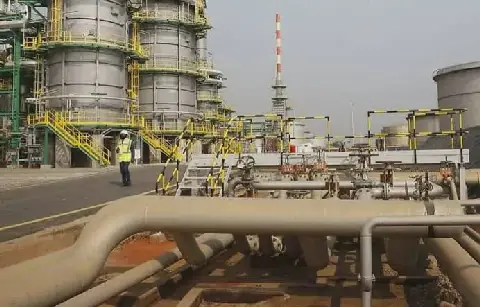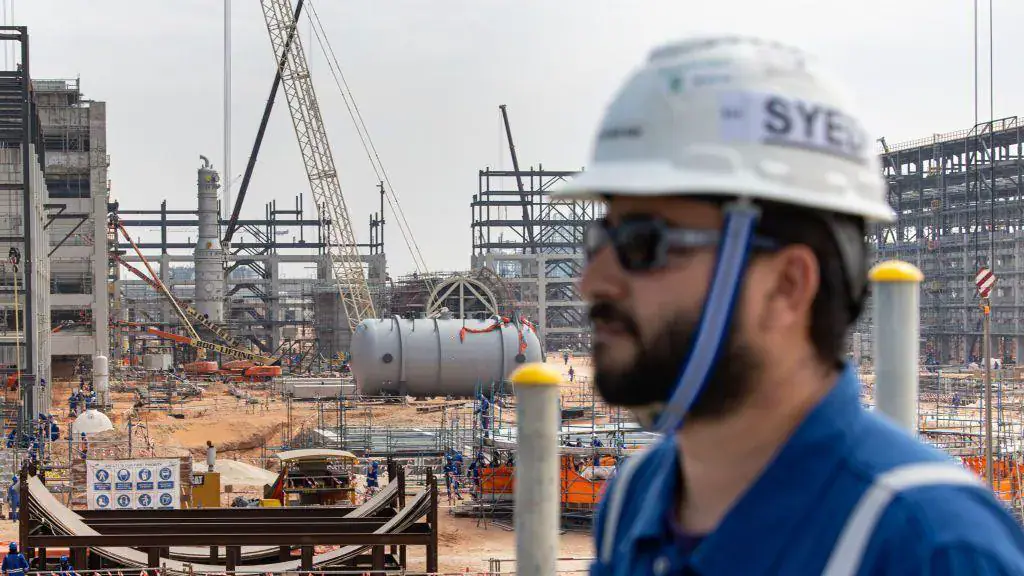
The Gulf petrochemical industry, once a beacon of success, is now facing significant challenges due to ongoing wars and shifting market dynamics. Historically, the industry has been a cornerstone of the regional economy, transforming waste gas into valuable products. In the 1950s and 1960s, oil fields in Saudi Arabia would light up the desert night, a sign of the vast resources being extracted but also a reminder of the gas being wasted. This scenario would change over time as countries in the region began to harness this resource.
The idea of utilizing associated gas, rather than simply burning it, dates back to the 1960s. Abdullah Al-Turiki, Saudi Arabia's first oil minister, was a key proponent of this vision. He envisioned a future where Gulf countries would not only extract their hydrocarbon resources but also control what happened to them afterward. However, several obstacles stood in the way, including a lack of infrastructure and insufficient capital. The 1973 Arab-Israeli War marked a turning point, as oil prices skyrocketed, providing Gulf countries with the financial means to invest in infrastructure.
In Saudi Arabia, the main gas network began collecting associated gas in 1977, and the Saudi Basic Industries Corporation (SABIC) was established in 1976 to convert this resource into industrial products. The Kuwaiti chemical industry also made early strides, starting production of ammonia and urea in 1963. However, it was Saudi Arabia, with its vast oil and gas reserves, that would significantly scale up the industry. The composition of natural gas varied across fields, influencing the types of products that could be manufactured.
Qatar's North Field, for instance, is rich in methane, making it suitable for producing ammonia and urea. Today, Qatar is a major producer and exporter of urea. In contrast, Saudi Arabia's gas is rich in ethane and heavier compounds, ideal for producing ethylene and propylene, essential materials for plastic production. The UAE's Abu Dhabi also leveraged its gas resources to establish Borouge, a leading producer of polyethylene.
The Gulf petrochemical industry has grown substantially, with exports valued at $64.6 billion in 2023. The region's production capacity reached 156.2 million tons, about 6% of the global total. Saudi Arabia leads the region in petrochemical production, accounting for a significant portion of the world's polypropylene supply. Despite this success, the industry still faces challenges, including fluctuating global markets and the need to diversify its product range.
To increase its contribution to GDP, the industry must move up the value chain, producing higher-value chemicals for sectors like electronics, pharmaceuticals, and automotive. Currently, petrochemicals account for about a quarter of the manufacturing sector in Gulf Cooperation Council (GCC) countries but only around 4% of GDP. Analysts believe that developing specialized chemical production will be crucial for future growth.
The industry's reliance on large-scale production and exports makes it vulnerable to global market fluctuations. About 85% of GCC petrochemical production is exported, exposing it to external market volatility. While the industry has made progress, it still has a long way to go in achieving its full potential and playing a more significant role in the regional economy.
Key points
- The Gulf petrochemical industry faces challenges due to ongoing wars and shifting market dynamics.
- The industry must diversify its product range and move up the value chain to increase its contribution to GDP.
- The region's production capacity reached 156.2 million tons in 2023, accounting for about 6% of the global total.