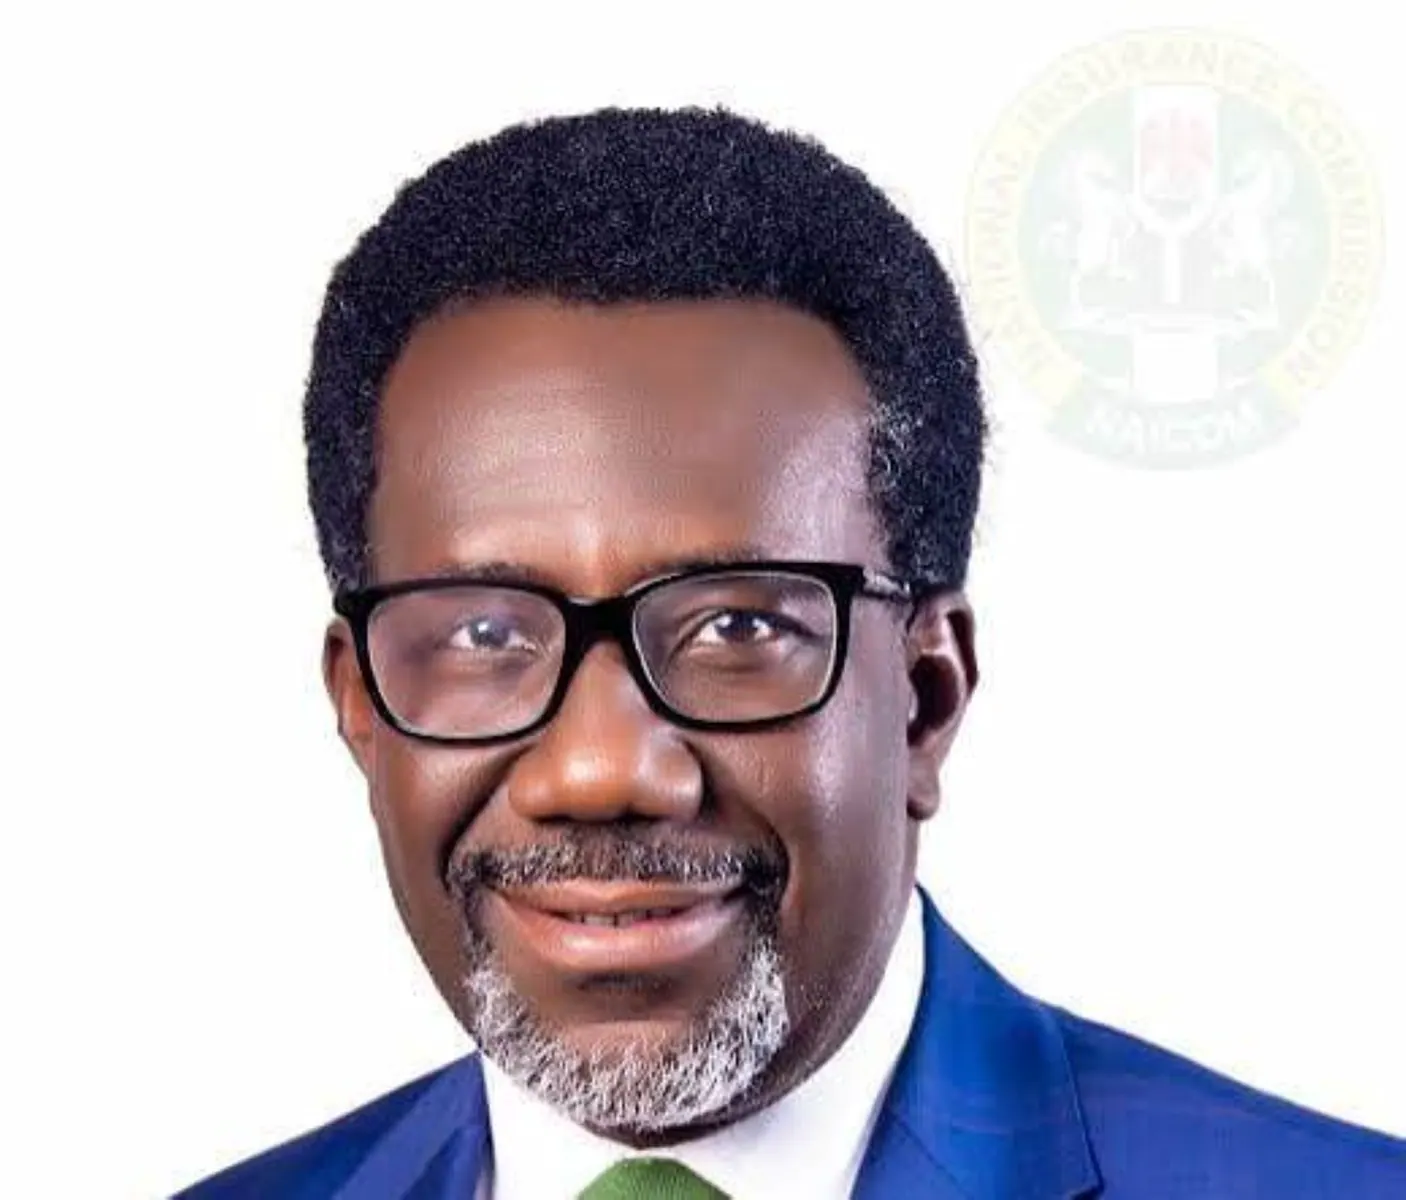
Nigeria's insurance industry has long occupied an uncomfortable position in the national economy, with its importance never in doubt, yet its potential largely untapped due to weak public confidence, low penetration, and concerns over claims settlement. The industry's limited financial capacity has also been a major challenge. However, under Olusegun Ayo Omosehin's leadership as Commissioner for Insurance and CEO of the National Insurance Commission (NAICOM) since 2024, a renewed sense of purpose has been brought to the regulation and repositioning of the sector.
Omosehin's extensive experience in the insurance industry, with over three decades of experience, has equipped him with a practical understanding of the industry's strengths and weaknesses. He has worked across different segments of the industry, occupying senior leadership positions at various insurance companies, including Crusader Insurance, Custodian & Allied, and Admiral Insurance. His experience gives him an appreciation of what must change if insurance is to play a bigger role in Nigeria's economic development.
One of the significant achievements under Omosehin's watch is the successful completion of the industry's recapitalization exercise under the Nigerian Insurance Industry Reform Act (NIIRA) 2025. The exercise aimed to strengthen the financial capacity and resilience of operators, fundamentally changing the conversation around the strength of insurance companies in Nigeria. The process resulted in stronger capital positions across compliant operators, creating a more solid foundation for companies to protect individuals, businesses, and investments against risk.
However, recapitalization is only useful if stronger balance sheets translate into better services. NAICOM has emphasized corporate governance, financial soundness, accountability, and better claims settlement, recognizing that the ultimate measure of an insurance company is not merely how much money it has, but how effectively it meets its obligations to policyholders. The establishment of the Insurance Policyholders' Protection Fund is particularly significant, strengthening the institutional safety net for policyholders and reinforcing the principle that the customer must remain at the center of insurance regulation.
Another important aspect of Omosehin's stewardship is the movement towards risk-based regulation. NAICOM's work on a Risk-Based Capital framework aims to ensure that capital requirements correspond more closely with the risks individual insurance companies undertake. This approach encourages stronger risk management, discourages reckless practices, and creates a regulatory environment in which responsible operators can grow while policyholders' interests remain protected.
The reforms are also extending beyond the traditional boundaries of the industry, with NAICOM increasingly focusing on innovation, technology, financial inclusion, and the expansion of insurance penetration. The collaboration with the National Space Research and Development Agency on the use of geospatial data and catastrophic risk insurance is an example of how the sector can respond to emerging challenges. This broader outlook is crucial for Nigeria to maximize the economic value of insurance.
Ultimately, the success of these reforms will be measured by the tangible benefits they bring to policyholders, businesses, and the Nigerian economy. Nigerians will want to see faster and fairer claims settlement, better products, improved customer service, greater transparency, and insurance that is accessible to ordinary households and small businesses. The industry must earn public confidence by demonstrating that when a policyholder suffers a legitimate loss, the promise made by the insurer will be honored.
Key points
- The recapitalization exercise has resulted in stronger capital positions across compliant operators.
- NAICOM is emphasizing corporate governance, financial soundness, accountability, and better claims settlement.
- The industry is moving towards risk-based regulation to ensure capital requirements correspond with individual risks.