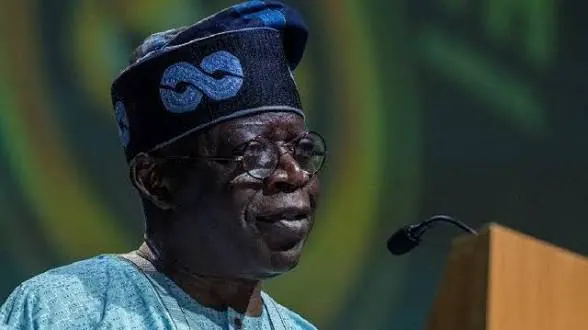
As Nigeria celebrates 66 years of independence, the country's economic landscape has undergone significant changes under President Bola Ahmed Tinubu's administration. Since assuming office in 2023, Tinubu has implemented reforms aimed at addressing the country's economic challenges, including expensive petrol subsidies, multiple exchange rates, and foreign-exchange shortages. These reforms have had far-reaching consequences, with some immediate effects being severe. However, evidence of macroeconomic stabilisation has become more visible, with Nigeria's real GDP expanding by 4.43 per cent year-on-year in the second quarter of 2026.
Tinubu's administration responded to the economic challenges by removing petrol subsidies, liberalising exchange rates, and implementing tighter monetary policies. The removal of petrol subsidies, in particular, has been a significant decision, transferring the cost of petrol from the government to consumers and triggering an unprecedented rise in fuel prices. However, the government argues that subsidy reform has released resources for infrastructure and other public priorities, with N6.47 trillion spent on strategic infrastructure between June 2023 and December 2025.
The reforms have produced measurable gains in government revenues, reserves, foreign-exchange stability, trade, and investor confidence, according to Lagos economist and Chief Executive Officer of the Centre for the Promotion of Private Enterprise, Muda Yusuf. However, Yusuf emphasises that stability must now become productivity, and macroeconomic stability is a means to an end, ultimately producing stronger businesses, employment, incomes, and living standards.
The dismantling of the multiple-exchange-rate system has also been a major reset, with the initial consequences including a sharp depreciation of the naira and higher import costs. However, the International Monetary Fund (IMF) says exchange-rate reforms have helped improve market functioning and rebuild external buffers. The administration's reform programme has coincided with a substantial improvement in the country's external position, while inflation has also moderated from its 2024 peak.
The Nigerian Exchange has been a clear indicator of changing investor sentiment, with market capitalisation rising from about N30 trillion in 2023 to N160 trillion in August 2026. The Finance Minister and Coordinating Minister of the Economy, Taiwo Oyedele, attributed the market's expansion to economic reforms, describing the capital market as an increasingly important avenue for wealth creation.
The economic reset has also been accompanied by an infrastructure push, with over 2,700 kilometres of highways and major roads under construction, reconstruction, or rehabilitation. The Lagos-Calabar Coastal Highway has emerged as the flagship project, with its first 30-kilometre completed segment commissioned in 2025. The Federal Government has also approved over N7 trillion in additional major road and bridge contracts in 2026.
The administration's reform agenda is also visible in transportation and energy, with Tinubu commissioning four CNG infrastructure projects in Lagos, Abuja, and Owerri in May 2026. These projects aim to expand domestic gas utilisation and provide an alternative to petrol-dependent transportation. As Nigeria continues to navigate its economic challenges, the impact of Tinubu's reforms will be closely watched.
Key points
- The Nigerian economy has shown signs of stabilisation and growth under President Bola Ahmed Tinubu's reforms.
- The reforms have produced measurable gains in government revenues, reserves, and investor confidence.
- The administration's infrastructure push has led to significant investments in roads, highways, and energy projects.