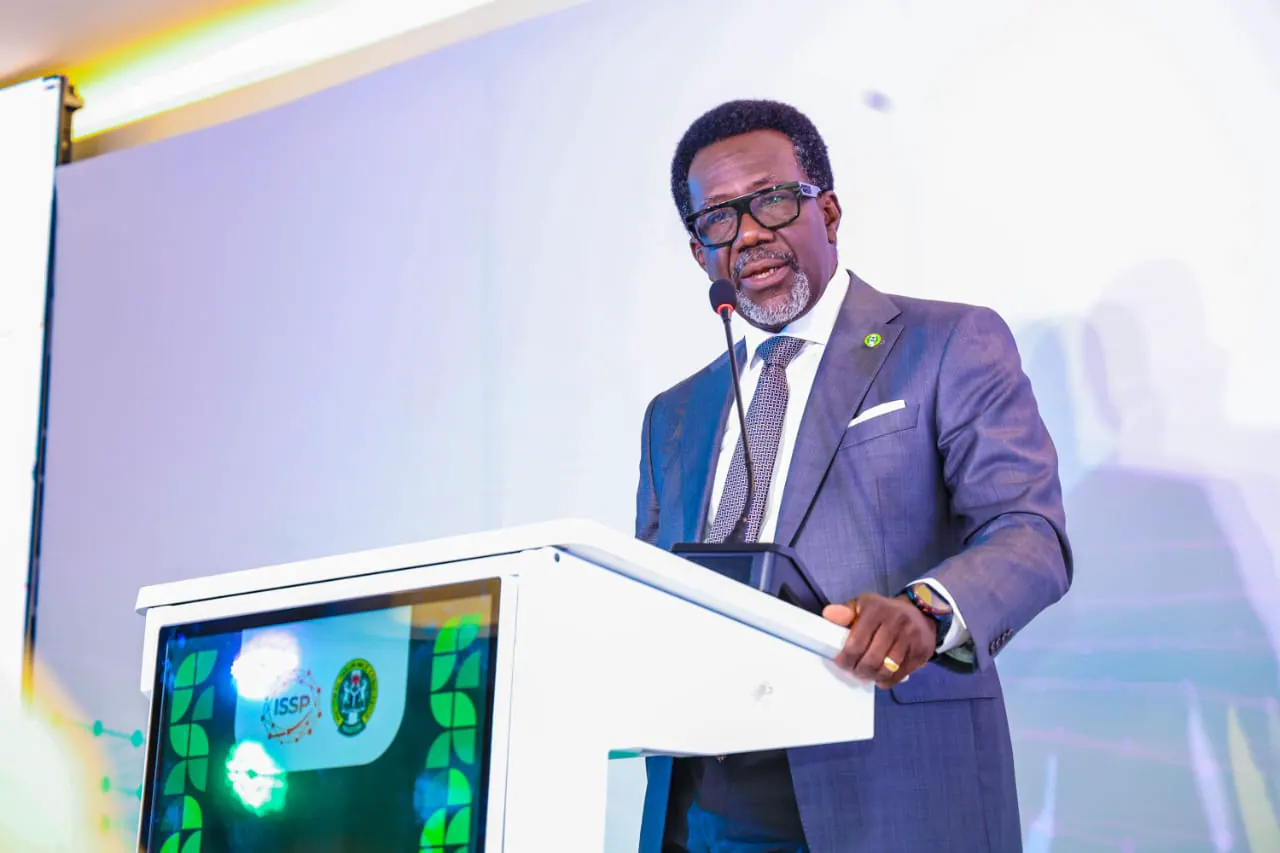
The National Insurance Commission (NAICOM) has clarified that Nigeria's insurance recapitalisation exercise was designed to give insurers a pathway to raise fresh capital, merge where necessary, and emerge as financially stronger institutions. The exercise, which came to an end recently, saw some insurers fail to meet the minimum capital requirements within the prescribed period, while others challenged the regulator's decisions in court. NAICOM's commissioner for Insurance/CEO, Olusegun Omosehin, maintained that the regulator's position was clear from the beginning: recapitalisation was never intended to eliminate operators from the market.
According to Omosehin, the commission initially made it clear that no operator would be allowed to go down, but that the regulator could not compel companies to take the opportunities available to them. The regulatory strategy was not necessarily for every insurance company to remain independent. NAICOM expected weaker or undercapitalised operators to explore combinations with stronger partners, allowing them to preserve a stake in a viable business rather than lose their licences altogether. This approach, Omosehin said, was to ensure that insurers could protect policyholders.
The recapitalisation exercise provided insurers with three key options: raise the required capital independently, find strategic investors, or merge with another operator. Omosehin noted that having a 5 percent stake in a thriving business is better than owning 100 percent of a cancelled licence. Once a licence is cancelled, the business no longer exists. NAICOM established a four-stage verification process to ensure that insurers' claims of raised capital were independently verified. The process involved self-assessment, NAICOM's review, independent verification by the Big Four accounting firms, and a review by NAICOM's governing board.
The verification process became particularly important where companies claimed to have raised the required capital but had not completed the verification process. Operators were required to move the funds into escrow accounts with the Central Bank of Nigeria (CBN). The money remained the property of the insurer, and the arrangement provided a mechanism for verifying the funds, including their source and compliance with anti-money laundering and counter-terrorist financing requirements. This distinction between claiming to have raised capital and proving that the capital qualified was central to the regulator's assessment.
Omosehin cited the case of Universal Insurance, which failed to meet the minimum capital requirement and provide evidence that the capital-raising process was still sufficiently advanced to qualify for further consideration by the deadline. NAICOM subsequently cancelled its registration and appointed a liquidator. The insurer later requested additional time to raise capital and execute a memorandum of understanding, but NAICOM maintained that the request came after the deadline had passed. The regulator's position was that the problem was not simply a failure to have completed every administrative step by the deadline.
NAICOM did not automatically shut out companies whose capital had been raised but was still undergoing verification. Such operators were allowed additional time to complete the verification process, provided they had raised the funds and moved them into escrow. The regulator's position was that the critical question was whether the operator had actually raised the required capital within the period allowed and could demonstrate that it was available for verification. Operators had a substantial window to do so, with a 12-month period allowed for the recapitalisation exercise.
The outcome of the recapitalisation exercise has raised questions about whether the affected companies were given sufficient opportunity to comply and what went wrong in their attempts to meet the new capital thresholds. NAICOM's Omosehin has maintained that the regulator provided a clear pathway for insurers to raise fresh capital and emerge as financially stronger institutions. The exercise has resulted in a stronger insurance industry, with insurers that can protect policyholders and provide financial services to the economy.
Key points
- NAICOM's insurance recapitalisation exercise aimed to strengthen insurers, not shrink the industry.
- Insurers had three key options: raise capital independently, find strategic investors, or merge with another operator.
- The regulator provided a 12-month window for the recapitalisation exercise, allowing operators sufficient time to raise capital and complete verification.