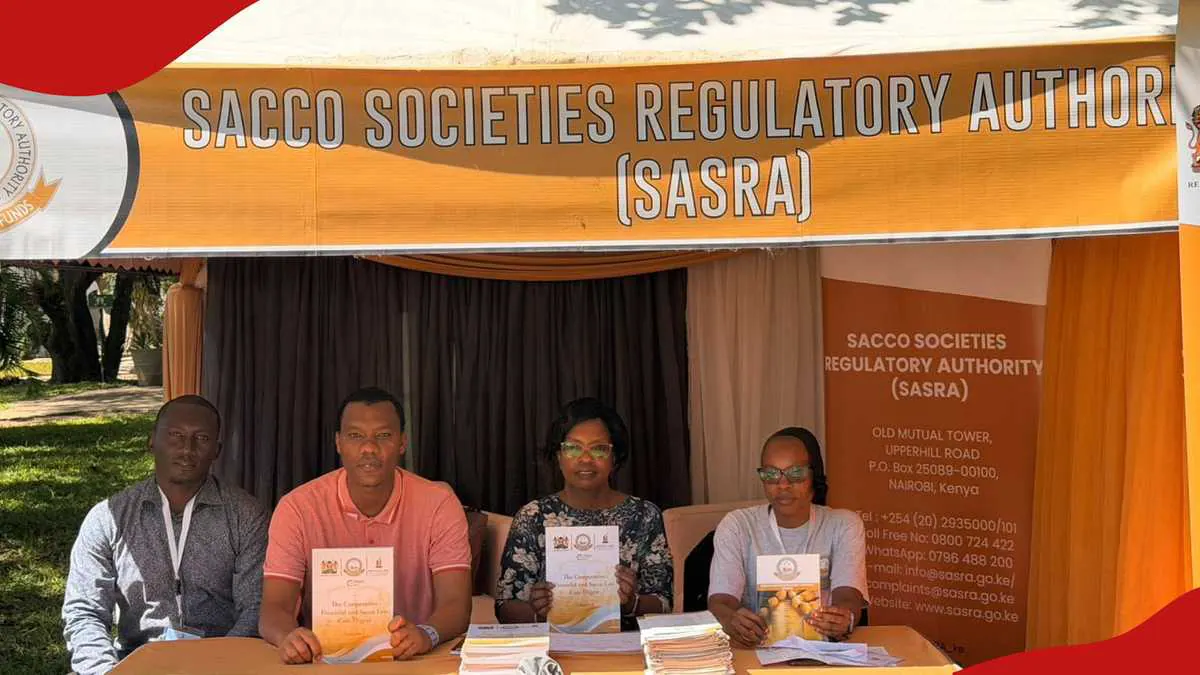
Kenya's Savings and Credit Cooperative (SACCO) sector is growing, with 357 regulated SACCOs holding KSh 1.21 trillion in assets and serving 7.87 million members, according to the SACCO Societies Regulatory Authority's (SASRA) 2025 annual report. However, the data reveals significant differences in financial health across individual societies. SASRA supervises 179 deposit-taking (DT-SACCOs) and 178 non-withdrawable deposit-taking (NWDT-SACCOs). Prospective members should confirm their intended SACCO appears on the regulator's current list and request a valid licence or authorisation certificate.
Unremitted salary deductions rose to KSh 3.92 billion in 2025, affecting over 104,000 members across 89 SACCOs. This has significant implications for SACCO liquidity and lending. SASRA received 886 member complaints in 2025, with the most common issue involving delays in refunds of savings and share transfers. The regulator has pledged policy reforms to prevent employers from failing to remit deductions. Members should ask directly whether their employer remits on time to avoid disputes over loans and reduced borrowing capacity.
Prospective members should examine key factors before joining a SACCO, including whether it is regulated and what kind of SACCO it is. They should also check the SACCO's non-performing loan (NPL) ratio, which improved to 6.36% in 2025 for DT-SACCOs. However, agriculture-based SACCOs recorded an NPL ratio as high as 14.01%, linked to erratic weather patterns. Understanding the SACCO's financial health can help members make informed decisions.
A SACCO's capital cushion is crucial in absorbing losses before members' savings are affected. For DT-SACCOs, core capital rose to 19.53% of total assets in 2025. Prospective members should look for "institutional capital," the reserves built from retained earnings, which is more stable than share capital. Checking the SACCO's payout history is also essential, with the average SACCO paying 10.00% dividends on shares and 6.72% interest on deposits in 2025.
The SACCO industry is highly concentrated, with 61 large SACCOs holding 77.62% of total assets. Being small is not a warning sign, but medium and small SACCOs need support to grow in a balanced way. Prospective members should find out which tier their SACCO falls into: large (over KSh 5 billion), mid (KSh 1 to 5 billion), or small (under KSh 1 billion). A smaller SACCO may have less scale to weather shocks but may also serve members more closely.
Complaints about refunds of savings, deposits, or share transfers were the most common issue, with 425 complaints received by SASRA in 2025. Members should ask about the SACCO's refund process and check whether it has a record of delayed payouts. Complaints about guarantors more than quadrupled, from 13 to 59, highlighting the importance of understanding loan terms and liabilities.
The full SACCO Supervision Annual Report 2025 is available for download on the SASRA website. SASRA's findings emphasize the need for prospective members to exercise due diligence when selecting a SACCO. By scrutinizing these key factors, Kenyans can make informed decisions and avoid potential risks associated with SACCO membership.
Key points
- Prospective members should check whether their employer remits deductions on time to avoid disputes over loans and reduced borrowing capacity.
- A SACCO's capital cushion and payout history are crucial factors to consider before joining.
- Understanding a SACCO's non-performing loan ratio and financial health can help members make informed decisions.