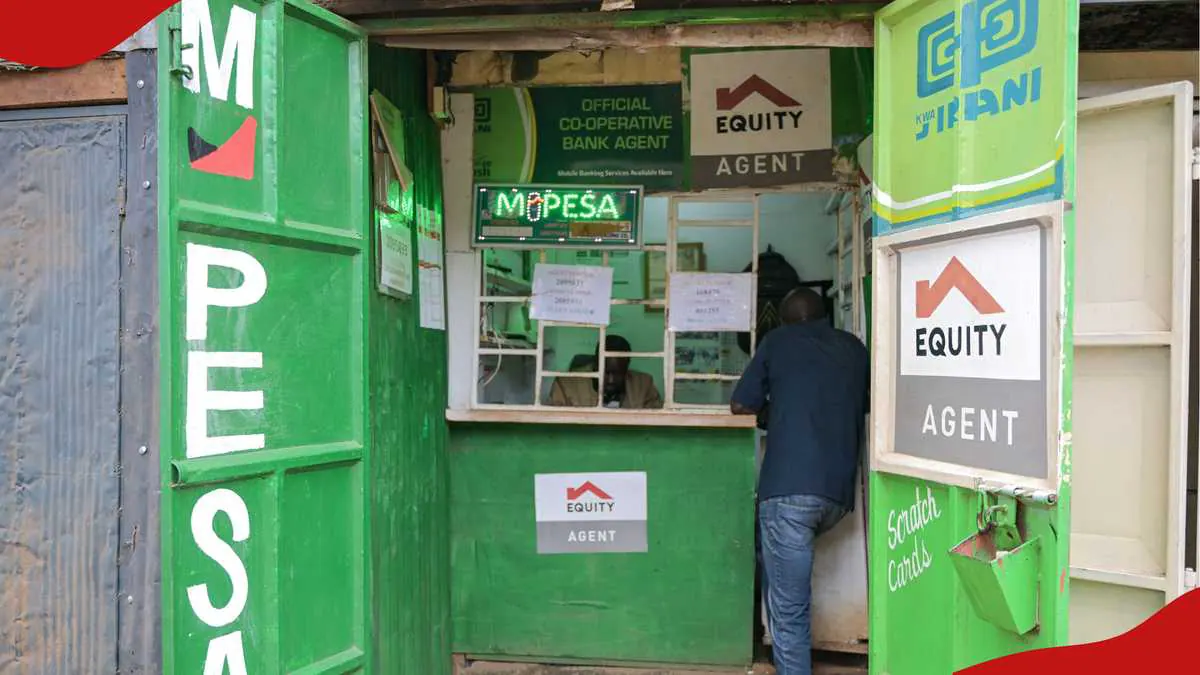
The Central Bank of Kenya (CBK) has published the National Payment System Bill 2026, proposing significant changes to the country's payments sector. The Bill aims to repeal the existing National Payment System Act and establish a unified licensing framework for entities involved in electronic money transactions. This move is expected to overhaul the licensing rules for mobile money operators, banks, and fintech firms. The proposed legislation will cover various payment service providers, including M-Pesa, card processors, and payment gateways.
The new rules set minimum capital requirements for payment service providers, ranging from KSh 5 million to KSh 250 million, depending on the category. Electronic money issuers, such as M-Pesa, must hold at least KSh 250 million, while merchant acquirers and electronic wallet providers require KSh 50 million. Money remittance providers must hold KSh 30 million, and payment gateways require KSh 10 million. Providers operating across multiple licence categories must hold the full capital amount for their highest category, plus 50% of the requirement for each additional category.
The Bill introduces a formal fit-and-proper test for board members, senior managers, and shareholders holding 10% or more of a licensed payment company. Shareholders who fail vetting will immediately lose voting rights and be required to reduce their stake to below the 10% threshold within a period determined by the CBK. This move aims to ensure that payment service providers are managed by individuals with the necessary skills and integrity.
The CBK will gain emergency powers to seize control of failing payment companies and appoint statutory managers for up to 12 months under the proposed law. Where the CBK determines that a payment provider poses a risk to customers or financial stability, it can suspend or revoke the company's licence, take direct control of its assets for up to 90 days, or appoint a statutory manager. This move aims to protect customer funds and maintain financial stability.
To protect customer funds, electronic money issuers and wallet providers will be required to hold all client deposits in ring-fenced trust accounts at licensed banks, separate from their own operating funds. No single bank may hold more than KSh 500 million or 25% of a provider's total trust funds, whichever is higher. This move aims to safeguard customer funds and prevent their misuse.
The Bill also empowers the CBK to compel providers to interconnect with competitors' systems and to mandate open finance data-sharing mechanisms requiring customer consent. Non-compliance could attract administrative penalties of up to KSh 20 million, rising to KSh 30 million for repeat violations, plus daily fines of up to KSh 100,000. Individuals who unlawfully exploit a payment system for financial gain could face up to seven years in prison.
Existing providers will have 12 months from the law's commencement to comply with the new regulations. The Bill must still undergo committee review and public participation before it can be enacted. Once implemented, the new rules are expected to significantly impact Kenya's payments sector, ensuring a more secure and stable financial environment for customers and providers alike.
Key points
- The Central Bank of Kenya introduces new capital requirements for payment service providers.
- The CBK gains emergency powers to seize control of failing payment companies.
- Providers must hold client deposits in ring-fenced trust accounts at licensed banks.