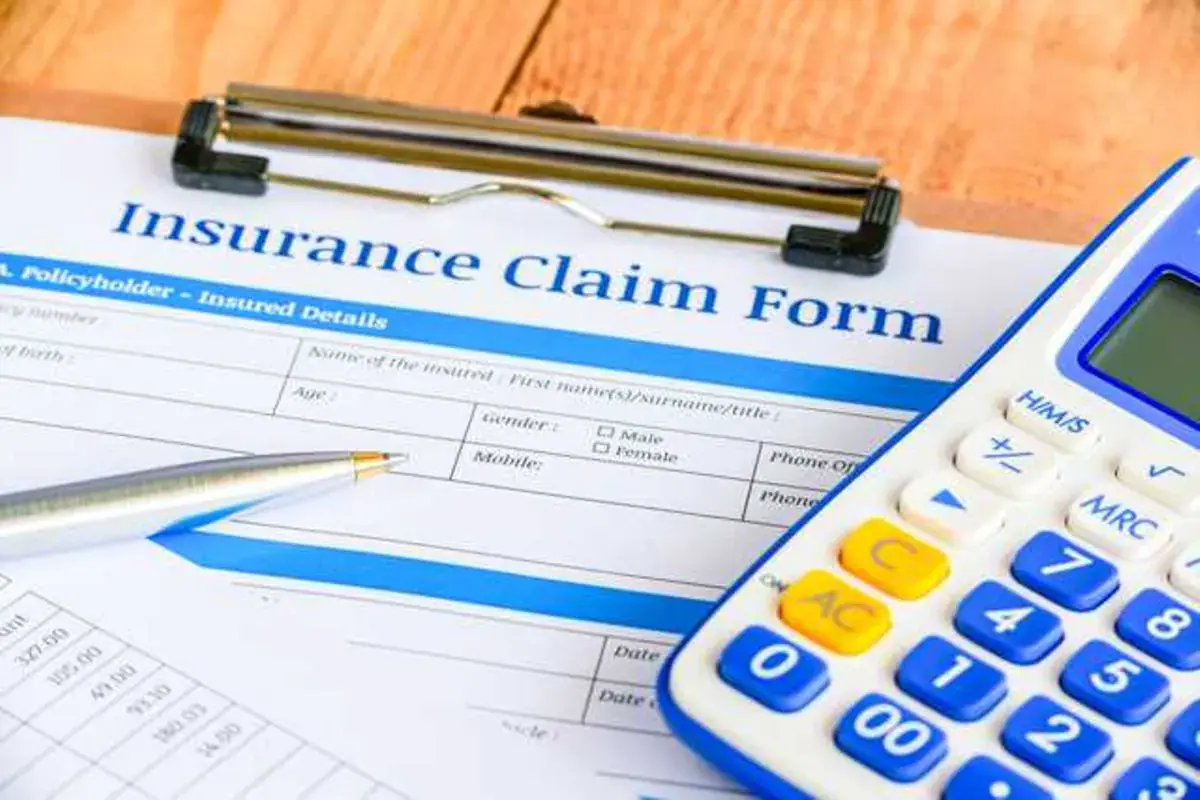
In Kenya's insurance market, incomplete documentation is a significant challenge to claims settlement. According to the Insurance Regulatory Authority (IRA), nearly two-thirds of outstanding liability claims are awaiting submission of required documents. This issue is critical as Kenya's insurance market continues to expand, with gross direct premiums growing 16.5 percent to Sh466.58 billion in 2025.
The IRA's April 202 6 claims snapshot reported that the average settlement period for admitted liability claims is 29.6 months, compared to approximately 4.5 months for non-liability claims. This disparity highlights the need for businesses to understand how insurance protection works in practice. Purchasing insurance and securing adequate protection are not necessarily the same thing, and significant exposures may still be unaddressed despite having a policy in place.
Effective risk management begins with understanding how a business operates and identifying potential threats to its financial and operational stability. This involves assessing physical assets, revenue streams, supply chains, contractual obligations, employees, and dependencies on critical infrastructure. A competent broker provides independent advice that reflects the client's business model, sector, and changing risk profile, helping to identify potential coverage gaps.
Regular risk reviews are crucial as business assets, inventory levels, and operating conditions change over time. If an organisation expands its premises or increases its stock without reviewing its insurance arrangements, it may find itself underinsured, resulting in a proportionate reduction in compensation payable. This can undermine the business's ability to recover from a loss.
The Central Bank of Kenya's November 2025 Insurance Sub-Sector Report found that 74.4 percent of policyholders who experienced an insurance service problem reported declined, delayed, or underpaid claims. Among these cases, 44.1 percent cited premiums not being up to date as a reason. This highlights the importance of understanding policy obligations and maintaining effective communication.
For businesses, ensuring policy conditions are observed and documentation required to support a claim is readily accessible is essential. The insurance broker plays a central role in connecting the policyholder with the insurer and loss adjuster, ensuring that legitimate claims are properly lodged and the client's interests are represented throughout the process.
Ultimately, businesses that prepare for the claims process are better positioned to protect their financial interests and recover from disruption. By understanding their insurance arrangements and maintaining effective communication, businesses can navigate the claims process more effectively and minimise potential losses.
Key points
- Incomplete documentation is a major obstacle to claims settlement in Kenya's insurance market.
- The average settlement period for admitted liability claims is 29.6 months.
- Regular risk reviews are crucial to ensure businesses are adequately insured.
Reporting sources
- Claims preparedness: The gaps that leave businesses exposed · Business Daily Africa