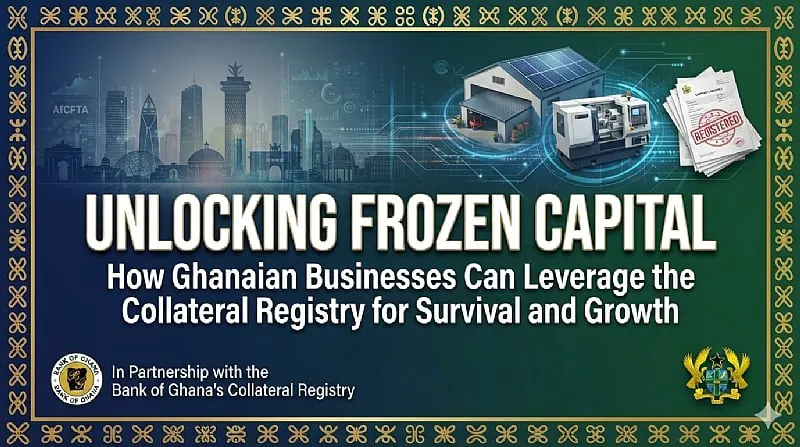
In Ghana, accessing credit remains a significant challenge for businesses due to the traditional banking sector's reliance on land titles and brick-and-mortar buildings as collateral. However, the Bank of Ghana (BoG) has introduced a structural revolution through the rigorous enforcement of the Borrowers and Lenders Act, 2020 (Act 1052). This act empowers businesses to formalize their movable properties through the Ghana Collateral Registry (GCR), providing a legal bridge to more accessible credit. The BoG's Monetary Policy Committee has maintained a benchmark monetary policy rate of 14.0%, signaling a cautious approach toward economic growth.
The current macroeconomic climate in Ghana presents a favorable window for businesses to secure new credit lines. Average commercial bank lending rates have dropped to 15.9%, down from 24.2% a year prior, driven by improved macroeconomic stability. Headline inflation stands at 5.0%, primarily driven by non-food, transport, and global energy costs. As a result, commercial banks are rationing credit to businesses that can show clear, de-risked collateral trails on the GCR. Businesses must understand the current pricing of capital in Ghana to borrow effectively.
The Ghana Collateral Registry allows businesses to transform everyday operational assets into powerful instruments for capital acquisition. A solar aviation runway systems contractor in Accra, for instance, can use its specialized installation equipment and incoming solar inventory as primary financial instruments. By logging these assets into the GCR database, the contractor can bypass retail bank debt and access long-term, concessionary capital via the Development Bank Ghana (DBG) or green energy facility funds. This approach enables businesses to leverage their movable assets to secure credit.
Another example is a plastic recycling and manufacturing plant in the Tema Industrial Area, which needs to acquire automated extrusion lines to scale up production. The factory can engage in an Equipment Finance Lease, where the commercial bank purchases the machinery directly from the global vendor and leases it to the manufacturer. The machinery itself is logged in the GCR database as the primary security. By presenting an independent asset valuation, the manufacturer can access long-term, concessionary capital funded through the DBG.
For smaller businesses, such as an Accra-based Fast-Moving Consumer Goods (FMCG) distributor, invoice discounting can provide instant cash. By turning unpaid corporate invoices into instant cash, the distributor can restock without waiting for buyers to pay. The outstanding accounts receivable are registered on the GCR as security, allowing lenders to advance up to 80% of the invoice value within days. Before applying, the distributor should pull its corporate credit report to clean up past structural mismatches and ensure an unblemished borrowing score.
To position their businesses for formal capital under the BoG's enhanced guidelines, corporate executives should implement several measures. These include auditing and digitizing movable assets, proactively checking the registry, negotiating on legal merits, and leveraging state-backed frameworks. By transitioning to auditable, cloud-based inventory and asset management systems, businesses can provide banks with verifiable data. Additionally, executives should ensure all company vehicles, machinery, and imported technical equipment have clean customs documentation and are free of existing liens.
The Bank of Ghana's mandate is clear: the era of allowing a lack of real estate to stifle corporate ambition is over. With inflation steadying at 5.0% and average lending rates dropping to 15.9%, a unique macroeconomic window has opened for the Ghanaian business community. By leveraging the collateral registry and movable assets, businesses can access credit and drive growth. Key recommendations for corporate leaders include auditing movable assets, checking the registry, negotiating on legal merits, and leveraging state-backed frameworks.
Key points
- The Bank of Ghana's collateral registry enables businesses to use movable assets as collateral for credit access.
- Average commercial bank lending rates in Ghana have dropped to 15.9%.
- Headline inflation in Ghana stands at 5.0%, driven by non-food, transport, and global energy costs.