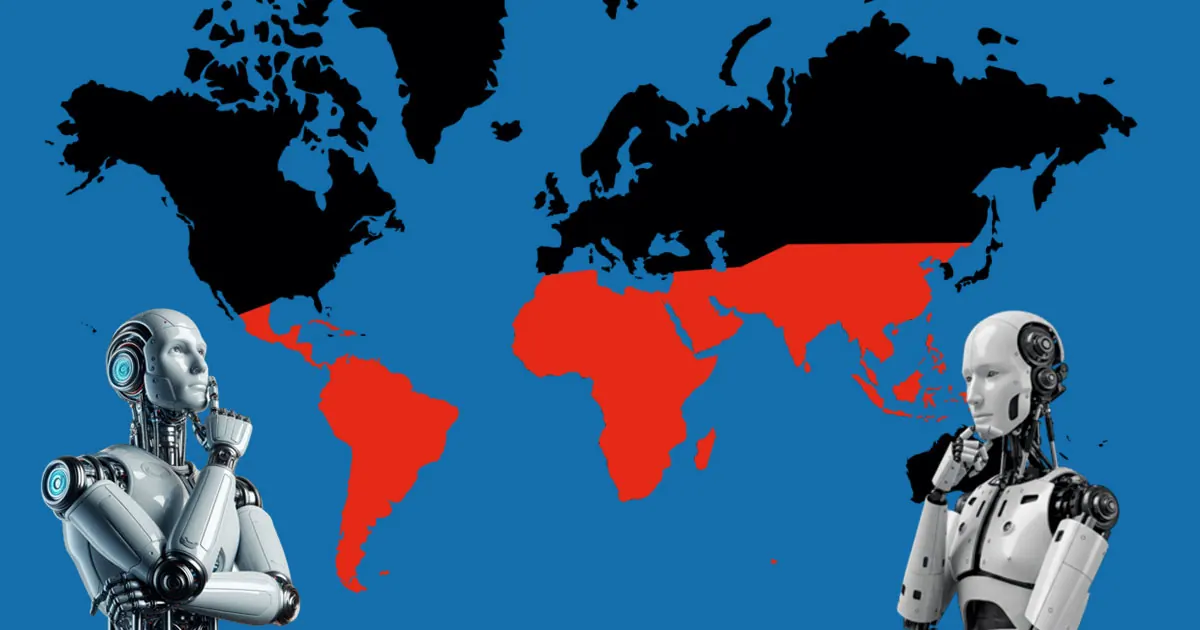
The global economy is witnessing a significant shift in the financing landscape, particularly for Southern economies, as the era of artificial intelligence (AI) gains momentum. The nine largest hyperscalers, which are the core of the digital giants that own and build the planet's data centers, are expected to invest nearly $830 billion in 2026, representing an 80% increase from the previous year. This massive investment is primarily financed through debt, as the founders are reluctant to share power through equity issuance.
The impact of this unprecedented investment is being felt in the global financial markets. The yield on the 5-year US Treasury bond has exceeded 5%, a level not seen in twenty years, driven in part by the demand for capital generated by the AI race. This has significant implications for emerging economies, as the cost of debt increases. The eurobonds issued by emerging countries between 2017 and 2021, with yields of 5-6%, are maturing and will need to be refinanced at much higher rates of 9-11%.
The African continent is facing a significant financing gap, with an estimated $100 billion in unmet financing needs this year. Countries in the South that need to refinance their debt between 2026 and 2028 will face a challenging market, as the capital has already been allocated to other priorities. The traditional pillars of development financing are crumbling, with the external debt becoming a significant burden. According to a report by the United Nations Conference on Trade and Development (UNCTAD), developing countries paid $995 billion in net interest on their public debt in 2025, nearly triple the amount in 2010.
The second pillar of development financing, official development assistance (ODA), is also declining. The OECD reported that ODA fell by 23.3% in real terms in 2025, following an 8.5% decline in 2024. This represents a significant contraction in the history of development aid. The OECD projects a further decline of 6.9% in 2026, with bilateral aid to sub-Saharan Africa and the least developed countries expected to decline by 11.6% and 10.9%, respectively.
The third pillar of development financing, climate finance, has also failed to materialize. The United Nations Environment Programme estimates that the adaptation needs of developing countries will range from $310 billion to $365 billion per year by 2035. However, the public international flows for adaptation, according to the OECD, were less than $35 billion in 2024. This has significant implications for countries that are vulnerable to climate change and need to invest in resilience-building measures.
The current monetary policy stance, led by the US Federal Reserve, is also having a disproportionate impact on Southern economies. The Fed's efforts to combat inflation are being driven by a small group of large corporations, rather than the broader economy. This is leading to a misallocation of resources, as the cost of capital increases for emerging economies, while the large corporations driving the AI investment are less sensitive to price.
The financing landscape for Southern economies is facing a perfect storm, as the traditional pillars of development financing crumble and the global economy adjusts to the era of AI. The dilemma facing policymakers is whether to prioritize solvency or liquidity, as the current crisis has elements of both. The ability of Southern economies to navigate this challenging environment will depend on their ability to adapt to the new reality and find innovative solutions to address their financing needs.
Key points
- The global economy is witnessing a significant shift in the financing landscape, driven by the era of artificial intelligence.
- Southern economies are facing a significant financing gap, with an estimated $100 billion in unmet financing needs this year.
- The traditional pillars of development financing, including external debt, official development assistance, and climate finance, are crumbling.