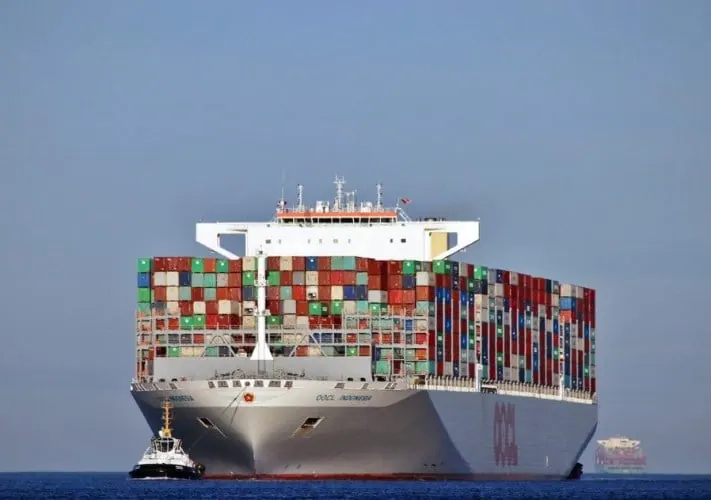
The global shipping market is experiencing a significant divergence in container shipping rates, with the East-West trade routes moving in opposite directions. According to Clarksons Research, the spot rates for shipping containers from Shanghai to Northern Europe have decreased by 5% to $2,425 per twenty-foot equivalent unit (TEU). In contrast, rates on the Trans-Pacific route continue to rise, driven by strong and stable demand.
The price gap between the two routes has reached a record high, with data from Xeneta showing that the spot rate from Asia to the US East Coast was $11,259 per forty-foot equivalent unit (FEU) on September 17. This compares to $4,103 per FEU from Asia to Northern Europe, a difference of over $7,100 per container. The US East Coast route is now close to pandemic highs, with current rates only 11.2% lower than the record $12,683 per FEU set in January 2022.
The divergence in rates is attributed to structural factors, including the return of more shipping services to the Asia-Europe route via the Red Sea. This has increased capacity and reduced the ton-mile index, which had previously surged due to rerouting via the Cape of Good Hope. In contrast, the Trans-Pacific route is supported by strong and stable demand, as well as discipline among shipping lines.
According to Xeneta, the capacity offered from Asia to the US East Coast in September is 6-7% higher than in August, yet rates continue to rise. Peter Sand, chief analyst at Xeneta, stated that shipping lines are "seizing the opportunity in a recovering market" and expects another wave of rate increases in early October, coinciding with the Chinese Golden Week.
The world's largest container trading region, intra-Asia, continues to see record revenues. The Drewry index for intra-Asian container shipping rose 6% last week to $1,402 per FEU, setting a new record for the fourth consecutive time. The consultancy attributed the increase to geopolitical disruptions, typhoons, and capacity constraints, as well as increased demand ahead of the Golden Week.
The record price gap between Trans-Pacific and Europe routes is expected to continue, driven by differences in demand and capacity. The strong demand on the Trans-Pacific route, particularly to the US East Coast, is likely to maintain upward pressure on rates. In contrast, the Asia-Europe route is expected to see more moderate rate increases, driven by increased capacity and competition.
The global shipping market is likely to see continued volatility in the coming months, driven by factors such as the pandemic, geopolitics, and changes in global trade patterns. As the market continues to evolve, shipping lines and analysts will be closely watching for signs of changes in demand and capacity, and adjusting their strategies accordingly.
Key points
- The price gap between Trans-Pacific and Europe routes has reached a record high.
- US East Coast route rates are nearing pandemic highs.
- Intra-Asia container shipping revenues have reached record levels.