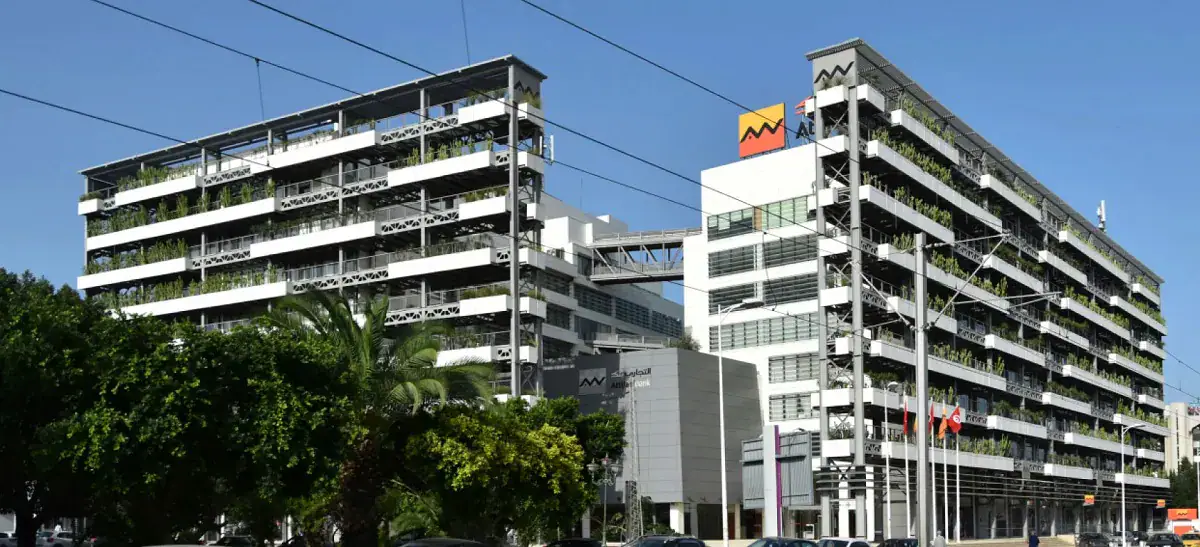
Attijari Bank's financial statements for the first half of 2026 reveal a significant decrease in lending. For every 100 dinars deposited, the bank lent only 58 dinars, compared to 66 dinars in the same period last year. This represents a decline of 6.0% in credits and a 7.1% increase in deposits. The bank's total assets stood at 14,014.2 million Tunisian dinars (MDT), a 7.9% increase from the same period last year.
The bank's credit-to-deposit ratio decreased from 65.5% to 57.5% over the past year. This ratio is a calculation derived from the net balance sheet and does not reflect the regulatory ratio reported to the Central Bank of Tunisia (BCT). The bank's lending focus has shifted, with long-term credits increasing by 4.1%, while short-term credits declined by 23.5% and foreign currency financing decreased by 15.1%.
The excess funds were invested in Treasury bills, which more than doubled to 2,424.3 MDT. The bank's exposure to the Treasury increased to 2,967.6 MDT, representing 21.2% of its total assets. This is a significant increase from 25.5% in the same period last year. The bank's net banking product (PNB) increased by 5.1% to 374.8 MDT, driven by a 57.0% increase in investment portfolio revenues.
The bank's interest margin declined by 22.3% to 125.0 MDT, due to a 6.6% decrease in interest income from customers. However, the investment portfolio generated 52.8 MDT in additional revenues, offsetting the decline in interest income. The bank's commission-based revenues decreased by 1.6% to 74.4 MDT, while foreign exchange gains increased by 14.9% to 38.5 MDT.
The bank's risk exposure increased, with classified receivables rising by 24.7% to 528.7 MDT. The coverage ratio for classified receivables decreased to 72.2%, down from 82.8% in the same period last year. The cost of risk increased by 66.2% to 22.0 MDT, driven by a nearly doubling of provisions for doubtful receivables.
The bank's operating result increased by 2.3% to 170.9 MDT, while net profit rose by 6.9 MDT. However, the financial statements lack transparency, with a significant variation in the "other ordinary items" line, which swung from a loss of 0.9 MDT to a gain of 12.4 MDT. The bank's tax burden increased by 20.6% to 60.3 MDT, resulting in an effective tax rate of 32.9%.
The bank's solidity and distribution policy remain strong, despite the challenges. The coefficient of exploitation improved to 50.9%, driven by a reversal of 1.7 MDT in provisions for paid holidays. However, the financial statements contain contradictions, which may impact the accuracy of the coefficient of exploitation.
Key points
- Attijari Bank's lending decreased to 58 dinars for every 100 dinars deposited in the first half of 2026.
- The bank's credit-to-deposit ratio decreased from 65.5% to 57.5% over the past year.
- The bank's exposure to the Treasury increased to 2,967.6 MDT, representing 21.2% of its total assets.
Reporting sources
- Attijari bank : Sur 100 dinars déposés, seulement 58 prêtés aux clients · African Manager