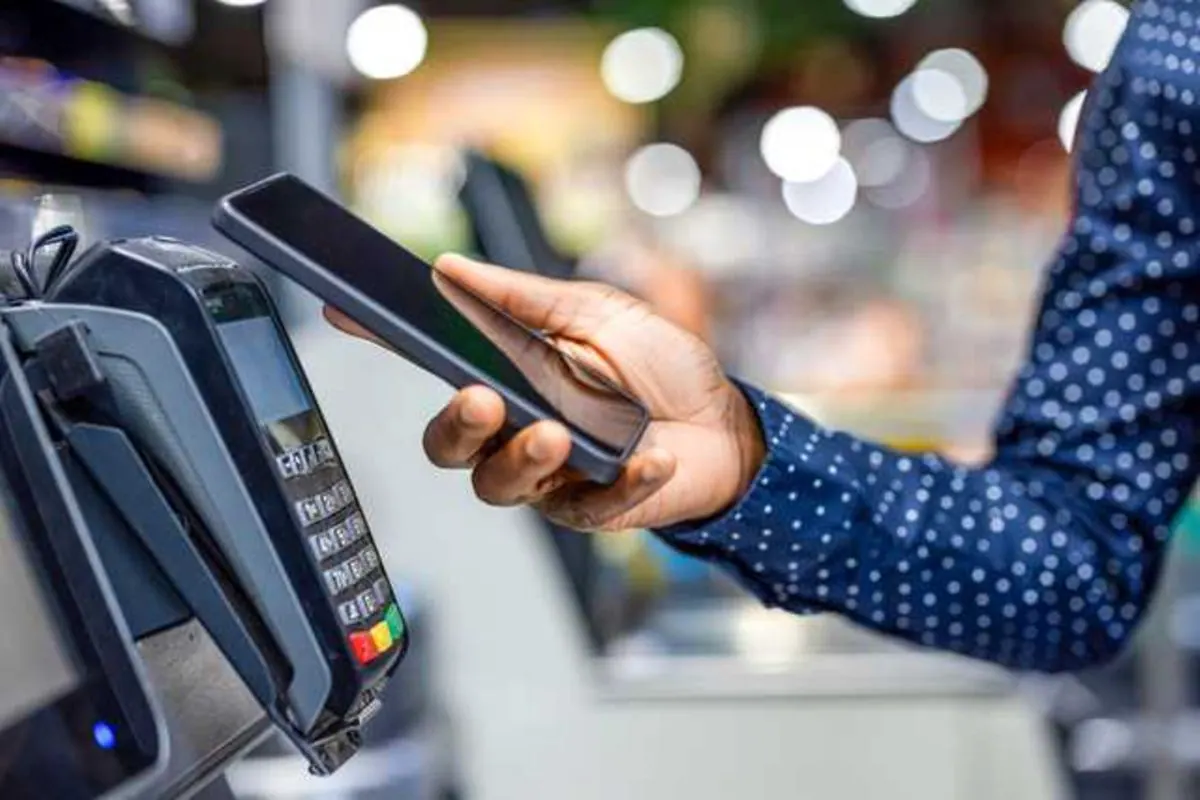
Africa's financial sector has made significant progress in access over the past two decades, with half a billion citizens now able to send, receive, save, and transact. However, this progress is incomplete, as access to financial services is not the same as financial health. The real measure of progress is whether households and businesses can absorb shocks, invest in the future, and participate productively in their economies. This is what builds resilient economies.
The next frontier for Africa's financial sector is interoperability, which requires connecting digital systems across borders. This involves creating a layer of infrastructure that includes connectivity, cloud, data centers, digital identity, payment rails, cybersecurity, and artificial intelligence. Beneath all of this is the need for reliable and affordable energy. The opportunity lies not in individual pieces of infrastructure but in how they connect to create value.
The M-Pesa ecosystem is an example of a successful digital financial system, serving over 103 million customers a month across six African countries. It connects them to over four million businesses and moves over $1.4 billion in value every day, carrying savings, credit, insurance, and social payments. The key is not the customer count but what it proves: infrastructure can compound when it reaches ordinary people.
To achieve this level of success, Africa needs to focus on building a sovereign digital stack that is open and accessible. This requires governments and central banks to set policy, standards, and safeguards that make trust possible at scale. Regulation must be adequate to create order but light enough to encourage innovation. The private sector brings investment, distribution, and execution.
The African Continental Free Trade Area is an example of a initiative that requires information, payments, identity, and regulatory data to move as easily as goods. This is not a hypothetical concept, as India and China have built digital stacks that reshaped how hundreds of millions transact. Africa's task is to learn from these examples and build its own version under its own governance.
The writer, Peter Ndegwa, CEO of Safaricom Plc, emphasizes that digital infrastructure is not just about technology but about empowering a generation to create opportunity. The temptation to wait for others to move first is a significant risk to the timeline. Collaboration between governments and the private sector is essential to make this happen.
Ultimately, Africa's transformation will be shaped by invisible infrastructure, authentication protocols, common standards, and trusted data-sharing frameworks. Artificial intelligence can accelerate this process, but it demands governance, privacy, and accountability for how decisions are made. The goal is to create a digital financial system that is resilient, secure, and inclusive.
Key points
- Africa's financial sector needs to shift focus from access to financial health and interoperability.
- Interoperability requires connecting digital systems across borders, creating a layer of infrastructure that includes connectivity, cloud, and data centers.
- The African Continental Free Trade Area requires information, payments, identity, and regulatory data to move as easily as goods.