The National Financial Ombudsman (NFO) of South Africa has raised concerns over the ease with which unsuspecting victims can become targets of organised criminals seeking to profit from their deaths through funeral policies. In a recent case, a high court judge expressed shock that people were being killed by ruthless syndicates to profit from funeral policies, often without the victims' knowledge. The NFO has suggested that urgent changes are needed within the life insurance industry to safeguard the lives of potential victims.
The NFO proposes that insurance companies obtain the informed consent of the life assured whenever cover is taken out on their life by another person. This, they believe, would enhance transparency, strengthen consumer protection, reduce opportunities for fraud and abuse, and assist insurers in verifying the legitimacy of policies at inception. While some insurance providers have implemented such measures, the NFO argues that improved standards across the industry would lead to better services for consumers.
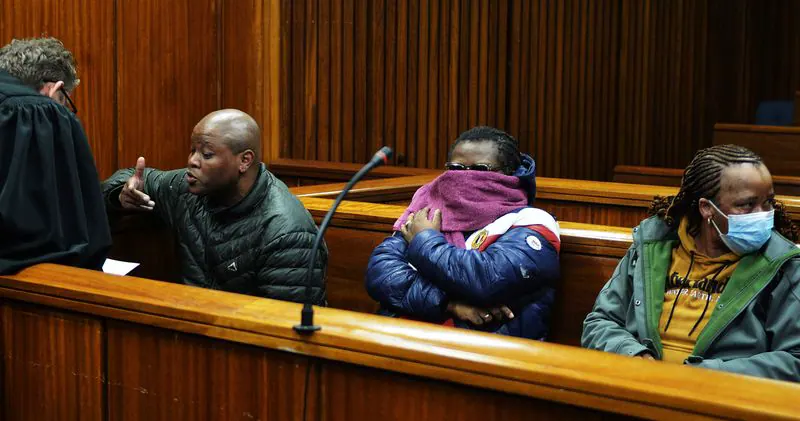
A recent case in the Eastern Cape Division of the High Court in Gqeberha highlighted the issue, with four accused facing charges related to a suspected murder-for-money racket. Siyabulela Mbane, Ntobeko Msome, Xolelwa Msome, and Unathi Peter are accused of lying about being related to the deceased to profit from their deaths, with alleged profits of over R1.7-million from fraudulent funeral policies. This is one of many cases under investigation by the police's Murder for Money (MFM) task team.
Senior public prosecutor advocate Louis Sinclair acknowledges the NFO's stance as a step in the right direction but believes further changes are required. He argues that certain policy structures, which offer double or triple payouts if a person dies of unnatural causes, incentivise criminals to commit these crimes. Sinclair suggests that doing away with these payout multipliers or changing the policies so that they do not pay out in the event of unnatural deaths could help prevent such crimes.
The NFO's lead ombud, Denise Gabriels, emphasises that justice delayed must not become justice denied. Where probes drag on unreasonably, or where police confirm that the beneficiary is not a suspect, insurers may be obliged to assess claims on their merits rather than leave families stranded in uncertainty. Gabriels adds that the NFO remains committed to ensuring that all parties are treated fairly and that indefinite delays do not undermine the rights of innocent policyholders and beneficiaries.
The insurance industry has introduced various measures to improve verification and reduce the risk of fraud, including the provision of certain documents like proof of address, bank statements, and payslips. Sanlam Retail Mass chief executive Bongani Madikiza welcomes the NFO's inputs but notes that no single intervention will solve the murder-for-money conundrum. He suggests that exploring additional safeguards, such as proof of the life assured's informed consent, could strengthen customer protection.
The issue has sparked a broader conversation about the need for comprehensive reforms in the life insurance industry to prevent such crimes. As the investigation into murder-for-money schemes continues, stakeholders are calling for a collaborative approach to address the root causes of these crimes and ensure that the industry prioritises consumer protection and safety.
Key points
- The National Financial Ombudsman proposes that insurance companies obtain the informed consent of the life assured to prevent murder-for-money schemes.
- Certain policy structures, which offer double or triple payouts for unnatural deaths, may incentivise criminals to commit these crimes.
- The insurance industry is exploring additional safeguards to strengthen customer protection and prevent fraud.