The practice of unregulated agencies playing a financial role of informal deposits taking has been growing in Nigeria. This has raised concerns among regulators and the government. A line of argument from abroad suggests that large retailers have quietly become unregulated banks, holding liquid cash in unspent gift cards, loyalty balances, and store credits. However, the situation in Nigeria is different, with customer balances sitting in pooled or trust accounts at licensed institutions and carrying Nigeria Deposit Insurance Corporation pass-through cover.
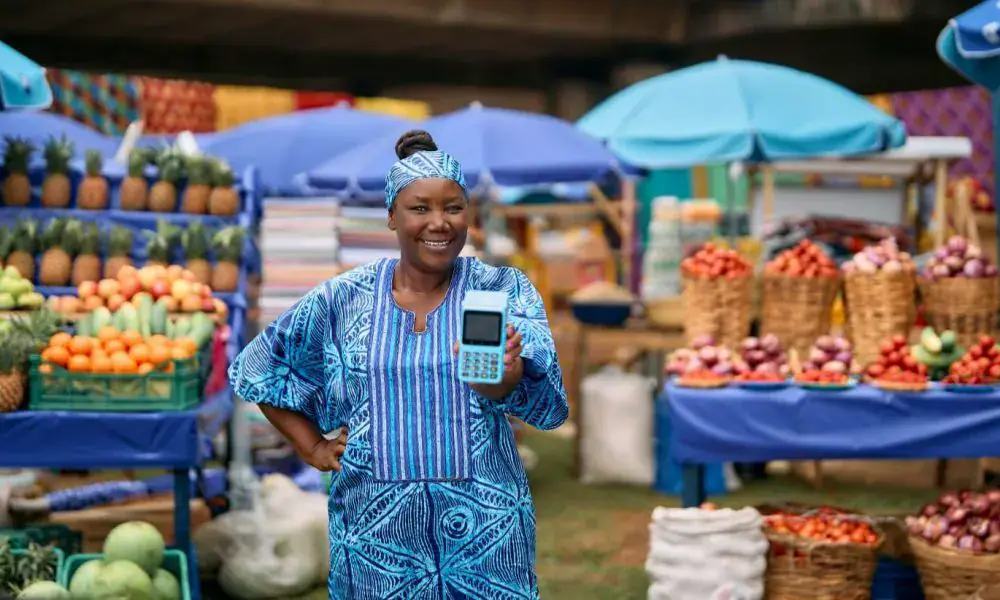
In Lagos markets, such as Balogun, Alaba, and the open stalls of Onitsha, traders use platforms like OPay, PalmPay, and Moniepoint to manage their finances. These platforms operate under Central Bank licences as mobile money operators or microfinance banks, providing customers with some level of protection. Customer balances are insured up to ₦5 million per subscriber for mobile money operators and ₦2 million for microfinance banks. This is a significant difference from the foreign practice, where customers have zero coverage.
The free-loan dynamic still exists in Nigeria, but the lender and borrower are different. When a market woman keeps working cash inside an OPay or Moniepoint wallet overnight, the platform or agent has temporary use of the money. The platforms can invest the float in government securities or short-term instruments while the user receives either zero interest or a modest savings rate on a separate product. A payments compliance lead described the practical result: the customer thinks the balance is just sitting there, but the platform has a short window to place it.
The siphoning of funds from traditional banks to fintech wallets is visible, with agents sourcing naira from market stalls and filling stations and parking the digital equivalent inside their principal's wallet. This has resulted in a thinner deposit base for community and mid-tier banks that might otherwise fund longer-term SME loans. The fintechs themselves have begun extending credit against the same customer data, but whether that credit reaches the open-market trader at usable rates remains uneven.
Gift cards form a parallel and less protected channel in Nigeria's financial market. The gift-card trading market is estimated to be in the low billions of dollars, driven largely by foreign cards that locals cannot easily redeem. Platforms that buy and sell them operate in a greyer zone and are not deposit-taking institutions, so the NDIC cover does not apply. Users who leave value on those platforms or hold unredeemed foreign cards are closer to the unsecured-creditor position.
Government regulation is not entirely blind, with the Central Bank licensing major wallets, setting agent rules, capping certain charges, and requiring ring-fencing in some group structures. The NDIC has raised coverage and clarified pass-through treatment for mobile money. However, oversight of pure closed-loop retail credits and the gift-card trading layer remains thinner. The Central Bank's recent sandbox for virtual assets and data-enabled services signals further attention, but rules for everyday loyalty points and informal store credit are not yet as tight as those for bank deposits.
The retailers and customers carrying the real exposure are those in the open-market, whose digital contact with the formal system is still largely a POS agent used as a cash bucket. Their working balances sit inside licensed fintech wallets that offer partial insurance and faster access than most bank branches, yet still leave them as temporary lenders to the platforms and agents that intermediate their cash. The free loan is real, but the unregulated retail giant of the foreign side is not the main holder of it.
Key points
- Unregulated agencies in Nigeria are warehousing customers' deposits in the financial market, posing risks to customers and the financial system.
- The situation in Nigeria differs from the foreign practice, with customer balances sitting in pooled or trust accounts at licensed institutions and carrying Nigeria Deposit Insurance Corporation pass-through cover.
- Government regulation is needed to oversee pure closed-loop retail credits and the gift-card trading layer to protect customers and the financial system.