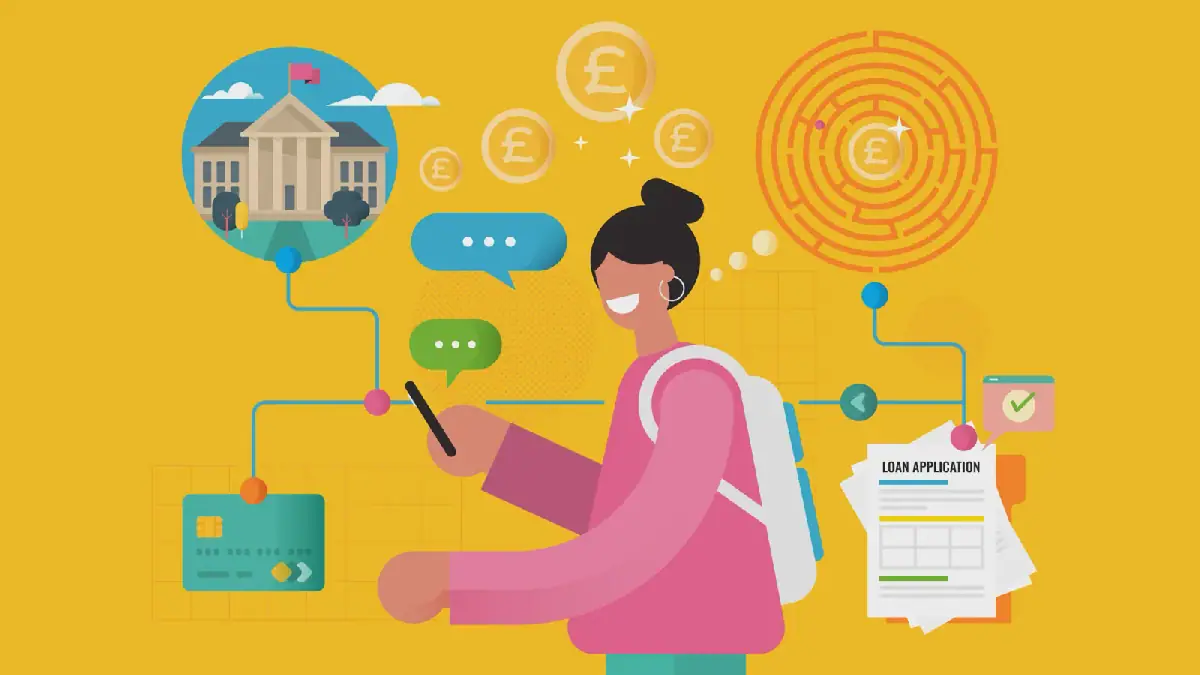
A recent study by connectivity network giffgaff reveals that many individuals, particularly young people, lack a clear understanding of credit scores and their implications. The research found that 67% of people believe young people are not adequately prepared to manage their credit profiles before applying for financial products. This knowledge gap can lead to poor financial decisions and difficulties in securing credit.
The study also discovered that only 7% of people learned about credit scores in school, highlighting a significant gap in financial education. As a result, many individuals are left to navigate the complex world of credit on their own, often relying on search engines for information. This can lead to costly mistakes, such as declined applications, multiple applications in a short period, and missed payments that can remain on credit reports for years.
giffgaff’s Chief Marketing Officer, Georgina Bramall, emphasized the importance of understanding credit basics before signing any agreements. Bramall noted that the company does not conduct credit checks for its SIM plans, allowing individuals with limited or no credit history to access their services. However, for many young people, purchasing a phone on a payment plan is often their first encounter with the credit system.
There are key differences between a credit report and a credit score. A credit report is a record of an individual’s credit accounts, payment history, and applications, while a credit score is a numerical value calculated from this information. In the UK, three main credit reference agencies – Experian, Equifax, and TransUnion – each calculate scores differently, and lenders use this information to determine whether to approve credit applications.
Checking one’s own credit report is free and does not affect the credit score. This is known as a “soft search,” which lenders cannot see. In contrast, applying for credit typically triggers a “hard search,” which can remain on the credit file for around a year. To gauge their chances of approval, individuals can use eligibility checkers, which rely on soft searches.
When borrowing credit, it is essential to understand the total cost, including interest and fees. The Annual Percentage Rate (APR) represents the yearly cost of borrowing, making it easier to compare deals. However, individuals should be cautious of “representative” APRs, as the advertised rate may not be offered to all successful applicants. Before signing any agreements, it is crucial to review the total repayment amount and the consequences of missed payments.
To manage credit effectively, individuals can take proactive steps, such as regularly checking their credit reports and understanding their credit scores. In the UK, individuals can access their credit reports for free through Experian, Equifax, and TransUnion, provided they have an address history for the past few years. By being informed and taking control of their credit, individuals can make better financial decisions and avoid potential pitfalls.
Key points
- Understanding the basics of credit scores and reports can help individuals make informed financial decisions.
Reporting sources
- The credit lessons nobody teaches you · The Big Issue Malawi