Uganda's financial sector is undergoing a significant transformation, driven by the growing demand for digital banking services. The country's economy, anchored by agriculture, services, manufacturing, and trade, is steadily growing, with small and medium enterprises contributing a significant share of national output. The young, urbanizing, and increasingly digital population is redefining expectations of financial services, prioritizing speed, simplicity, and seamless access to financial services.
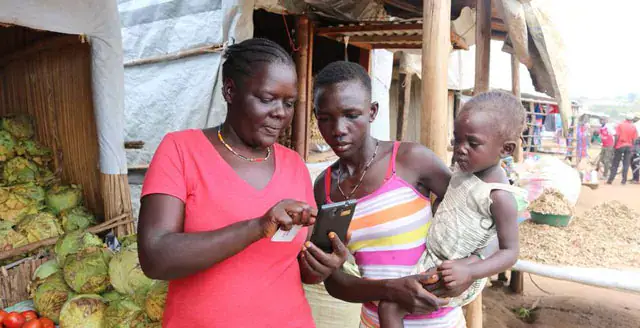
The traditional branch-led model is giving way to platform-based banking, with digital platforms taking over as the primary centre of financial activity. Physical branches remain important for advisory services and complex transactions, but digital platforms have reduced friction, improved transparency, and accelerated service delivery. Banks are investing heavily in mobile applications, USSD platforms, and integrated digital ecosystems that allow customers to send money, save, borrow, invest, and perform other transactions without physically visiting a branch.
The education sector illustrates this transformation clearly, with school fee payments being digitized, allowing parents to make instant payments, schools to receive funds in real-time, and administrators to reconcile accounts more efficiently. This has improved cash flow and strengthened institutional management. For small and medium enterprises, convenience is critical, as delays in accessing credit or working capital can directly disrupt operations, payroll, and growth.
Financial institutions that combine capital with capability building are better positioned to support enterprise growth and resilience. NCBA Bank Uganda has positioned itself within this shift by investing in digital-first financial solutions that prioritize speed, accessibility, and customer experience. Through solutions such as MoKash, the bank has enabled customers to access instant credit and savings products directly from their mobile phones.
NCBA Uganda has strengthened its SME proposition through asset finance and working capital solutions designed to address two of the most persistent constraints facing small businesses: limited collateral and cash flow pressure. By aligning financing to productive assets and business cycles, the bank is enabling more responsive and practical access to capital that reflects real economic activity.
East Africa continues to serve as a hub for financial innovation, particularly in digital financial services. Proven models across the region are increasingly being adapted to local contexts, allowing financial institutions to scale impact more efficiently and at lower cost. Convenience is also emerging as a powerful driver of financial inclusion, with women entrepreneurs, young people, and informal sector actors better able to access financial services.
Looking ahead, Uganda's financial sector will continue to evolve alongside broader trends in economic growth, urbanization, and digital adoption. As demand for faster, more integrated, and more responsive financial services intensifies, convenience will become increasingly important, enhancing productivity, strengthening inclusion, and supporting enterprise growth across all sectors of the economy.
Key points
- Convenience has become the new currency of banking in Uganda, and institutions that understand this shift will define the next phase of financial transformation.
Reporting sources
- Banks compete on speed as digital banking takes hold · The Independent magazine