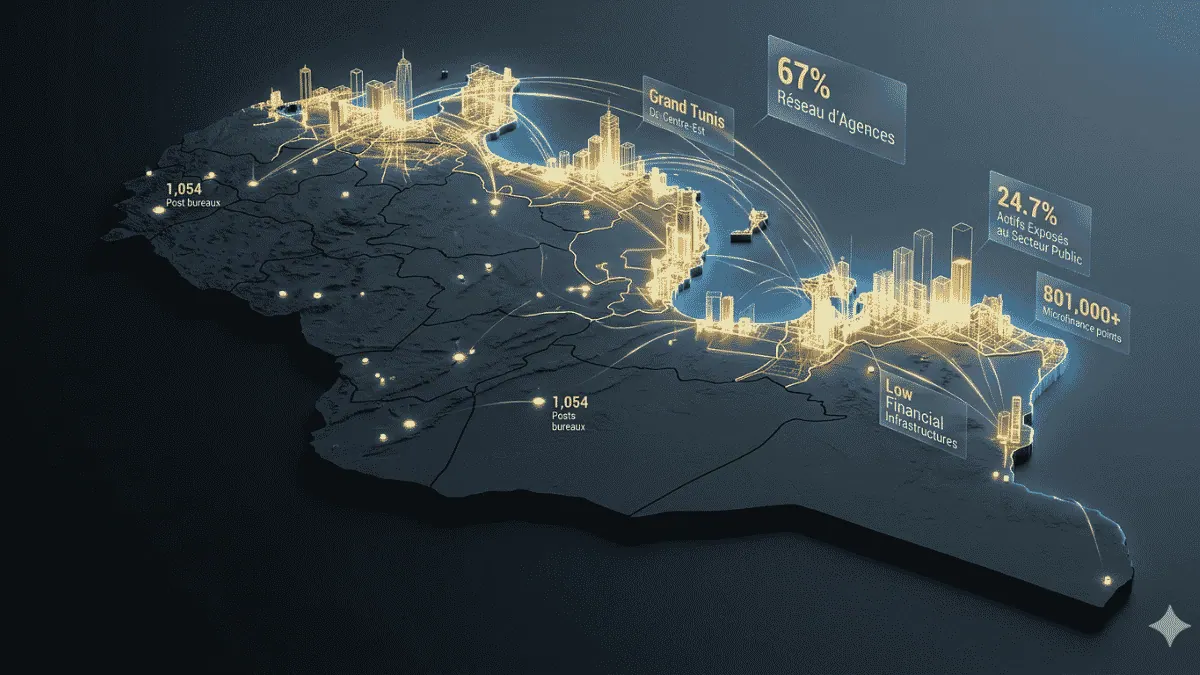
Tunisia's financial system is facing a paradox. Despite having a wide range of financial instruments, the country's economy is struggling to access credit for productive sectors. According to Fayçal Derbel, an expert-comptable and university teacher, the country's financial system has a dense prudential framework, updated banking laws, multiple guarantee devices, and active SICAR and FCPR. However, these instruments are not articulated, optimized, or sufficiently oriented towards the productive economy.
The country's macroeconomic indicators confirm this underperformance. In 2025, national investment represented only 15.5% of GDP, compared to 30% in Morocco, 21% in Jordan, and 15% in Egypt. The outstanding credit to non-public enterprises reached 123 billion dinars, for 125 billion dinars in deposits, reflecting stagnant intermediation. This situation is a structural brake on growth, particularly for SMEs, which represent 97% of the economic fabric.
One of the main obstacles identified is the massive credit to the state, which crowds out credit to enterprises. The state's claims on banks reach 56 billion dinars, with 36 billion dinars held by commercial banks. The Treasury bond has become the preferred asset: liquid, risk-free, and profitable. Some banks only lend 60% of the deposits collected, while they could go up to 120%. This eviction phenomenon deprives enterprises, particularly SMEs and startups, of essential financing.
Another obstacle is the absence of a risk culture and hypertrophied guarantees. Banks sometimes require guarantees representing 2.5 to 4 times the borrowed amount. Intangible companies, service activities, or high-growth companies are penalized or excluded. The guarantee device itself is fragmented: SOTUGAR, National Guarantee Fund, and sectoral funds. In contrast, Morocco has created a single operator, Tamwilcom, capable of covering up to 80% of the risk, with a fully digitalized process.
The factoring, securitization, and stock market levers are under-exploited. The financing of invoices is almost non-existent, with only two factoring companies and a few bank departments. The total outstanding amount does not exceed 281 million dinars, down 35% in 2025. Securitization has remained embryonic, with only two operations in twenty-five years. The stock market also remains an unexplored lever, with a capitalization representing 17 to 20% of GDP, far from regional standards.
The capital-investment sector has a bridled potential. Between 2011 and 2025, Tunisian capital-investment financed 2,725 companies, for 5.2 billion dinars, or 2.8% of 2025 GDP. In 2025, investments reached 740 million dinars, or 0.4% of GDP. These figures remain modest compared to the needs of transforming the productive fabric. The handicaps are known: limited legal instruments, absence of a secondary market, mandatory retrocession, and constraining exchange control.
To build a new financing ecosystem, Fayçal Derbel recommends coherent and interdependent reforms. These reforms aim to rebalance the risk-return arbitrage in favor of productive financing. The goal is to gradually reduce the state's share in bank balance sheets, introduce prudential incentives for innovation, investment, and energy transition credits, and reserve certain refinancing from the BCT to banks financing SMEs.
Key points
- The Tunisian financial system has a comprehensive array of financial instruments but struggles with underperformance and limited access to credit for productive sectors.
- The country's macroeconomic indicators confirm this underperformance, with national investment representing only 15.5% of GDP in 2025.
- Reforms are needed to rebalance the risk-return arbitrage in favor of productive financing and to build a new financing ecosystem.