East Africa has made significant progress in digital payments, becoming a global leader in mobile payments. The region continues to evolve as consumers switch between mobile money, cards, digital wallets, apps, and online marketplaces. With more commerce moving online, trust is becoming a deciding factor in whether people and businesses participate in and transact online. The focus is shifting from access to ensuring secure and seamless transactions.
Kenya is a prime example of the region's progress, with 95% of small and medium-sized enterprises (SMEs) accepting mobile payments and 39% accepting online payments. About 70% of Kenyan SMEs expect their revenues to grow over the coming year, demonstrating the importance of digital tools and the ambition to scale. This growth presents an opportunity and a responsibility for the ecosystem to ensure secure and trustworthy transactions.
Card-not-present transactions, where payment credentials are transmitted digitally, have transformed commerce. Consumers can purchase from businesses they've never visited, and small businesses can reach customers beyond their physical location. However, this convenience also means that trust signals behind every transaction need to be assessed digitally. The ecosystem must determine whether payment credentials, devices, merchants, customer behavior, and transactions make sense together, often within milliseconds.
Mastercard data shows that 70% of card-related fraud occurs in card-not-present transactions, highlighting the need for evolving digital commerce security. In Kenya, 2.3% of transaction attempts in 2025 were suspected of digital fraud, according to TransUnion. Among Kenyan consumers who reported losing money to digital fraud, 39% cited third-party seller scams on legitimate websites as the cause. This emphasizes that much of the risk lies outside the payment credential itself.
The East African Community has recognized this challenge through its regional e-commerce agenda, focusing on creating an enabling environment for cross-border digital trade while strengthening consumer protection, digital identity, and trust in online transactions. The goal is to use technology and intelligence to identify genuine risk while allowing legitimate commerce to continue. Tokenization is one example, replacing sensitive payment credentials with a unique digital token.
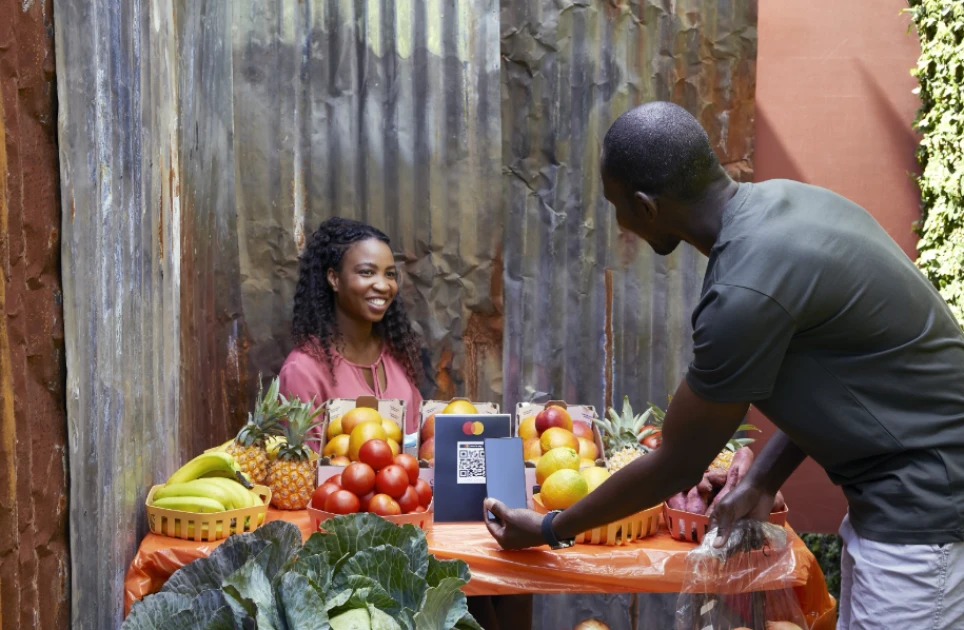
Mastercard's collaboration with various financial institutions in East Africa reflects the increasingly connected payment ecosystem. The partnership with KCB spans multiple countries, supporting solutions like e-commerce payments, cross-border remittances, and QR payments. Similar collaborations in Kenya, Uganda, and Tanzania aim to reach more merchants and enable businesses to participate in digital and international commerce.
As digital commerce becomes more embedded in everyday life, security needs to become more sophisticated and less visible. The objective is not to treat every transaction as suspicious but to understand which transactions make sense, so scrutiny falls where it belongs. With the right infrastructure and technology in place, East Africa's payment ecosystem can build trust and support the growth of digital commerce in the region.
Key points
- East Africa leads in mobile payments globally, but trust is now crucial for online transactions.
- 70% of card-related fraud occurs in card-not-present transactions.
- The East African Community is working to strengthen consumer protection, digital identity, and trust in online transactions.