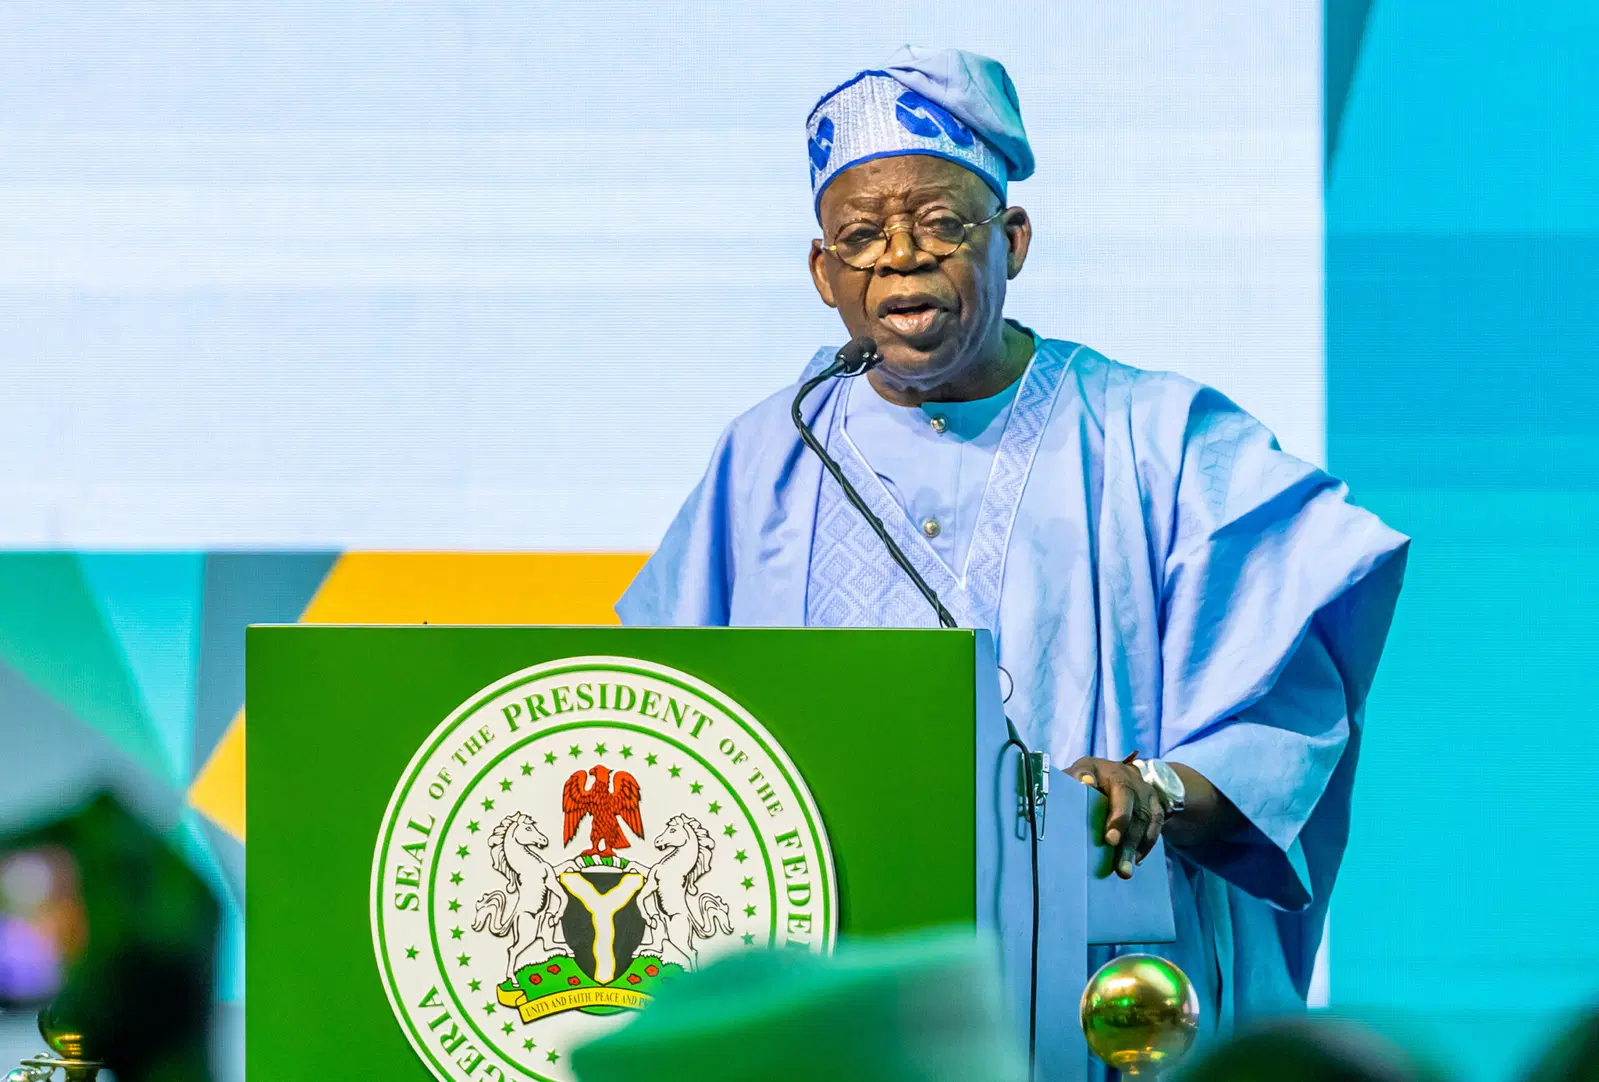
President Bola Tinubu has noted that the World Bank's October 2026 Nigeria Development Update shows that the Federal Government's economic reforms are stabilising the economy and increasing resources available for development. The report highlights improvements in economic growth, inflation, external reserves, and government revenues, as well as increased capital expenditure by state governments. Tinubu stated that the findings confirm the impact of the removal of the petrol subsidy, unification of the foreign exchange market, and efforts to strengthen fiscal discipline.
According to the report, Nigeria's economy grew by 4.2 per cent in the first half of 2026, compared with 3.9 per cent in the corresponding period of 2025, despite the impact of the conflict in the Middle East. The World Bank projects that economic growth will average at least 4.4 per cent annually between 2026 and 2028. The report also found that Nigeria's poverty rate had stabilised for the first time since 2019 and projected that poverty would decline gradually as economic growth outpaces population growth.
The World Bank report showed that Nigeria's inflation rate fell from 27.6 per cent in January 2025 to 15.2 per cent in December 2025. However, higher global fuel prices linked to the Middle East conflict have slowed the decline. The World Bank expects inflation to ease to about 12 per cent by 2028. Tinubu said his administration would sustain the reforms while intensifying efforts to improve living conditions, particularly through lower food prices and increased employment opportunities.
Nigeria's external position also improved, with the current account surplus rising to $12 billion, representing 7.0 per cent of gross domestic product, in the first half of 2026, from $8.6 billion in the corresponding period of 2025. Gross external reserves increased from $45.5 billion at the end of 2025 to $53.8 billion at the end of August 2026. The report further projected that Nigeria's public debt would decline from 40.0 per cent of GDP in 2025 to 38.1 per cent in 2026.
The World Bank attributed a 69 per cent increase in federation revenues in real terms between 2023 and 2025 to reforms introduced since 2023. State governments were identified as the largest beneficiaries of the additional revenue. The report said states increased capital expenditure by 151 per cent in real terms over the same period, with most of the spending directed towards roads and other transport infrastructure, agriculture, energy, and housing.
Tinubu urged state governments to manage their increased revenues prudently and prioritise projects that improve public welfare. He also announced plans to expand targeted cash transfers, accelerate the deployment of compressed natural gas, increase agricultural productivity, and improve access to affordable healthcare and quality education. The President commended the Economic Management Team and state governors for their cooperation in implementing the reforms.
Tinubu assured Nigerians that the best is yet to come under the Renewed Hope Agenda 2.0, which will accelerate the delivery of shared prosperity for all Nigerians. The administration will continue its policies, with a focus on delivering shared prosperity. The cash transfer programme had already reached more than 10 million households, and the President promised to continue expanding the programme.
Key points
- President Bola Tinubu says Nigeria's economic reforms are yielding positive results, citing a World Bank report.
- The report highlights improvements in economic growth, inflation, external reserves, and government revenues.
- Tinubu urges state governments to manage their increased revenues prudently and prioritise projects that improve public welfare.