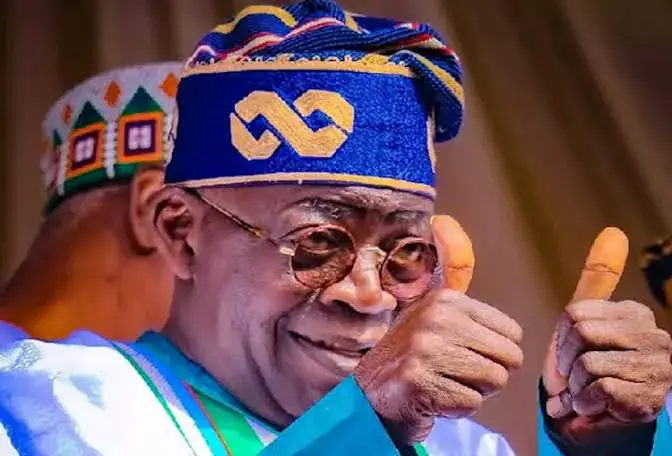
President Bola Tinubu has issued a strong response to critics of his government's borrowing plans, particularly opposition leaders. In a recent essay, Tinubu emphasized that the success of his administration's economic policies will be evaluated based on completed projects, employment generation, and improved living standards. He argued that the focus should not be on the amount borrowed, but on the value created and the future left behind for Nigeria.
Tinubu identified several major projects expected to boost Nigeria's productive capacity, including the Lagos-Calabar Coastal Highway, Sokoto-Badagry Superhighway, Trans-Sahara Superhighway, electricity grid upgrades, and the modernization of key commercial ports in Lagos. These projects, he said, will connect economic regions, reduce logistics costs, unlock agricultural and industrial potential, and attract private investment. The Lagos-Calabar Coastal Highway, for instance, is expected to cut logistics costs by 15 to 20 percent and add up to two percent to Nigeria's GDP.
The Lagos-Calabar Coastal Highway project is also projected to generate about 100,000 direct jobs in construction and engineering, as well as over 150,000 indirect jobs in logistics, materials, and related services. Tinubu emphasized that his administration is not just building highways, but opening economic corridors, connecting markets, unlocking industries, and reshaping Nigeria's economic geography. He stressed that sustained infrastructure investment is crucial to supporting higher productivity, industrialization, and trade.
Tinubu disclosed that his administration's ambition to build a $1 trillion economy by 2030 requires sustained infrastructure investment. He noted that Nigeria cannot build a $1 trillion economy with infrastructure designed for an economy a fraction of that size. The president said improving economic indicators and growing international investor confidence are creating opportunities for Nigeria to attract long-term investment and expand critical infrastructure.
According to Tinubu, the economic reforms introduced in May 2023 helped restore macroeconomic stability, strengthen public finances, and improve the country's standing in international financial markets. He cited positive economic indicators, including a 4.43 percent real Gross Domestic Product growth in the second quarter of 2026 and a decline in headline inflation to 14.63 percent in September from 20.98 percent a year earlier.
Tinubu also highlighted improvements in the country's external reserves, which rose to $55.1 billion as of October 9, 2026, including about $46 billion in net reserves. He noted that the tax-to-GDP ratio increased to 12.5 percent from seven percent. The president attributed these improvements to measures, including the removal of petrol subsidies and exchange rate reforms.
Tinubu concluded that building a $1 trillion economy will not be achieved by declaration alone, but through sustained investment, higher productivity, industrialization, and trade. He emphasized that infrastructure development will be critical to achieving this target by 2030. The president's statement is seen as a response to concerns about the government's borrowing plans and its ability to drive economic growth and development.
Key points
- President Tinubu defends government's borrowing plans, citing investments in infrastructure to drive economic growth.
- Nigeria aims to build a $1 trillion economy by 2030 through sustained investment and infrastructure development.
- The government's economic reforms have led to improvements in macroeconomic stability, public finances, and international investor confidence.