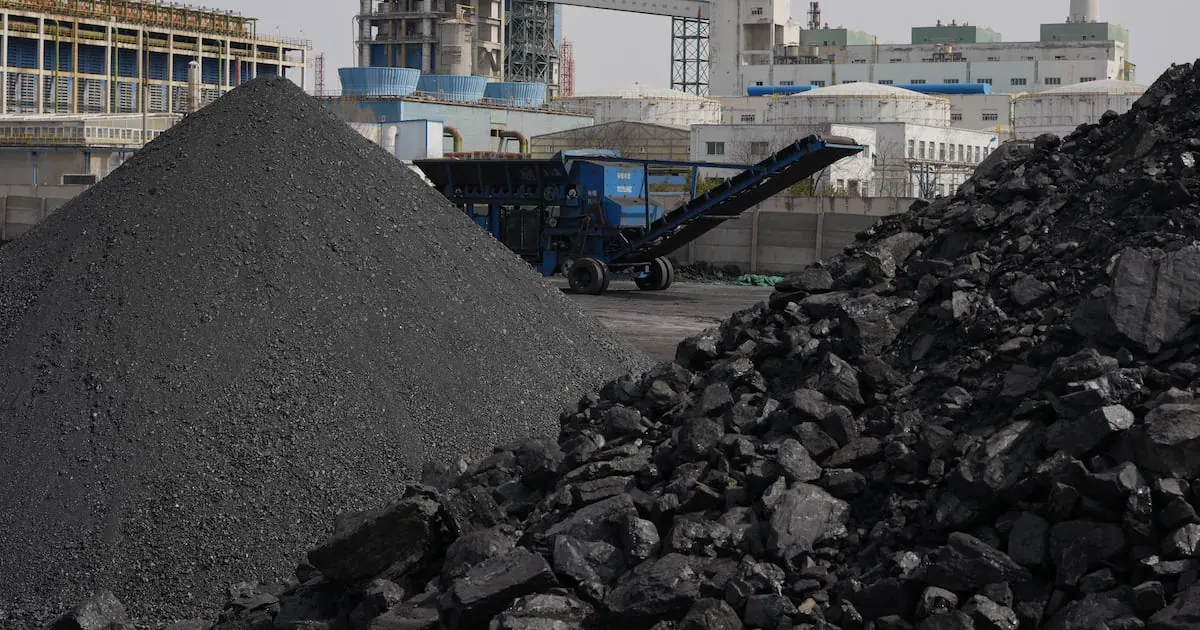
South Africa's mining sector has entered the 2026 reporting period in a stronger position than previously, but the lack of real investment in recent years means output levels are still under pressure. This prevents companies from fully benefiting from high commodity prices. According to a report by professional services firm PwC, the sector's overall position is stronger, but challenges persist. The report highlights that energy reliability has improved from the worst periods of load-shedding, but cost and availability remain important considerations for energy-intensive mining and beneficiation operations.
Logistics are also a significant constraint, particularly on bulk commodity export corridors where rail and port underperformance affect realised prices, production planning, and customer reliability. A recent assessment by Moody’s found that while South Africa is better positioned than most countries on the continent to move beyond mining into higher-value processing of critical minerals, logistics bottlenecks and policy uncertainty continue to limit investment. The PwC report notes that exploration remains one of the industry's most important constraints, despite a mineral endowment that has increased in 2023-26.
Gold reserves in South Africa have risen from 68-million ounces to 77-million ounces, with estimated average mine life increasing from 27 to 29 years. PGM reserves have increased from 261-million to 298-million ounces, with estimated average mine life increasing from 38 to 43 years. Iron ore reserves have also increased from 696-million tonnes to 1,101-million tonnes, with estimated mine life increasing from 13 to 23 years. However, investor appetite for early-stage exploration has been weakened by regulatory complexity, permitting timeline uncertainty, and eventual project realisation uncertainty due to infrastructure constraints, ownership, tenure, and cost considerations.
The result is a project pipeline weighted toward brownfield optimisation — improving, expanding, or modernising existing, mature mining operations — rather than material new discoveries. Andries Rossouw, Africa energy, utilities, and resources leader at PwC South Africa, said that the improvement in reserve positions shows what becomes possible when South Africa combines its geological strengths with investment, technology, prices, and technical expertise. This creates scope to extend productive operations and improve the economics of existing resources.
Maximising value from existing mines is essential, but a competitive enabling environment for new mine investments is needed, with a thriving mining ecosystem that encourages investment in exploration, infrastructure, and innovation. Other headwinds facing the sector include safety risks, rising labour and input costs, declining ore grades, environmental compliance costs, and illegal mining. For the first time in its more than 150 years of mineral extraction, South Africa has finally classified illegal mining as an unlawful act, with perpetrators facing a maximum jail term of 30 years.
The classification of illegal mining as an unlawful act aims to clamp down on a scourge that drains as much as R70bn from the economy annually. Amendments to the Criminal Procedure Act and other relevant laws approved by cabinet will close a loophole that had seen perpetrators only face minor charges such as trespassing or fines of as little as R300. South Africa remains central to global PGM supply, accounting for a substantial share of global platinum and palladium output while remaining the dominant supplier of rhodium, iridium, and ruthenium.
Medium- to long-term support for PGMs is likely to come from a combination of a lack of supply and demand diversification, with notable price increases for ruthenium on the back of data storage applications. The hydrogen economy also remains an important optionality driver, with platinum and iridium used in electrolysers and fuel-cell technologies, though large-scale commercial demand is still developing. However, constraints on the supply side, including ageing South African assets and constrained investment across the industry, are likely to limit future supply growth.
Key points
- The mining sector faces challenges despite stronger reserves, with production expectations tightened due to restructuring initiatives and limited new project development.
- Logistics bottlenecks and policy uncertainty continue to limit investment in the sector.
- The sector needs a competitive enabling environment for new mine investments, with a thriving mining ecosystem that encourages investment in exploration, infrastructure, and innovation.