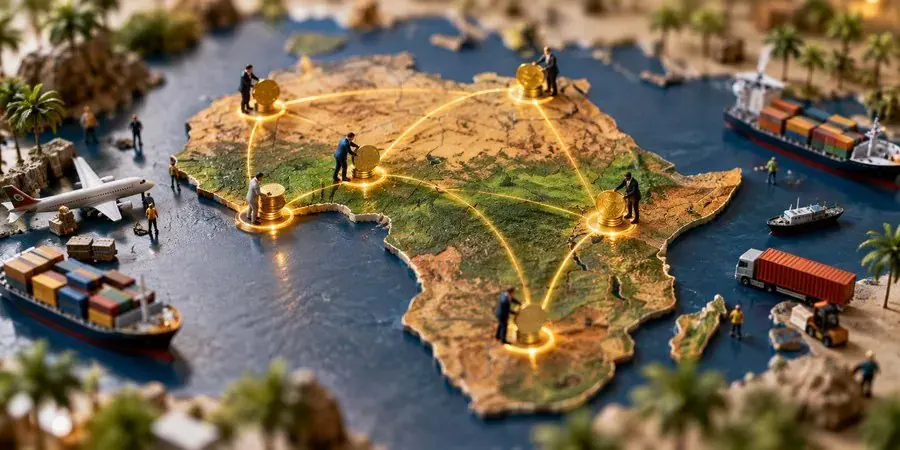
Africa's investment landscape is becoming increasingly concentrated, with six markets attracting the majority of the continent's foreign direct investment. This trend is driven by investors seeking depth, policy credibility, and reliable infrastructure. The six leading destinations - Nigeria, Egypt, Kenya, South Africa, Morocco, and Côte d'Ivoire - offer a combination of scale, connectivity, and established investment channels that make them attractive to investors.
Nigeria, with its large consumer economy and deep energy links, is a major draw for investors. Egypt, on the other hand, provides industrial capacity, logistics access, and proximity to Europe and the Gulf. Kenya serves as East Africa's commercial and financial hub, while South Africa boasts the continent's deepest capital markets and broadest corporate base. Morocco connects African production networks to European trade routes, and Côte d'Ivoire adds a francophone West African gateway.
The concentration of FDI in these six markets can be attributed to three structural drivers. Investors first assess market size and depth, then track policy stability and reform signals, and finally price physical and institutional infrastructure. This approach allows investors to separate repeatable market capacity from single-event flows, according to standard development finance practice.
While headline FDI figures may be impressive, they require careful reading. Egypt's 2025 inflows, for example, reflect a large national result that may include one-off transactions. Nigeria's total is also linked substantially to oil and gas project finance. Investors must be cautious when evaluating these figures to ensure accurate assessments.
Nine markets, including Mauritius, Uganda, Ghana, Ethiopia, Senegal, Rwanda, Mozambique, Tanzania, and Botswana, show clear momentum and are advancing in terms of FDI. However, gaps in infrastructure, scale, and institutional capacity still limit their pull on large capital allocations. Policymakers in these markets must focus on improving infrastructure, credibility, and institutions to widen access to capital.
The African Credit Rating Agency (AfCRA), an African Union-mandated institution headquartered in Port Louis, Mauritius, represents a step towards institutional deepening. Over time, it can support broader market access across the continent, in line with UN Trade and Development frameworks for investment facilitation. Regional cooperation can also help smaller markets achieve the scale that investors require.
For investors, a continent-wide strategy is too broad, and country selection must guide sector allocation, currency planning, partner assessment, and exit design. Infrastructure investors should examine both physical networks and the institutions that govern them. The key signal to watch is whether these markets can provide the necessary infrastructure and institutional capacity to support large-scale investments.
Key points
- Six African markets - Nigeria, Egypt, Kenya, South Africa, Morocco, and Côte d'Ivoire - dominate continental FDI.
- Investors prioritize market size, policy stability, and infrastructure when evaluating investment opportunities.
- Policymakers in smaller markets must focus on improving infrastructure, credibility, and institutions to widen access to capital.