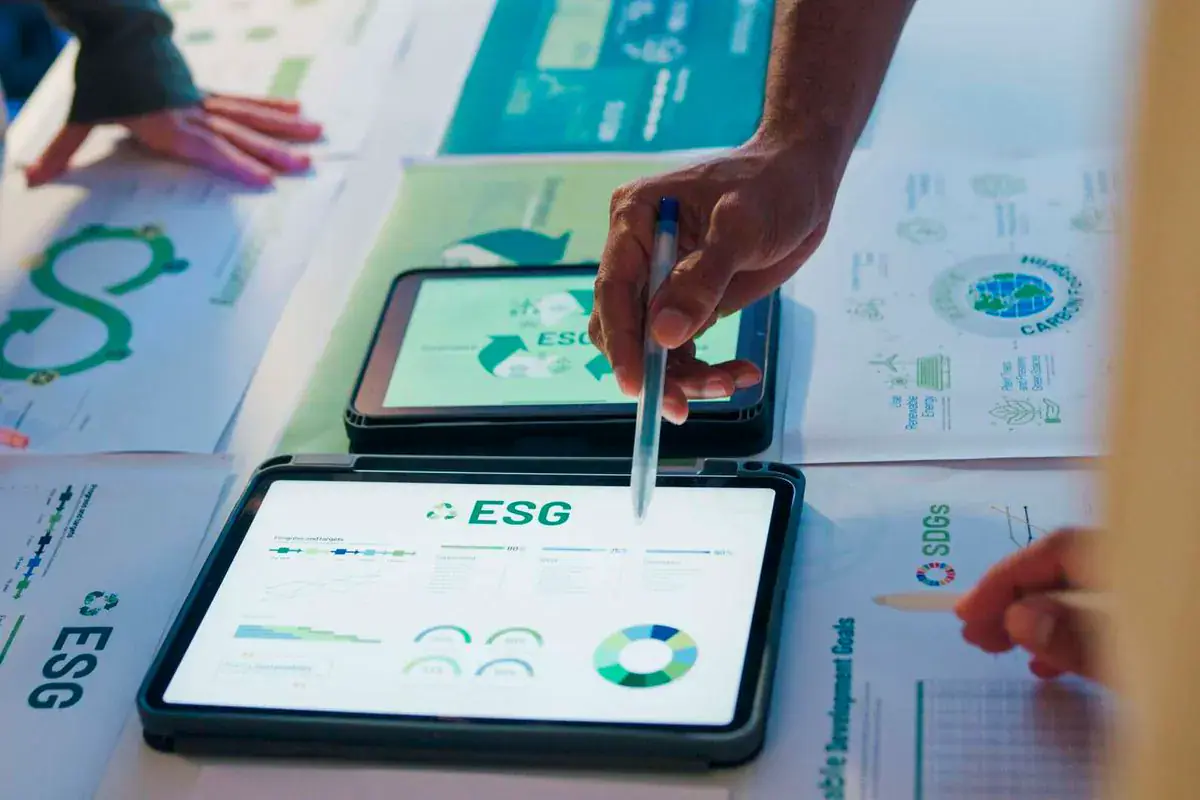
Organisations in Kenya are increasingly recognising the importance of sustainability reporting, but often overlook the crucial aspect of assurance. According to Akinyemi Awodumila, a Partner at PwC Kenya, assurance considerations should be included at every step of the sustainability reporting process. This approach enables organisations to prepare better and achieve a more comprehensive and effective overall assurance environment. By integrating assurance considerations from the beginning, organisations can avoid major gaps and significant changes later on.
An effective assurance framework is required to deliver reliable and accurate disclosures. Awodumila emphasises that understanding how to prepare for sustainability reporting assurance while implementing it is crucial to build stakeholder trust through high-quality reporting. Some organisations have had to revisit their sustainability reporting processes due to assurance considerations revealing major gaps that could not be ignored. This highlights the importance of early consideration of assurance in the sustainability reporting process.
Assurance considerations should begin with internal stakeholders who rely on sustainability data for decision-making and extend to external stakeholders through statutory reporting. Data quality considerations across the entire sustainability process are important, as poor-quality data leads to suboptimal management decisions. Organisations should invest in systems and resources that improve sustainability data quality, ensuring that information is complete, accurate and consistently defined.
Governance and oversight structures are another essential consideration for organisations in Kenya. Oversight for reporting should define the roles and responsibilities of different internal stakeholders, starting with board reporting and executive management accountability, and extending to functional teams across the organisation. This helps foster accountability and transparency in sustainability reporting, which is critical for building stakeholder trust.
Once critical sustainability-related processes are identified, organisations should consider developing internal control mechanisms embedded within the three lines of defence. These include Operational Management, Risk and Compliance, and Internal Audit. Clear ownership of processes, controls, data, and disclosure preparation, including oversight with agreed reporting timelines, is also essential. This helps ensure that sustainability reporting is accurate, reliable, and transparent.
Organisations should document the key methodologies, assumptions, and reporting boundaries used to prepare sustainability disclosures. This ensures that there are evidence trails that make processes repeatable and auditable when required. By documenting these details, organisations can verify information and support a smooth audit process. This is particularly important for organisations in Kenya that are seeking to build stakeholder trust through high-quality sustainability reporting.
Akinyemi Awodumila, a Partner at PwC Kenya, advises organisations to prioritise assurance considerations in their sustainability reporting processes. By doing so, organisations can ensure that their sustainability reporting is accurate, reliable, and transparent, which is critical for building stakeholder trust. Key considerations include data quality, governance and oversight structures, and internal control mechanisms. By integrating these considerations, organisations can achieve a more comprehensive and effective overall assurance environment.
Key points
- Organisations should integrate assurance considerations into their sustainability reporting processes from the outset to build stakeholder trust.
Reporting sources
- How to get your firm prepared for sustainability reporting assurance · Business Daily Africa