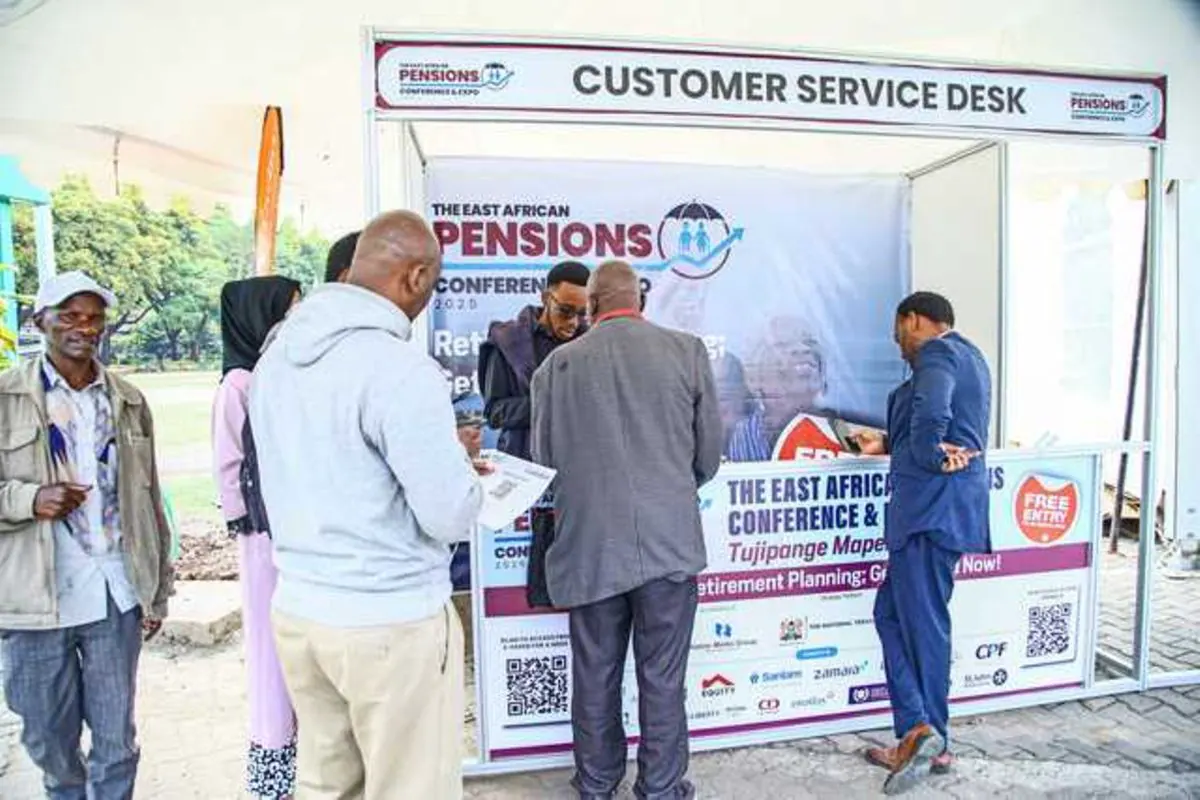
Kenya's retirement benefits sector has experienced remarkable growth, managing Sh2.8 trillion in assets, equivalent to 14.5 percent of the country's gross domestic product. The sector has evolved from a fragmented, unregulated industry to a well-regulated one, with the Retirement Benefits Authority (RBA) established in 2000. The RBA's regulatory efforts have helped to supervise the sector, which had previously operated under a patchwork of trust. This growth has been significant, but the sector's next phase of expansion will focus on member engagement.
The pension sector has undergone significant changes, including a product reconfiguration in the 2010s. The number of schemes increased exponentially, and investment guidelines matured in consistency with the law. The public pensions space also began a structural shift from a defined benefits to a defined contributions arrangement. The Public Service Superannuation Scheme Act reorganized the administration of public pensions for hundreds of thousands of workers, leading to the operationalization of the scheme in 2021. This shift moved responsibility for retirement outcomes from institutions to individuals.
Despite the sector's growth, millions of Kenyans do not understand, trust, or use the retirement products designed for them. The RBA's statistical digest shows that the sector recorded an overall membership coverage ratio of 26.58 percent in 2025, equivalent to 7.71 million members out of an estimated working-age population of 29 million. This growth has been significant, but it is still marginal as a percentage of the working-age population and is highly concentrated among urban, male, and wealthier, middle-aged Kenyans.
The growth of the sector in the coming years will hinge on awareness, trust, and habit. With the global shift from defined benefit to defined contribution arrangements, members have inherited the decisions that employers once made on their behalf. Researchers argue that when members are engaged through commitments and well-structured nudges, participants and contribution rates rise substantially. The import for Kenya is that while it has had its own shift toward direct contribution arrangements, there is a greater role for members in enhancing their retirement adequacy.
Pension schemes need to help members exercise their responsibility and engage with their retirement planning. The common thread across guidance offered by bodies such as the OECD on pension communication is that members save more when they understand what they are saving for, can track their progress, and are engaged in a participatory approach in a language and channels that reflect their reality. Communicating in clear, accessible language, as well as digital self-service tools, grants members access to their contributions and projected benefits.
Building trust and sustained engagement with members cannot replace the rigour of investments and pension administration, but it complements efforts to create a holistic experience for the member. The pension sector has done the hard work of setting up broad legislation and harmonizing supervision of the industry in the last three decades, but its next phase of growth must focus on helping members engage with their retirement future. This phase will also require a structural shift in how the industry's success is measured.
The industry's success has predominantly been measured by growth in assets under management, but a key metric of the next decade must be the number of members who understand their pension, trust the pension scheme managing their savings, and are actively contributing to their retirement security. According to Dr. Jonah Aiyabei, the Chief Executive Officer of the Public Service Superannuation Fund (PSSF), the next decade of pension sector growth will come from deliberate, sustained initiative to help ordinary Kenyans understand, actively participate in, and trust their own retirement planning.
Key points
- The pension sector's growth in the coming years will depend on awareness, trust, and habit among members.
- The industry's next phase of growth will focus on helping members engage with their retirement future.
- A key metric of the next decade must be the number of members who understand their pension, trust the pension scheme, and are actively contributing to their retirement security.