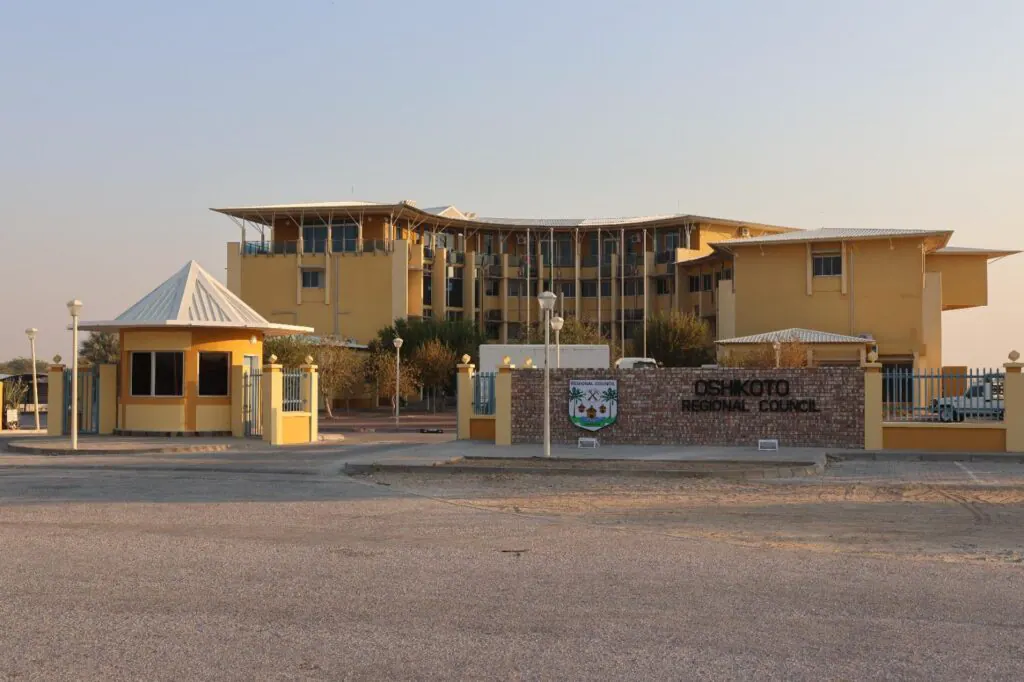
The Oshikoto Regional Council in Namibia has received a qualified audit opinion due to concerns over investments worth N$5.5 million. An auditor-general report could not confirm the existence, ownership, and valuation of these investments. The investments in question are in the Northern Regional Electricity Distributor and Central North Regional Electricity Distributor. The report highlights incomplete documentation and a lack of subsequent valuations since 2014.
The auditor-general, Junias Kandjeke, notes that the council's investments were made in 2014, but no valuations have been conducted since then. This contravenes International Public Sector Accounting Standard 36. The council also holds shares in Regional Councils Electricity Company, which has a 33% interest in Nored amounting to N$5 million. However, the absence of a joint venture agreement and company status reports makes it difficult to determine the individual shareholding and corresponding value attributable to the Oshikoto region.
The audit report also reveals that the council's financial performance deteriorated, with a N$6.4 million deficit recorded for the year ended 31 March 2024. This is compared to a surplus of N$18.8 million in 2023. The council's total assets stood at about N$168.7 million as at 31 March 2024, down from N$174.9 million the previous year. These findings have raised concerns about the accuracy of the council's financial statements.
Furthermore, the audit found that the council did not comply with reporting timelines. The annual plan review and extended strategic plan review matrix were submitted late, on 17 April 2025. The financial statements were also submitted to the auditor-general on 1 April 2025, despite an extension that had ended on 30 September 2024. The Regional Councils Act requires timely submissions, but the council failed to meet these deadlines.
The Oshikoto Regional Council's management and staff are acknowledged for their co-operation and assistance during the audit. However, the report emphasizes the need for the council to address these concerns and ensure accurate financial reporting. The council's investments and financial performance will likely be closely monitored in the future.
The qualified audit opinion may have implications for the council's credibility and ability to secure funding. It is essential for the council to take corrective action to address the concerns raised in the audit report. This includes obtaining accurate valuations of its investments and ensuring compliance with reporting requirements.
The auditor-general's report has been tabled in the National Assembly, highlighting the need for improved financial management and accountability in the region. The Oshikoto Regional Council must take steps to rectify the issues identified and ensure transparent and accurate financial reporting.
Key points
- The Oshikoto Regional Council's investments worth N$5.5 million are under scrutiny due to incomplete documentation and lack of valuations.
- The council's financial performance deteriorated, with a N$6.4 million deficit recorded for the year ended 31 March 2024.
- The audit report highlights the need for improved financial management and accountability in the region.