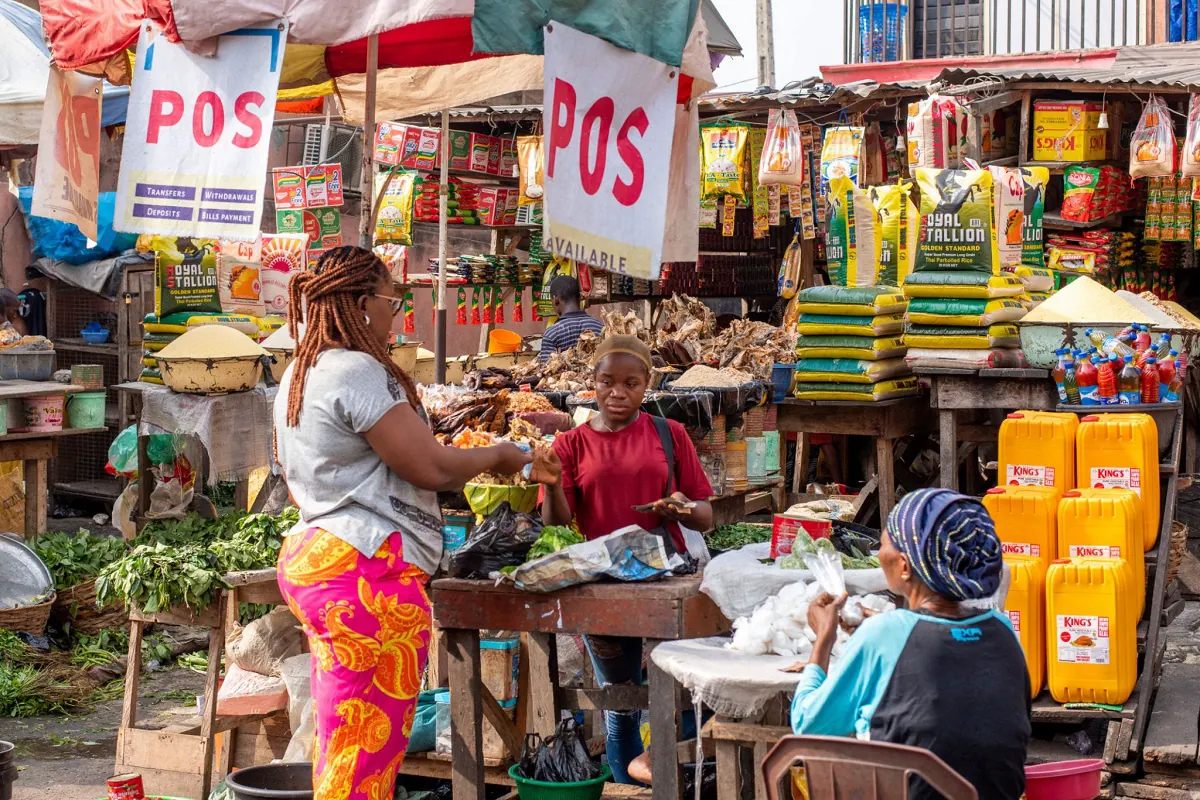
The Access to Financial Services in Nigeria (A2F) Survey by Enhancing Financial Innovation and Access (EFInA) found that 40.8% of formal borrowers used loans for consumption and coping in 2026, up from 31.7% in 2023. This shift indicates that more Nigerians are relying on loans to manage everyday financial pressure rather than investing in businesses or productive assets. The survey covered adults across Nigeria's thirty-six states and the Federal Capital Territory, with oversight from the National Bureau of Statistics.
The share of formal borrowers using loans for productive enterprises fell from 40.2% to 34.3% over the same period. This decline suggests that fewer Nigerians are using loans to expand businesses or acquire assets that could generate additional income. Instead, many are using loans to cover essential expenses such as food, rent, school fees, and medical bills. This trend is concerning, as it may lead to a cycle of debt that is difficult to escape.
Formal credit use itself increased, with 10% of Nigerian adults accessing formal credit, up from 6% in 2023. This expansion is part of a broader improvement in financial inclusion. However, the EFInA survey found that only a small fraction of Nigerian adults were classified as financially healthy. This puts the credit figures in context, highlighting that access to credit alone does not necessarily translate to financial security.
A significant share of formal borrowers, 45.8%, reported difficulties repaying their loans. This is a worrying trend, as it indicates that many Nigerians are struggling to manage their debt obligations. For households whose income is already being absorbed by regular expenses, a new loan repayment becomes another fixed obligation, which can lead to a cycle of debt.
The EFInA survey also found that credit access has expanded among groups that traditionally had less access to formal lenders, including informally employed Nigerians, young adults, and farmers. While this is a positive development, it also raises concerns about the potential for over-indebtedness among these groups. If not managed carefully, increased access to credit can lead to financial distress.
The shift in borrowing purposes and the level of repayment difficulty are relevant to credit risk for lenders. For households, the more immediate issue is what happens after the money arrives. If the loan finances an income-generating activity, repayment may come from the additional income. However, if it pays for expenses that return every month, the repayment still has to come from income that may not have increased.
Nigeria's credit market is reaching more households, but the EFInA data suggests that the next question is whether that credit is helping them move forward or simply giving them more room to cope. The survey's findings have implications for policymakers, lenders, and households, highlighting the need for careful management of credit and financial inclusion initiatives to ensure that they promote financial stability and security.
Key points
- 40.8% of formal borrowers used loans for consumption and coping in 2026, up from 31.7% in 2023.
- 45.8% of formal borrowers reported difficulties repaying their loans.
- Formal credit use increased to 10% of Nigerian adults, up from 6% in 2023.