Nigeria's banking sector has come a long way since the country's independence in 1960. At that time, the economy was largely driven by agriculture and commodity exports, with cocoa, groundnuts, and palm produce generating over three-quarters of the country's foreign exchange. The Central Bank of Nigeria (CBN) was established in 1958 and began operations in 1959, while the Banking Act of 1969 strengthened regulation and supervision of the sector.
The 1986 Structural Adjustment Programme marked a significant turning point for Nigeria's banking industry, as it liberalized banking and encouraged new entrants. However, this rapid expansion was followed by widespread distress, leading to the establishment of the Nigeria Deposit Insurance Corporation (NDIC) in 1988 to protect depositors and promote confidence in the banking system. The Failed Banks (Recovery of Debts) and Financial Malpractices Act of 1994 introduced tougher measures against distressed banks.
A major consolidation exercise in 2004-2005, led by the CBN under Prof Charles Soludo, raised the minimum capital for commercial banks from N2 billion to N25 billion, forcing banks to merge or acquire one another. This reduced the number of banks from 89 to 25 and created larger institutions capable of supporting larger transactions and absorbing economic shocks. The 2009 banking crisis, triggered by weaknesses exposed during the global financial crisis, led to another round of reforms focused on corporate governance, risk management, and financial stability.
The Nigerian banking sector has faced repeated tests since independence, including weak corporate governance, non-performing loans, foreign-exchange volatility, and sudden changes in regulation. The 2009 banking crisis demonstrated that increased capital alone could not guarantee stability, and poor risk management and weak oversight had allowed some institutions to expand aggressively without adequate controls. Subsequent reforms strengthened supervision, improved resolution mechanisms, and reinforced the role of the NDIC.
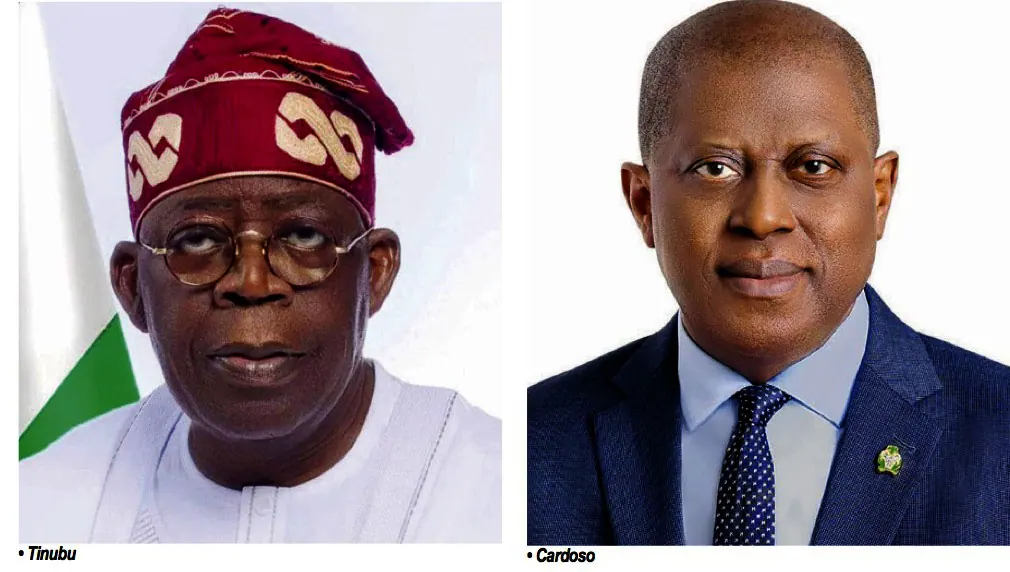
In recent years, the banking sector has witnessed rapid growth in electronic banking, mobile money, ATMs, cards, internet banking, and instant payments, fundamentally changing how Nigerians conduct transactions. The CBN, under Olayemi Cardoso, began another reform phase in 2023, including stronger supervision and efforts to strengthen banks' capital positions. In March 2024, the CBN raised minimum capital requirements to N500 billion for banks with international authorization, N200 billion for national banks, and N50 billion for regional banks.
The latest recapitalization exercise has strengthened capital buffers and improved the sector's capacity to absorb shocks. According to the CBN, 33 banks met the March 31, 2026 deadline and raised a combined N4.65 trillion in new capital, with 72.55% of the funds coming from domestic sources and 27.45% sourced internationally. This development is expected to enable banks to finance large transactions and support economic growth.
Key points
- The Nigerian banking sector has undergone significant transformations since independence in 1960, driven by changes in regulation, technology, and economic conditions.
- The sector has faced repeated tests, including weak corporate governance, non-performing loans, and foreign-exchange volatility, but has emerged stronger and more technologically sophisticated.
- The latest recapitalization exercise has strengthened capital buffers and improved the sector's capacity to absorb shocks, enabling banks to finance large transactions and support economic growth.