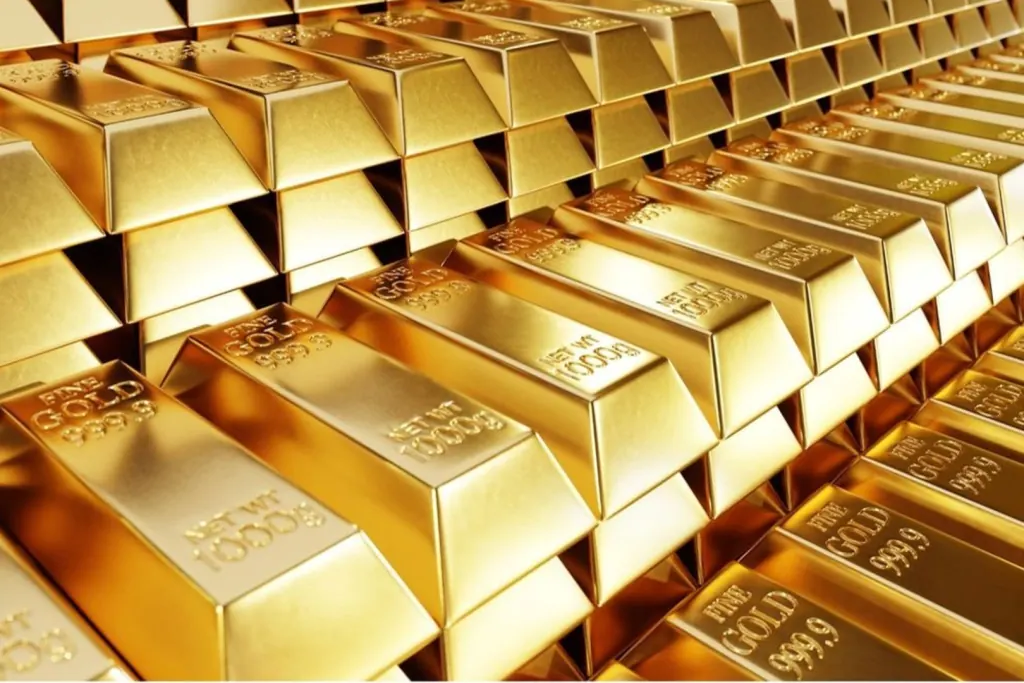
Central banks worldwide have been on a gold-buying spree, adding around 1,000 tonnes of gold each year over the past four years, roughly double the rate of the previous decade. According to the World Gold Council, 89 per cent of reserve managers expect global central-bank gold reserves to rise within the next year. A record 45 per cent expect their own institutions to increase holdings, indicating a significant shift in how they view national reserve security and robustness.
Geopolitical risk is a key factor fuelling renewed interest in gold. Conflicts, sanctions, trade disputes, and tensions among major powers demonstrate how political decisions impact financial connections. Gold is unique because it isn’t someone else’s liability, providing governments with an asset to diversify their holdings amid uncertain geopolitical conditions. The World Gold Council's 2026 survey shows that central banks increasingly view gold as a strategic asset, influenced by economic and geopolitical uncertainties, inflation, and diversification.
The US dollar remains dominant in global trade, finance, payments, and foreign-exchange reserves. However, reserve managers are focused on lowering excessive concentration in any one asset or currency. Gold provides a way to diversify reserves, and a nation can hold substantial dollar reserves while increasing gold holdings. This strategy offers additional protection against currency volatility, external funding difficulties, and global financial crises for emerging economies.
Historically, gold has proven to be a dependable store of value, particularly when investors are concerned about inflation, currency devaluation, or diminishing purchasing power. These concerns have intensified in the current environment, with governments experiencing significant fiscal pressures, changing interest rate forecasts, commodity-price volatility, and rising geopolitical risks. The World Gold Council predicts that ongoing factors will continue to increase gold investment demand.
Evidence from China and emerging markets underscores the trend’s strategic importance. The People’s Bank of China reportedly added 40 tonnes of gold reserves in the first half of 2026 and continued purchases in July. Poland, Uzbekistan, and Kazakhstan have been significant gold accumulators, with Poland adding 102 tonnes of bullion gold in 2025, totalling 550 tonnes, which makes gold about 28 per cent of its reserves.
The growing attention to where gold is stored is also noteworthy. In September 2026, the Netherlands revealed that it moved around 86 tonnes of gold from New York and Ottawa to London, citing better liquidity, easier trading, and increased readiness for severe crises. This highlights that reserve managers are now paying more attention not just to the amount of bullion gold they hold but also to its storage location and accessibility in times of crisis.
The bullion approach has its limitations, and there’s an important caveat to bear in mind. Gold does not generate interest or dividends, and holding large amounts can incur opportunity costs when interest rates are high. Moreover, gold prices tend to be highly volatile. The 2025 experience highlights this complexity, as central banks bought 863 tonnes of bullion gold worldwide, much more than the 473 tonnes average from 2010 to 2021.
Key points
- Central banks are treating gold as a strategic instrument, driven by economic independence, diversification, and safeguarding against an unstable global financial system.
- The US dollar remains dominant, but reserve managers are increasingly focused on lowering excessive concentration in any one asset or currency.
- Gold-producing countries, particularly in Africa, can improve how they link mineral output to national reserves, given the continent's substantial gold resources.