The Insurance Regulatory Authority (IRA) of Kenya has implemented new regulations to limit the buying of foreign reinsurance. Insurers are now required to exhaust local capacity before seeking approval to place Kenyan risks with foreign reinsurers. This move aims to strengthen local reinsurance capacity as insurers begin renewing their reinsurance contracts for 2027. The IRA has increased the mandatory reinsurance cession to Kenya Reinsurance Corporation (Kenya Re) to 25 percent from 20 percent.
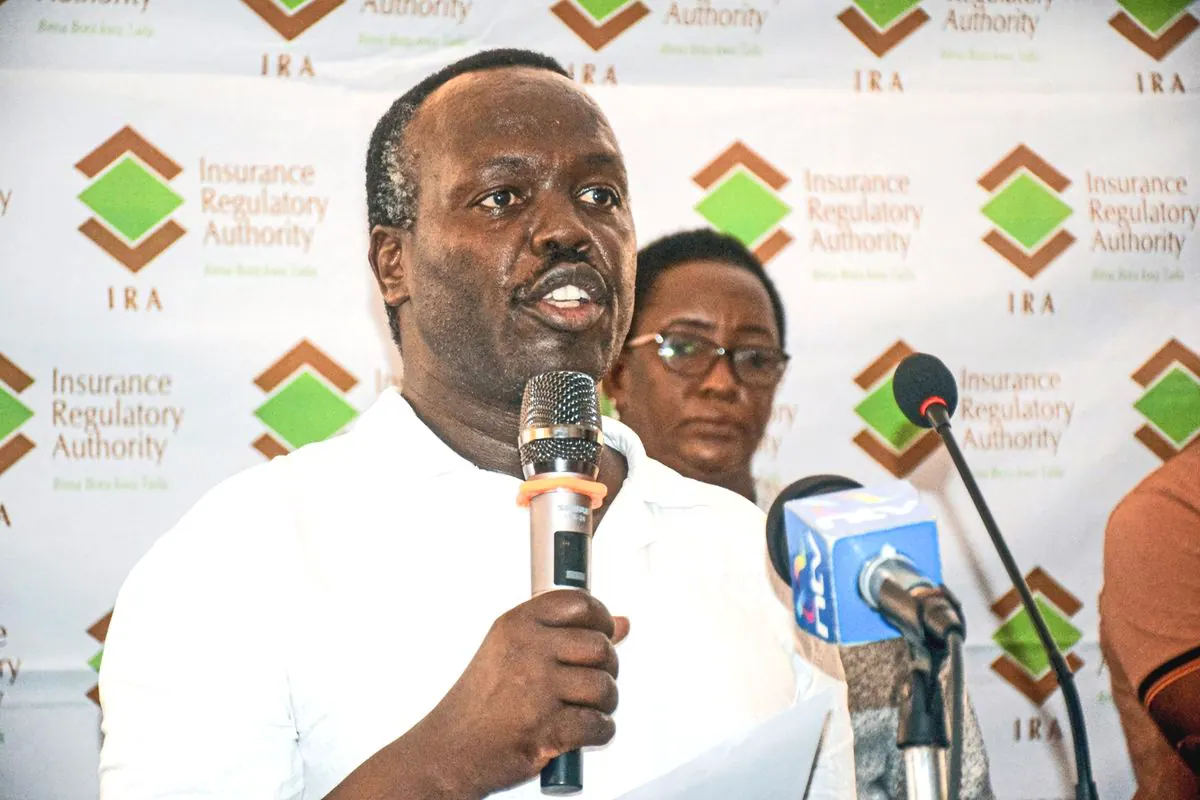
The new regulations, announced in a circular dated September 16, are part of the IRA's efforts to ensure that insurers comply with reinsurance rules. Insurers must now arrange reinsurance programs with local reinsurers before seeking approval for foreign reinsurance. The IRA's chief executive, Godfrey Kiptum, emphasized that insurers must adhere to these rules, warning that those who do not will not be allowed to write new business from January 1, 2027. Insurers are required to begin negotiations early and file final cover notes with the IRA by October 31.
The Kenyan insurance market has several local reinsurers, including Continental Reinsurance, East Africa Reinsurance, Ghana Reinsurance, WAICA Reinsurance (Kenya), and ZEP-RE. The IRA's intervention aims to curb the offshore placement of Kenyan insurance risks. Insurers transfer part of their risks to reinsurers to reduce their exposure to massive or catastrophic losses. The regulator's move is expected to give local reinsurers a more prominent role in Kenya's insurance market.
The 25 percent mandatory business for Kenya Re follows amendments to the country's reinsurance rules. Every insurer is required to reinsure with Kenya Re a quarter of each of its reinsurance treaties relating to general business. This requirement will only cease if Kenya Re is privatized. Kenya Re is 60 percent owned by the government and is listed on the Nairobi Securities Exchange.
The IRA has raised concerns about non-compliance practices by insurers, including late submission of reinsurance arrangements for regulatory approval and arranging reinsurance through unregulated brokers. Some insurers have also been entering into reinsurance arrangements with lowly rated or unrated reinsurers and reinsuring with foreign firms not registered under the Insurance Act. Insurers have been warned to avoid concentrating more than 50 percent of a risk with a single reinsurer unless they provide justification for the placement.
The IRA is also tightening scrutiny on insurers that enter into reinsurance contracts but fail to honour payments. Insurers submitting their 2027 arrangements must provide proof that reinsurance balances up to the second quarter of 2026 have been settled, or present an agreed payment plan with the reinsurers. Insurers will have to show evidence of actuarial certification of the adequacy and contractual certainty of reinsurance arrangements.
The new regulations require insurers to provide actuarial reports covering their five-year claims risk profile, changes in their reinsurance management strategy, the credit ratings of reinsurers, and the structure of reinsurance arrangements. Actuaries must give an opinion on the adequacy of insurers' retention levels and purchased reinsurance capacity, ceding commissions, minimum deposit premiums, and rates for non-proportional treaties. The IRA measures collectively tighten the conditions under which insurers can transfer risks to overseas markets.
Key points
- Insurers must exhaust local reinsurance capacity before seeking foreign reinsurance.
- The mandatory reinsurance cession to Kenya Re has been increased to 25 percent from 20 percent.
- Insurers who do not comply with the new regulations will not be allowed to write new business from January 1, 2027.