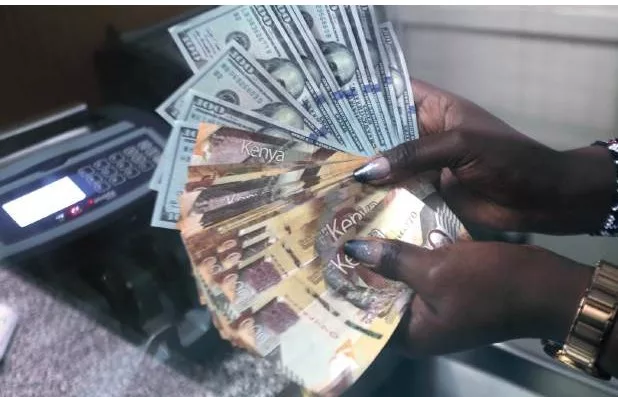
Kenya's financial inclusion story has been touted as a remarkable success, with millions of adults now able to access bank accounts, mobile money, digital credit, savings, insurance, and investment products. However, a closer look at the latest FinAccess survey reveals that access to financial services has not necessarily translated to financial security for many households. Despite having access to various financial products, many Kenyans still struggle to accumulate enough savings to withstand financial shocks.
The FinAccess survey shows that only a quarter of adults in Kenya could raise emergency funds within three days in 2024. This is a worrying trend, as it indicates that many households are not able to fall back on their savings during times of financial need. Instead, many households are forced to take on more debt to cope with financial shocks, which can lead to a cycle of debt and financial fragility.
The reliance on bank savings for emergencies has fallen sharply, while dependence on family, informal lenders, savings and credit cooperatives (Saccos), and other sources has increased. This shift towards informal sources of financial support highlights the vulnerability of many households in Kenya. For many households, a financial shock does not mean drawing down savings, but rather taking on another loan to make ends meet.
The problem of financial fragility is not limited to low-income households. Declining real wages, rising living costs, and expanding family obligations have squeezed households across income groups, leaving even higher earners struggling to make ends meet. Lifestyle inflation and recurring commitments have also contributed to the financial strain faced by many households.
Credit can be a useful tool for households to manage genuine emergencies, finance education, buy homes, or expand businesses. However, when borrowing becomes the permanent solution to inadequate disposable income, it can lead to financial distress. Kenya must therefore move beyond celebrating the number of people with accounts and wallets, and focus on ensuring that households can pay their bills, survive financial shocks, and save for retirement.
The government and financial institutions must work together to address the root causes of financial fragility, including low wages, high living costs, and inadequate financial planning. Financial inclusion should not merely make poverty easier to finance, but rather help Kenyans escape it. This requires a more nuanced approach to financial inclusion, one that prioritizes financial security and stability over mere access to financial products.
Ultimately, Kenya's financial inclusion success story needs a rethink. The country must prioritize financial security and stability, rather than just access to financial products. By doing so, Kenya can ensure that its financial inclusion efforts translate to meaningful economic benefits for its citizens, rather than just a temporary reprieve from financial hardship.
Key points
- Many Kenyan households are still financially fragile despite having access to financial products
- The reliance on informal sources of financial support has increased, highlighting the vulnerability of many households
- Financial inclusion should prioritize financial security and stability over mere access to financial products