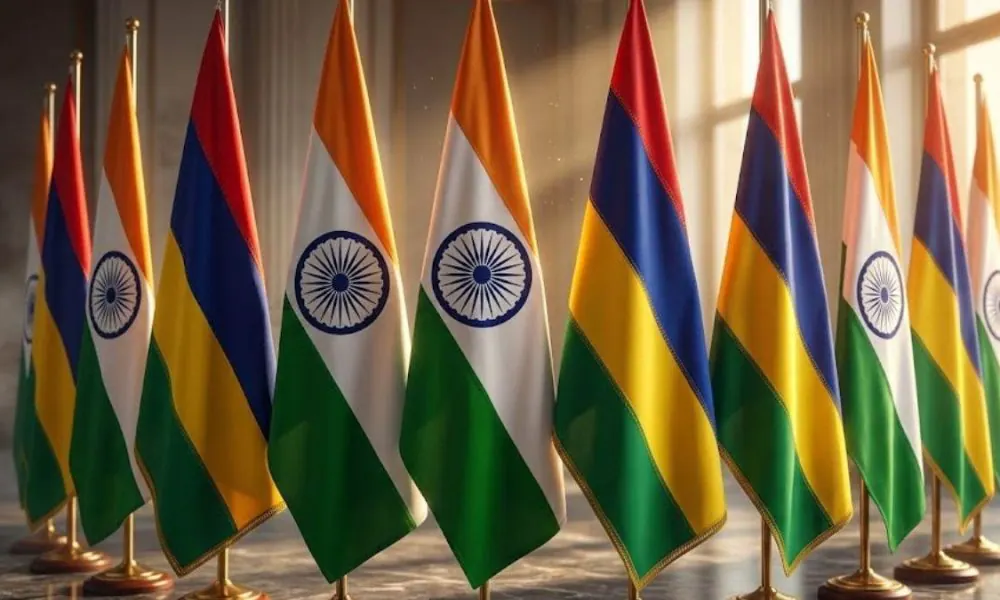
India has successfully renegotiated its tax treaties with Mauritius, Singapore, and Cyprus, allowing it to tax capital gains from investments in India at the source. Finance Minister Nirmala Sitharaman announced this development at the eighth International Tax Conference in Bengaluru. The treaties were amended to prevent the exploitation of loopholes and strengthen India's tax base. The changes aim to ensure that India can tax capital gains from share sales in Indian companies.
The previous framework allowed certain investors, particularly those from Mauritius, to claim that share-sale capital gains in Indian companies were taxable only in their resident nation. This limited India's taxation authority. To address these limitations, India amended its Mauritius tax treaty via a 2016 protocol. The changes ensured that share capital gains taxation for acquisitions made from April 1, 2017, would be shifted to the source country. Pre-existing investments were safeguarded under historical grandfathering provisions.
Similar modifications were applied to the Singapore and Cyprus pacts. The updated amendments include safeguards to curb treaty abuse, targeting entities established primarily for securing tax advantages. These safeguards restrict the available benefits for such entities. The changes reflect India's efforts to strengthen its tax regime and prevent tax evasion. The renegotiated treaties are expected to have a significant impact on India's tax revenue.
Finance Minister Sitharaman highlighted the broader scope of regulatory reform in India's international tax architecture. The introduction of the General Anti-Avoidance Rules (GAAR) aims to prevent tax avoidance. The adoption of the Multilateral Instrument (MLI) and the wider roll-out of the Advance Pricing Agreement (APA) programme are also part of these efforts. Additionally, new safe harbour provisions have been established to provide clarity on tax rates.
The renegotiated treaties with Mauritius, Singapore, and Cyprus are part of India's efforts to strengthen its tax base. The changes will help prevent tax evasion and ensure that India can tax capital gains from investments in the country. The treaties were amended to bring them in line with international best practices. The changes are expected to have a positive impact on India's economy.
The updated tax treaties reflect the changing global tax landscape. The OECD and G20 have been working to address tax avoidance and ensure that multinational corporations pay their fair share of taxes. India's efforts to renegotiate its tax treaties are part of this global effort. The changes will help India to better align its tax regime with international standards.
The renegotiated tax treaties with Mauritius, Singapore, and Cyprus are a significant development in India's tax policy. The changes will have a positive impact on India's economy and tax revenue. The Indian government is expected to continue its efforts to strengthen its tax regime and prevent tax evasion.
Key points
- India renegotiates tax treaties with Mauritius, Singapore, and Cyprus to tax capital gains from investments in India at the source.
- The treaties were amended to prevent the exploitation of loopholes and strengthen India's tax base.
- The changes reflect India's efforts to strengthen its tax regime and prevent tax evasion.