The Revenue Appeals Tribunal Eswatini's 2025/2026 Annual Report revealed that income tax-related matters constituted the bulk of disputes brought before the institution. This reflects the complexity of tax disagreements arising between taxpayers and the Eswatini Revenue Service. The report identified disputes involving complex corporate audits, transfer pricing adjustments, and statutory deductions as principal matters requiring intervention during the financial year ended March 31, 2026.
Income tax disputes accounted for 79% of the caseload, while value-added-tax (VAT) matters represented 21%. These income tax disputes centered on key provisions and amendments under the Income Tax Order, 1975, and the Income Tax (Amendment) Act, 2023. Issues identified included bad debt deductions, the reduction of the corporate income tax rate to 25%, and transfer pricing adjustments. These matters concern how taxable income is determined, which expenses may be deducted, and how transactions between related companies are assessed for tax purposes.
Transfer pricing concerns the prices charged in transactions between related companies or entities. Where the Eswatini Revenue Service and a taxpayer disagree over the pricing applied to such transactions, the resulting adjustments can become the subject of a tax appeal. Bad debt deductions concern the circumstances under which businesses may deduct debts considered irrecoverable when calculating taxable income. The prominence of these matters places corporate tax assessments and the interpretation of income tax legislation at the center of the Tribunal's work.
VAT disputes, accounting for 21% of cases, were attributed to disagreements surrounding mandatory VAT apportionment for mixed-use property developers and the tax treatment of zero-rated management services linked to international transport operations under the VAT Act, 2011. VAT apportionment becomes relevant where a business conducts activities involving both taxable and exempt supplies, requiring the appropriate determination of the input tax that may be claimed.
For property developers undertaking mixed-use developments, disagreements may arise over how VAT incurred on expenses should be apportioned between different activities. The Tribunal also identified disputes concerning the application of zero-rated VAT to management services associated with international transport operations. These highlight the complexities businesses can encounter when interpreting VAT provisions.
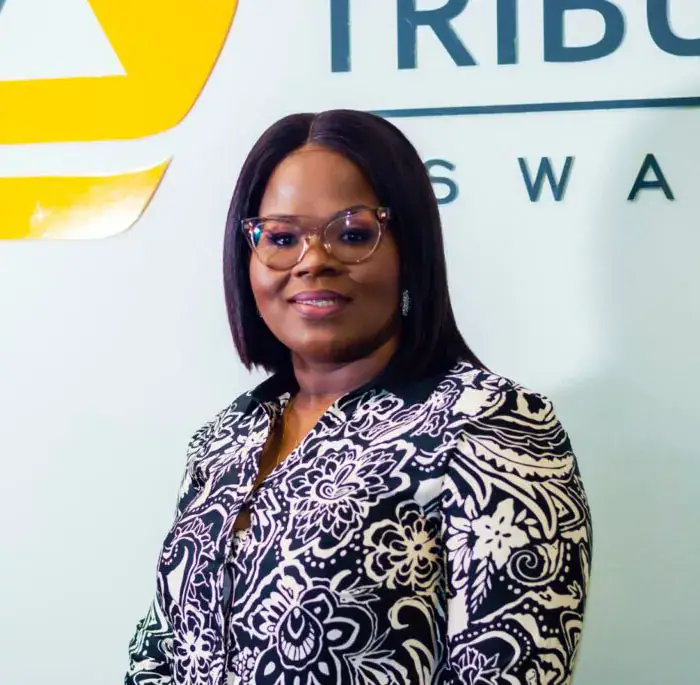
The CEO of the Revenue Appeals Tribunal Eswatini, Nelsiwe Hlophe, has overseen the handling of these complex tax disputes. The Tribunal's caseload reflects the critical role it plays in resolving tax disputes and providing clarity on tax legislation. The issues brought before the Tribunal have significant implications for businesses and taxpayers in Eswatini.
The Revenue Appeals Tribunal's work in resolving these disputes will continue to shape the tax landscape in Eswatini. As the business environment evolves, the Tribunal's role in interpreting tax laws and regulations will remain crucial. Taxpayers and businesses must navigate these complex issues to ensure compliance with tax laws and regulations.
Key points
- Income tax disputes accounted for 79% of cases before the Revenue Appeals Tribunal in Eswatini in 2025/2026.
- Corporate assessments and transfer pricing were key issues in income tax disputes.
- VAT disputes accounted for 21% of cases, with disagreements on VAT apportionment and zero-rated management services.
Reporting sources
- Income tax disputes dominate Revenue Tribunal caseload · Times of Swaziland