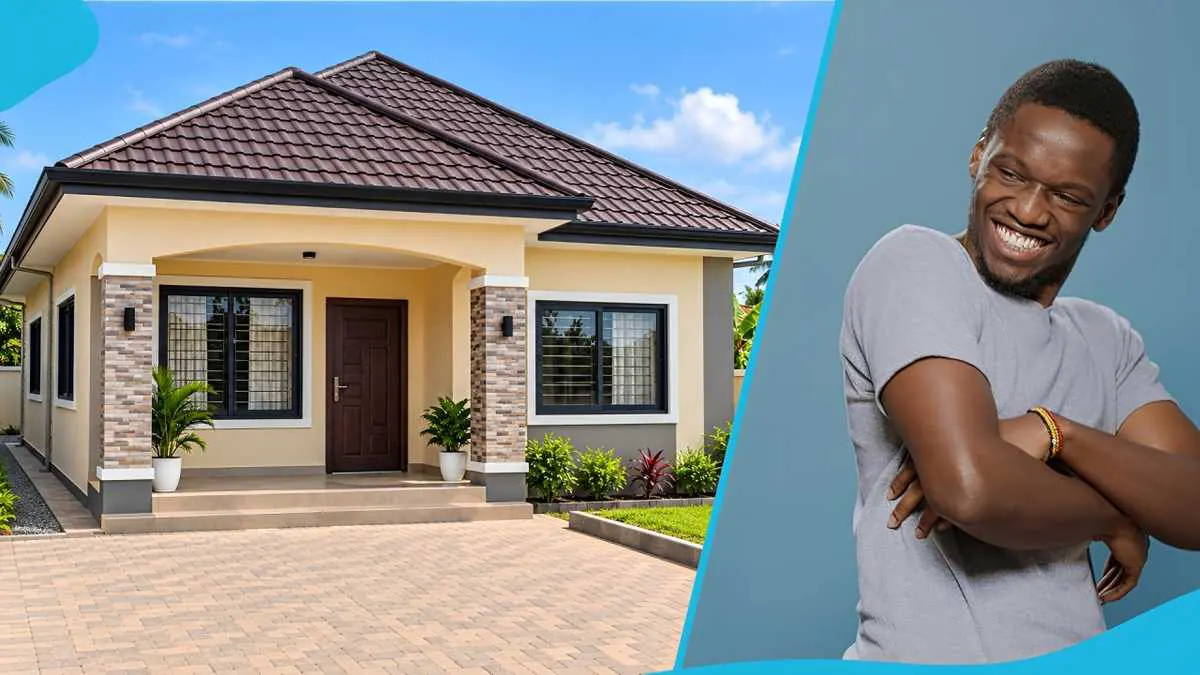
The National Homeownership Fund in Ghana has introduced a rent-to-own scheme aimed at helping low- and middle-income earners own homes. This scheme allows occupants to live in a house while making monthly payments that gradually build an ownership stake. The Fund's Affordable Housing Real Estate Investment Trust Rent-to-Own Scheme is designed to provide affordable monthly payments, helping participants build equity over time.
Under a typical rent-to-own arrangement, a property owner or housing organization enters into a long-term agreement with an occupant. The occupant moves into the house and makes an agreed payment every month, part of which covers the right to live in the property, while another portion is credited towards its purchase. This arrangement could benefit workers who have stable monthly incomes but struggle to raise a large deposit or qualify for a conventional bank loan.
The National Homeownership Fund is acquiring and converting inner-city apartments and housing units in different regions for the programme. The scheme is being implemented with asset management companies, which use investment funds to acquire properties and make them available under rent-to-own arrangements. This could allow a participant to live in the house while paying towards ownership instead of paying rent elsewhere and attempting to save for another property at the same time.
In August 2026, NHF Chief Executive Officer Prosper Hoetu announced that the rent-to-own programme had been reviewed to introduce more flexible payment terms and improve access to homeownership. However, he acknowledged that inadequate resources could limit the number of people who initially benefit from the programme. Workers must carefully study the agreement before joining any rent-to-own programme, confirming the full price of the house, the repayment duration, and the exact amount to be paid monthly.
Applicants must also know how much of each payment will count towards ownership and be aware of other expenses, including insurance, maintenance, property rates, service charges, legal fees, and administrative costs. These charges could make the monthly commitment higher than ordinary rent. The agreement should also explain what happens when a participant loses a job, misses payments, or decides to leave the scheme.
To qualify for a home loan, a worker earning GH¢2,500 net monthly could qualify for a mortgage of up to GH¢143,000, according to the National Homeownership Fund. The repayment could be about GH¢1,231.95 monthly over a maximum period of 20 years. Applicants would still have to meet the requirements of a participating bank before the mortgage is approved.
Prospective applicants should deal directly with the National Homeownership Fund or its officially approved partners to avoid fraudulent agents. A lawyer should examine the agreement and verify the ownership documents before any money is paid. Rent-to-own could offer workers a realistic path to homeownership without demanding the full price upfront, but its success will depend on the property's price, the monthly obligation, and whether the payments can be sustained for the entire agreement period.
Key points
- The National Homeownership Fund's rent-to-own scheme provides more flexible payment terms to help low- and middle-income earners own homes.
- The scheme allows occupants to build an ownership stake in a property while making monthly payments.
- Applicants must carefully study the agreement and be aware of all expenses and conditions before joining the rent-to-own programme.