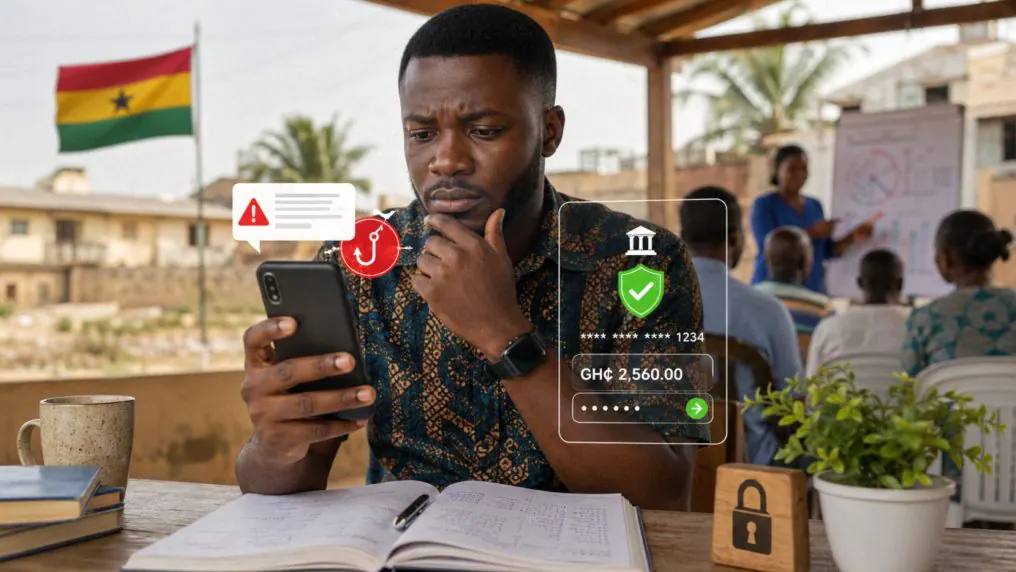
Ghanaian households are increasingly turning to Buy-Now-Pay-Later (BNPL) schemes to finance purchases of essential items, but this growing market hides a significant risk of debt-stacking. A family can take out multiple BNPL loans from different shops in a short period, without any lender knowing about the others. This can lead to a situation where multiple bills fall due at the same time, putting a strain on household finances.
The ease of access to BNPL schemes is a major contributor to the problem. Unlike bank loans, which require paperwork and income checks, BNPL purchases can be made quickly and easily, often using a simple USSD code. This makes it easy for households to take on more debt than they can handle. Retailers such as Electromart Ghana and MAXBUY, as well as MTN's Pick and Pay Later service, offer BNPL schemes for a range of products, from smartphones to fridges and generators.
The consequences of missing a payment can be severe. For example, MTN's scheme can remotely lock a financed phone within 24 hours of a missed instalment, which can be disastrous for traders and small-business owners who rely on that phone to earn a living. Missed payments can also lead to spoiled food, collections visits, and strain between spouses. Women, who often carry primary responsibility for household budgeting, are disproportionately affected when repayment plans collide.
The problem is not limited to individual households. Ghana's credit system struggles with data visibility, with lenders often not sharing information about borrowers' existing exposure. This can lead to a situation where households take on more debt than they can handle, and lenders are unaware of the risks. The Bank of Ghana's Directive for Digital Credit Services Providers, which came into effect on 1 November 2025, aims to address some of these issues, but it has limitations.
The Directive introduces licensing requirements, a minimum capital threshold of GH¢2 million, and a transaction cap of GH¢10,000, as well as daily reporting of loan data to credit bureaus. However, the cap applies per provider, not per household, meaning a borrower could still take on multiple capped loans from different lenders simultaneously. The Directive also requires providers to report lending data after the fact, but does not require them to query a borrower's existing debt with other providers before approving a new loan.
Experts say that the Directive does not go far enough to address the debt-stacking problem. To prevent debt-stacking, lenders need to be required to check a borrower's existing debt with other providers before approving a new loan. The Directive also does not mandate that lenders disclose the cash price of an item alongside its deferred-payment price, or set a minimum notice period before a financed device can be locked or repossessed.
The BNPL market in Ghana is expected to continue growing, but it is crucial that lenders, regulators, and policymakers take steps to address the debt-stacking risk. This includes implementing measures to ensure that lenders have access to data on borrowers' existing debts, and that households are protected from the consequences of missed payments. By taking a proactive approach, Ghana can mitigate the risks associated with BNPL and ensure that this growing market benefits households and the broader economy.
Key points
- Ghana's Buy-Now-Pay-Later market poses a significant risk of debt-stacking, with lenders approving multiple loans without checking existing obligations.
- The Bank of Ghana's Directive for Digital Credit Services Providers aims to address some of the issues, but it has limitations and does not go far enough to prevent debt-stacking.
- Experts say that lenders need to be required to check a borrower's existing debt with other providers before approving a new loan to prevent debt-stacking.