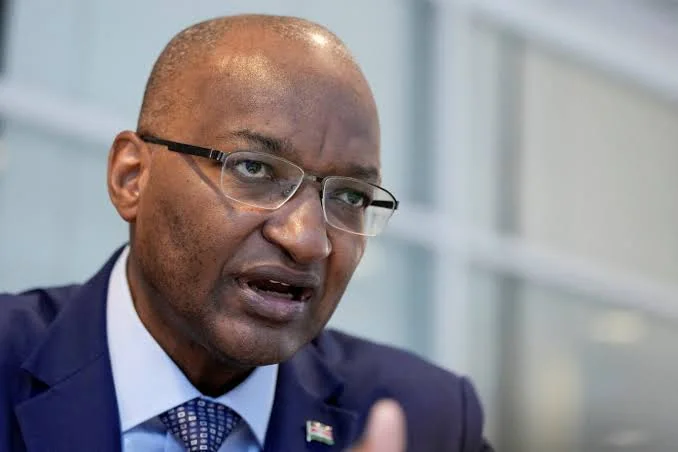
Former Central Bank of Kenya Governor Patrick Njoroue has publicly expressed concerns over the draft National Payment System Bill 2026, citing the need for clearer principles on consumer data protection, competition, and financial inclusion. The Bill, jointly prepared by the National Treasury and the Central Bank of Kenya, aims to replace the 2011 Act with a framework promoting interoperability, innovation, and consumer protection. Njoroue's comments come as the country seeks to enhance its payments ecosystem.
Njoroue emphasizes that consent for data sharing must be explicit, informed, and revocable, and calls for stronger digital-identity safeguards to ensure that data sharing is truly voluntary. He notes that while the Bill requires providers to safeguard funds, disclose fees, and set up complaint mechanisms, it lacks clear rules for fraud liability, redress, and the use of personal data. These gaps remain major pain points for users, highlighting the need for more comprehensive regulations.
On competition, Njoroue warns that vertically integrated groups could engage in discriminatory pricing, urging a clearer separation between payment operations and other group activities. He insists that third-party services be offered on fair, reasonable, and non-discriminatory terms. This, he believes, will promote a level playing field and encourage innovation in the payments sector. The Bill's provisions on competition will be crucial in shaping the industry's future.
Njoroue also stresses that the Bill's inclusion agenda should directly address rural connectivity gaps, social norms limiting women's access, identification challenges for youth and marginalized groups, and the high cost of mobile devices and data. He argues that these issues must be tackled to ensure that the benefits of the new payments framework are accessible to all Kenyans. The Central Bank and National Treasury must consider these concerns when finalizing the Bill.
The former CBK Governor also highlights the need for explicit recognition of agent interoperability, allowing customers to transact across providers and agents to manage combined liquidity. He questions the treatment of wallet income, proposing that balances be treated as customers' property with regular bonus payouts after operational costs. Additionally, Njoroue suggests that the Bill should provide for a secure offline-payment capability to protect users during network outages.
Njoroue's concerns also relate to the Bill's provision allowing the Central Bank to own or operate market infrastructure. He notes that the upcoming instant-payment system will be a critical test of how government participation is governed. The Central Bank's role in the payments ecosystem must be carefully defined to ensure that it promotes innovation and competition while maintaining financial stability.
Overall, Njoroue acknowledges the draft's direction but insists that substantive amendments are required before Kenya adopts the new payments framework. His comments are a significant contribution to the ongoing debate on the future of Kenya's payments sector. The National Treasury and Central Bank of Kenya must consider Njoroue's suggestions as they finalize the Bill.
Key points
- The National Payment System Bill 2026 needs clearer rules on data protection, competition, and financial inclusion.
- Former CBK Governor Patrick Njoroue urges stronger digital-identity safeguards to ensure that data sharing is truly voluntary.
- The Bill's provisions on competition and inclusion must be strengthened to promote a level playing field and accessible benefits for all Kenyans.