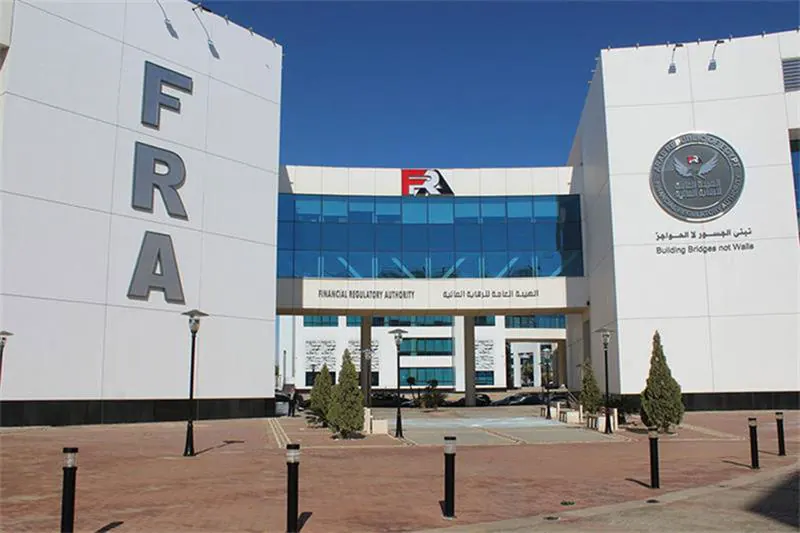
Egypt's Financial Regulatory Authority (FRA) has issued a circular to insurance companies, mandating them to enhance transparency on gold-linked investment insurance policies. The circular requires insurance companies to fully disclose to customers the nature of the insurance policy, its related benefits, risks, and material terms before entering into a contract. This move aims to improve market oversight and protect consumer rights across the country's non-banking financial activities.
The circular also prohibits false marketing and mandates insurance companies to declare whether the policy has any investments or strategies linked to gold or any other investment asset. The fund or investment manager must also be disclosed. Insurance companies are prohibited from using misleading marketing methods or statements that could confuse clients by conflating the insurance product with deposits, accounts, or other banking products or services.
The FRA identified negative practices and customer complaints regarding the marketing of investment-linked insurance products with savings vehicles, investment instruments, or banking products and services through banking channels. The circular forbids the inclusion of incorrect or inaccurate information in marketing materials or data that could create a perception inconsistent with the product's true nature and the terms approved by the FRA.
The new regulations require insurance companies to document the customer's understanding of the product's nature before finalizing the contract. This includes confirming that the customer has reviewed the policy's material terms and conditions, acknowledges the nature of the policy, and confirms disclosure of information sufficient to understand the product's nature.
Companies must also review the materials, forms, and marketing methods used to distribute their products through banking channels and implement internal measures and controls to ensure compliance. They are required to submit a report to the FRA within one month detailing the measures taken, along with the customer declaration form to be used in contracting processes.
This move is part of the FRA's efforts to enhance its regulations and increase transparency while verifying customer data to develop Egypt's non-banking financial sector. The sector is an important source of financing for households, consumers, and private-sector investment outside the traditional banking system.
The FRA has been bolstering its efforts to regulate the market, having issued two circulars last month banning the financing of gold and other precious metal products and requiring consumer finance firms to submit quarterly data on interest rates and administrative fees. The authority aims to enable clients to make informed decisions, as gold is considered a safe haven for investments rather than a consumer good eligible for consumer financing.
Key points
- The FRA's new circular aims to enhance transparency and protect consumer rights for gold-linked investment insurance policies.
- Insurance companies must fully disclose the nature of the insurance policy, its benefits, risks, and material terms before entering into a contract.
- The circular prohibits false marketing and misleading marketing methods that could confuse clients.