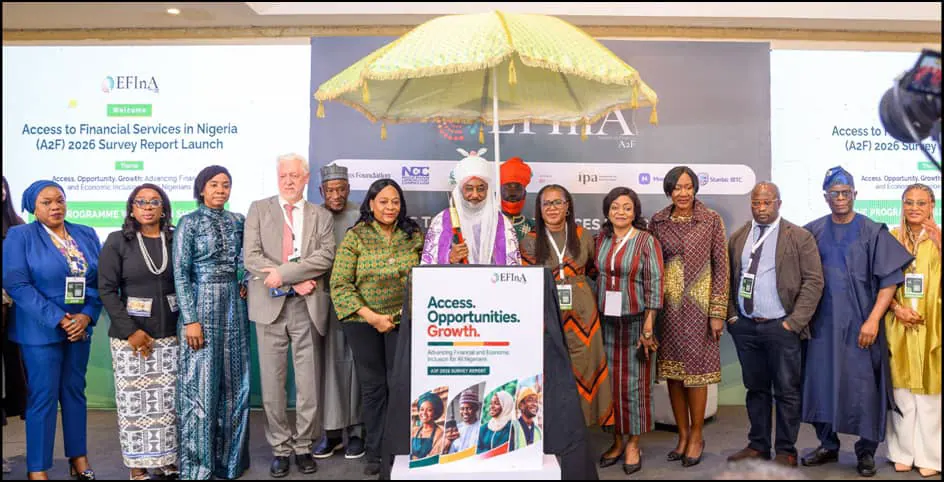
Nigeria has made significant progress in financial inclusion, with 79% of adults now having access to formal financial services, representing about 94.2 million people. This development is attributed to the rapid expansion of digital financial services, which has drawn more Nigerians into the formal financial system. The Enhancing Financial Innovation and Access (EFInA) released the findings of its latest Access to Financial Services in Nigeria (A2F) Survey in Lagos.
The survey revealed that formal financial inclusion has climbed to 73%, equivalent to about 87.2 million adults, surpassing the 70% target set under the National Financial Inclusion Strategy. The growth in financial inclusion is largely driven by digital channels, with 64.4% of Nigerian adults now using digital financial services, up from 45% in 2023 and 34% in 2020. This significant shift in Nigeria's financial inclusion landscape is a positive development for the country's economy.
The A2F Survey was unveiled under the theme, "Access. Opportunity. Growth: Advancing Financial and Economic Inclusion for All Nigerians," at an event attended by government officials, regulators, financial institutions, development partners, and civil society organizations. The event provided a platform for stakeholders to discuss the progress made and the challenges that lie ahead in Nigeria's financial inclusion journey.
Board Chair of EFInA, Dr. Agnes Olatokunbo Martins, noted that the survey's value lies in its ability to provide insights into the lives of individuals behind the numbers. She cautioned against designing solutions based on national averages, emphasizing that financial needs and experiences differ by income, gender, geography, age, and economic activity. Martins stressed the importance of understanding the nuances of financial inclusion to develop effective solutions.
In a keynote address delivered on behalf of the Governor of the Central Bank of Nigeria (CBN), Dr. Aisha A. Isa-Olatinwo, CBN, highlighted the importance of the survey's findings in policy design, market development, consumer protection, and targeting reforms. She emphasized that the policy challenge now is to ensure meaningful usage, affordability, reliability, safety, trust, and measurable improvement in financial health, rather than simply expanding access points.
The Director-General of the National Pension Commission, Ms. Omolola Oloworaran, welcomed the rise in pension participation from 8% of adults in 2023 to 9.1%. However, she noted that there is still a significant gap in pension coverage, with roughly nine out of every ten Nigerians not covered for their retirement. Oloworaran invited EFInA to work with the Commission on a dedicated pension inclusion model.
The Research Lead at EFInA, Dr. Oluwatomi Eromosele, noted that the survey's findings provide valuable insights into Nigeria's financial inclusion landscape. The survey's results will inform policy decisions and guide the development of effective solutions to address the remaining challenges in financial inclusion. The growth in digital finance and pension participation are key areas of focus for stakeholders.
Key points
- Nigeria's financial inclusion rate has risen to 79%, representing about 94.2 million adults.
- Digital finance is driving access to formal financial services, with 64.4% of Nigerian adults now using digital financial services.
- Formal financial inclusion has climbed to 73%, equivalent to about 87.2 million adults, surpassing the 70% target set under the National Financial Inclusion Strategy.